
What if the easiest car to buy upfront becomes the hardest one to afford month after month? If you’re searching for low down payment cars St Louis MO, a smaller amount due at the dealership may make a vehicle feel more accessible, especially when savings are limited. But the down payment is only one part of the cost. A promotional offer doesn’t tell you what you’ll pay over the full loan.
It’s reasonable to want dependable transportation without stretching your monthly budget or knowing exactly how a lender will assess your credit. Compare the vehicle, financing terms, and ongoing ownership costs together rather than choosing based on the upfront amount alone.
This guide explains what a low down payment does and doesn’t mean, what to include in your car budget, and how to compare financing choices. You’ll also find practical steps for exploring pre-owned sedans, SUVs, trucks, and vans around St. Louis, including budget-focused options from 111 Auto Sales LLC in nearby Pontoon Beach. Financing terms vary by vehicle and buyer, so review the full figures before deciding what fits.
Key Takeaways
- A low upfront payment doesn’t guarantee a low total cost. Compare financing details before deciding what fits your budget.
- Review the down payment, amount financed, monthly payment, and loan duration together to understand how each affects the overall plan.
- Build a complete ownership budget that includes insurance, fuel, maintenance, and emergency savings, not just the car payment.
- Prepare for low down payment cars St Louis MO shopping by setting a budget, identifying your vehicle needs, and gathering accurate application information.
- Explore pre-owned sedans, SUVs, trucks, and vans at 111 Auto Sales LLC in Pontoon Beach, serving St. Louis and nearby Metro East shoppers.
Low Down Payment Cars in St. Louis, MO: What the Offer Really Means
Low down payment cars St Louis MO are used vehicles that may be purchased with a smaller upfront contribution, depending on the vehicle, financing terms, and buyer’s qualifications. There’s no universal dollar amount that makes a down payment “low,” and the phrase doesn’t guarantee that the car will cost less overall.
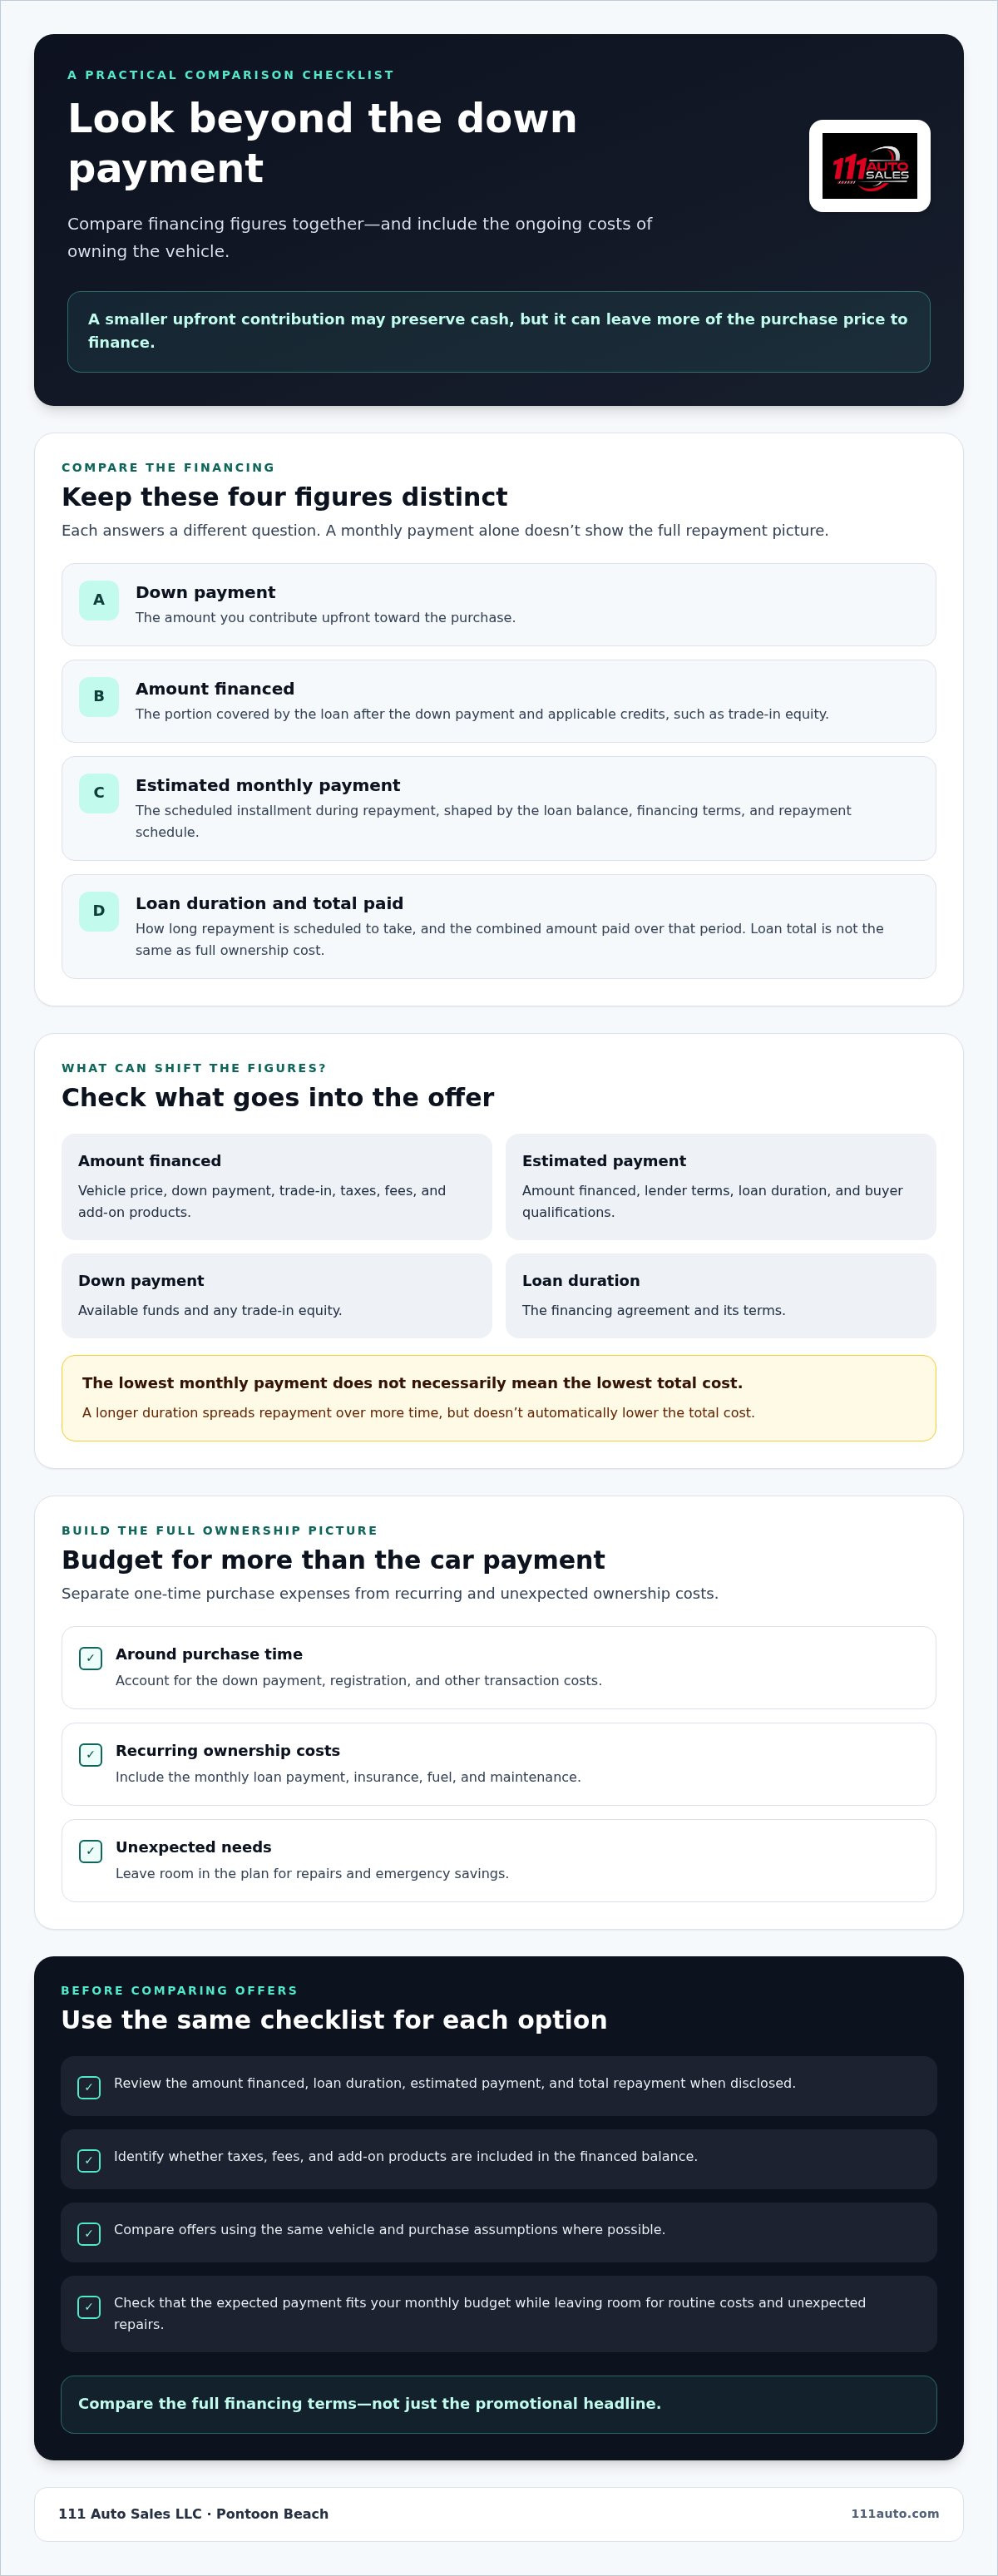
Keep these four figures distinct when comparing an offer:
- Down payment: The amount you contribute upfront toward the purchase.
- Amount financed: The portion covered by the loan after the down payment and any applicable credits, such as trade-in equity.
- Monthly payment: The scheduled installment, based on the loan balance, financing terms, and repayment schedule.
- Loan duration and total paid: The time allowed to repay the loan and the combined amount paid over that period. The loan total is different from the full cost of owning the vehicle.
These figures work together, but they answer different questions. A smaller down payment can leave more of the purchase price to finance. The monthly payment alone won’t show how long repayment lasts or how much you’ll pay across the full loan. For a neutral introduction to how car financing works, review the differences between financing arrangements before comparing specific offers.
What does a low down payment on a used car mean?
The down payment reduces the amount that needs to be financed. A lower upfront contribution may preserve cash for other needs, but it can also leave a larger loan balance than a larger down payment would. Promotions may apply only to certain vehicles or conditions. The amount offered and financing terms can vary, and an advertised offer doesn’t establish what every buyer will qualify for.
Why the upfront amount is only one part of affordability
Cash due at purchase is a one-time expense. Monthly loan payments recur, while insurance, fuel, maintenance, and repairs add to the ongoing cost of keeping a car. Registration and other transaction costs can also affect the amount needed around purchase time. Include these expenses in your plan rather than judging affordability by the initial payment alone.
Before focusing on the smallest amount due upfront, consider whether the expected payment fits your monthly budget and leaves room for routine costs and unexpected repairs. Compare the full financing terms, not just the promotional headline. A manageable purchase should leave flexibility for ownership expenses, too.
How Down Payment, Monthly Payment, and Loan Terms Work Together
To compare low down payment cars St Louis MO offers clearly, look at how the figures interact rather than treating a quoted monthly payment as the whole deal. Estimates can change with the vehicle price, lender terms, buyer qualifications, and any trade-in. Use this table to organize the figures for each option:
| Financing detail | What it tells you | What can affect it |
|---|---|---|
| Down payment | The amount you contribute upfront. | Your available funds and any trade-in equity. |
| Amount financed | The balance covered by the loan. | Vehicle price, down payment, trade-in, taxes, fees, and add-on products. |
| Estimated monthly payment | The scheduled amount due during repayment. | Amount financed, lender terms, loan duration, and buyer qualifications. |
| Loan duration | How long repayment is scheduled to take. | The financing agreement and its terms. |
How does a larger or smaller down payment affect financing?
A larger down payment generally reduces the amount you need to finance, all else being equal. A smaller contribution may preserve savings, but it can leave a larger balance to repay. Depending on the financing terms, that could affect the payment or total repayment. These are general relationships, not guarantees: the final figures depend on the vehicle and the buyer’s application.
Changing one factor can shift the others. A trade-in with equity may reduce the balance financed, while taxes, fees, or optional products may increase it. A longer loan duration can spread repayment over more time, but it doesn’t automatically lower the total cost. The lowest monthly payment does not necessarily mean the lowest total cost.
Which financing details should shoppers compare?
Review the amount financed, loan duration, estimated payment, and total repayment when disclosed. Identify what’s included in the financed balance so you can see how taxes, fees, and add-ons affect the figures. Compare offers using the same vehicle and purchase assumptions where possible. The Consumer Financial Protection Bureau provides tools for smart auto financing to help shoppers understand auto loans and assess their options.
For a closer look at financing considerations for a specific vehicle type, read this guide to used sedan financing in Pontoon Beach. You can also explore used-vehicle options at 111 Auto Sales LLC while comparing vehicle choices and financing with your overall plan in mind.
Does a Low Down Payment Make a Used Car Affordable? Check the Full Budget
No. A small amount due at purchase can make a vehicle easier to consider, but it doesn’t automatically make the car affordable. A realistic decision accounts for recurring ownership costs, your existing bills, and a cushion for unexpected expenses. That broader view matters more than the upfront figure alone when comparing low down payment cars St Louis MO.
What costs should you include beyond the down payment?
Before choosing a vehicle, map out the costs you’ll face at purchase and over time. Include:
- Monthly payment: Check that it fits alongside existing financial commitments.
- Insurance: Account for the coverage you’ll need for the vehicle.
- Fuel: Consider your regular driving, not just occasional trips.
- Maintenance and repairs: Plan for routine upkeep and possible repair needs.
- Taxes and transaction charges: Include these in your purchase budget rather than treating them as surprises.
- Emergency savings: Keep room for unplanned vehicle expenses so one repair doesn’t disrupt other bills.
A trade-in may reduce the amount you need to finance if it has equity, but its value and the transaction details affect how it applies. Treat any trade-in estimate as part of the calculation, not as guaranteed cash available for the down payment. The Federal Trade Commission’s guide to how down payments affect car loans offers more context on considering the loan alongside the vehicle’s overall cost.
How can you decide what payment fits your budget?
Start with take-home income, then subtract regular obligations such as housing, utilities, debt payments, food, and savings. Set a personal ceiling for the car payment only after accounting for insurance, fuel, maintenance, and other ownership expenses. Leave some flexibility; a payment that uses every available dollar can make routine costs harder to manage.
Next, compare vehicles against that ceiling instead of stretching the budget to match a preferred model. If an SUV is on your list, this guide to used SUVs under $10,000 in Pontoon Beach offers related budget-focused shopping guidance.
Write down your budget before shopping, then compare the complete purchase and ownership picture for each vehicle. You can also browse used vehicles at 111 Auto Sales LLC as one step in finding an option that suits your needs and financial plan.
How to Prepare for Low Down Payment Car Shopping Near St. Louis
A little preparation can make shopping for low down payment cars St Louis MO more focused. Set your budget before comparing vehicles, and gather the information that can help you have a clear financing conversation. Credit history and application details may inform a financing review, but no single document or credit profile guarantees an outcome.
What should you prepare before discussing financing?
Use this short sequence to organize your next steps:
- 1. Set your budget. Decide what you can comfortably contribute upfront and what monthly amount fits alongside your other obligations and vehicle expenses.
- 2. Identify your vehicle needs. Consider your regular commute, passengers, cargo, and how you’ll use the vehicle.
- 3. Gather relevant information. Bring identification and accurate income, residence, and insurance information when discussing a financing application. Having current details ready can help you provide consistent answers.
- 4. Prepare questions. Ask how the amount financed, estimated payment, loan duration, and total repayment fit together. Clarify which taxes, fees, or other items are included in the figures you’re reviewing.
Organized information helps you discuss your circumstances clearly. Financing decisions depend on the application and relevant terms, so don’t assume that a particular income document, residence detail, or credit history guarantees approval.
How can you narrow down the right used vehicle?
Start with how you’ll use the car. A sedan may suit everyday commuting, while an SUV or van may better match passenger and cargo needs. A truck may fit work-related use. Compare pre-owned sedans, SUVs, trucks, and vans by practical requirements, then weigh each option against your budget, including the full payment and ownership costs.
St. Louis shoppers can broaden their search to include Pontoon Beach and nearby Metro East communities. If an SUV is on your shortlist, explore this guide to used SUV financing in Pontoon Beach for additional comparison guidance.
With your budget, vehicle priorities, and questions in hand, you can approach the search with a clearer plan. Explore pre-owned vehicles at 111 Auto Sales and compare your options against the needs you’ve identified.
Find Budget-Focused Used Cars and Financing Near St. Louis
For St. Louis shoppers, the search for low down payment cars St Louis MO can extend across the river to Pontoon Beach and nearby Metro East communities. 111 Auto Sales is a used-car dealership in Pontoon Beach with pre-owned sedans, SUVs, trucks, and vans, along with vehicle financing options. Its budget-focused selection includes vehicles under $10,000. Because price and financing terms vary by vehicle and buyer, consider each option individually rather than assuming every vehicle has the same upfront requirement or qualifies for identical terms.
What can local shoppers compare at 111 Auto Sales?
Start by matching the vehicle type to how you’ll use it. A sedan may suit commuting, an SUV can provide space for passengers or gear, a van may meet specific passenger or cargo needs, and a truck may work for hauling or job-related use. Think through your regular trips and practical requirements before narrowing your choices.
Then consider the vehicle and financing together. Compare the amount you’re prepared to contribute upfront with the estimated payment and other ownership costs. 111 Auto Sales offers financing options for shoppers considering a pre-owned vehicle. A careful comparison keeps the decision grounded in your budget, not just the vehicle category or initial amount due.
What is a practical next step for St. Louis shoppers?
Review the current used-vehicle inventory and make a short list of vehicles that fit your transportation needs. Note what matters most, such as passenger space, cargo capacity, or everyday commuting. Then revisit your budget and identify a comfortable upfront contribution and monthly payment range before discussing financing options.
Having those priorities ready can make conversations about vehicle choices and financing more focused. Shoppers from St. Louis and surrounding Metro East communities can include the Pontoon Beach location in their local used-car search. Compare the full ownership picture for each vehicle, and treat financing as one part of choosing a suitable option.
Ready to take a practical next step? Explore used vehicles at 111 Auto Sales.
Make Your Next Used-Car Search a Confident One
A low down payment can make a purchase feel more reachable, but it doesn’t tell you the full cost. Compare the amount financed, monthly payment, loan duration, and total repayment, then make room in your budget for insurance, fuel, maintenance, and unexpected expenses. Setting a comfortable payment limit before shopping helps keep the vehicle choice grounded in what works for you.
For shoppers looking for low down payment cars St Louis MO, preparation matters. Know your vehicle needs, upfront budget, and financing questions, and bring accurate information when discussing an application. Credit history and application details may inform a financing review, but terms vary.
111 Auto Sales is located in Pontoon Beach and serves shoppers across St. Louis and the Metro East. Its pre-owned sedans, SUVs, trucks, and vans come with financing options, and its budget-focused inventory includes vehicles priced under $10,000. Review current options as you plan your search.
Explore used vehicles and financing options at 111 Auto Sales. With a clear budget and a careful comparison, you can take your next step with greater confidence.
Frequently Asked Questions
How much should I put down on a used car?
There’s no single down-payment amount that fits every buyer or vehicle. Choose a contribution based on your available savings, the vehicle, financing terms, and application details, while keeping funds available for insurance and other ownership costs. Before deciding, compare the amount due upfront with the amount financed, estimated monthly payments, loan duration, and total repayment. A comfortable down payment shouldn’t leave you without room in your budget for ongoing expenses.
Can I get a car with a low down payment if I have bad credit?
Possibly, but financing decisions depend on factors such as credit history, income information, the vehicle, and the lender’s terms. A low down payment doesn’t guarantee approval or particular financing conditions. Prepare accurate application information and focus on a vehicle that fits your overall budget. If you receive financing terms, review the estimated payment, loan duration, and total repayment carefully before deciding whether the arrangement works for you.
Does a lower down payment mean a higher monthly payment?
It can, because paying less upfront may leave a larger amount to finance. The actual monthly payment also depends on the vehicle, loan duration, financing terms, and application details. Compare the payment with the total repayment and your other ownership costs, including insurance, fuel, and maintenance. Don’t assume that the smallest amount due at purchase will create the most affordable option over the full loan period.
What information should I bring when applying for used-car financing?
Bring accurate identification and be ready to provide relevant income and residence information requested for the application. It also helps to know your comfortable upfront contribution, monthly budget, and vehicle needs. Application requirements and review processes can vary, so answer questions accurately and read the financing terms carefully. Being prepared can make the discussion more organized, but no document or credit profile guarantees approval.
Can a trade-in reduce the amount I need to finance?
Yes, a trade-in may contribute value toward the purchase and affect the amount financed. The impact depends on the vehicle’s assessed value and transaction details. Review how the trade-in is reflected in the purchase figures, including the resulting amount financed and repayment terms. Then compare the revised figures with your budget for insurance, fuel, maintenance, and other ownership expenses before choosing a vehicle.
How can I find low down payment cars near St. Louis, MO?
Set a realistic upfront and monthly budget, then compare used vehicles that meet your transportation needs. Search in St. Louis and nearby communities, including Pontoon Beach, Granite City, Collinsville, Belleville, Maryville, Troy, Alton, Highland, O’Fallon, Glen Carbon, Swansea, and Cahokia. 111 Auto Sales offers pre-owned sedans, SUVs, trucks, and vans with financing options. Review the terms for the vehicle you’re considering, since advertised down payments aren’t universal offers or approval guarantees.


