
Did you know that as of August 2026, the average interest rate for a used car loan can reach 24.06% for buyers with poor credit? It's a staggering number that often makes finding reliable vehicle financing Maryville IL feel like an uphill battle. You likely feel the weight of high interest rates or the anxiety that your credit history might lead to an immediate rejection. It's frustrating when you just want a straightforward deal on a pre-owned truck or SUV that doesn't break your monthly budget.
We're here to change that experience by helping you master the local financing process to secure an affordable auto loan. You'll learn how to identify fair terms on vehicles under $10,000 and how to navigate recent Illinois regulations like Public Act 104-0516. This guide previews the steps to a transparent, stress-free approval process that puts you behind the wheel without the usual confusion between bank loans and dealer options. By the end, you'll have a clear roadmap to a payment plan that fits your financial reality perfectly.
Key Takeaways
- Learn why local independent dealerships offer more stability and flexibility than big-box franchises in the 2026 Metro East market.
- Discover how to audit your financial profile and calculate your debt-to-income ratio to ensure a smoother approval process.
- Understand the critical differences between dealership-arranged loans and high-risk title loans to protect your long-term financial health.
- Master a stress-free application process for vehicle financing Maryville IL by utilizing online tools before your physical test drive.
- Find out how to access specialized inventory under $10,000 paired with extended warranty options for complete peace of mind.
Understanding the Maryville Vehicle Financing Market in 2026
The Metro East auto market has seen significant shifts as we move through 2026. Economic factors in Madison County, such as local tax rates and shifts in employment, directly influence how lenders evaluate risk. For many residents, the choice isn't just about the car; it's about the structure of the loan. Understanding how car financing works is the first step in deciding between direct lending, where you secure a loan from a bank yourself, and dealership financing, where the dealer coordinates with multiple lenders on your behalf. In Maryville, the latter often provides a distinct advantage because local independent dealers have deeper roots in the community than large, corporate franchises.
Independent dealerships in the Maryville and Pontoon Beach area focus on long-term stability rather than high-volume corporate quotas. They often specialize in budget-friendly inventory, such as pre-owned trucks, SUVs, and sedans under $10,000. This focus allows them to build relationships with local credit unions and specialized lenders who understand the financial realities of Metro East families. Unlike big-box franchises that rely on rigid, automated scoring systems, local dealers can often present a more nuanced case to their lending partners when arranging vehicle financing Maryville IL.
Local Maryville Lenders vs. National Banks
Speed and flexibility define the local lending experience. National banks often operate with strict underwriting guidelines that don't account for specific local economic nuances. In contrast, local lenders use common sense underwriting. They look at the person, not just the credit score. Working with a dealership that maintains these local banking ties often results in faster approvals. Because the lender and the dealer are in close proximity, communication is direct. This proximity simplifies loan servicing and makes it easier to resolve questions about your vehicle financing Maryville IL throughout the life of the loan.
Current 2026 Interest Rate Environment
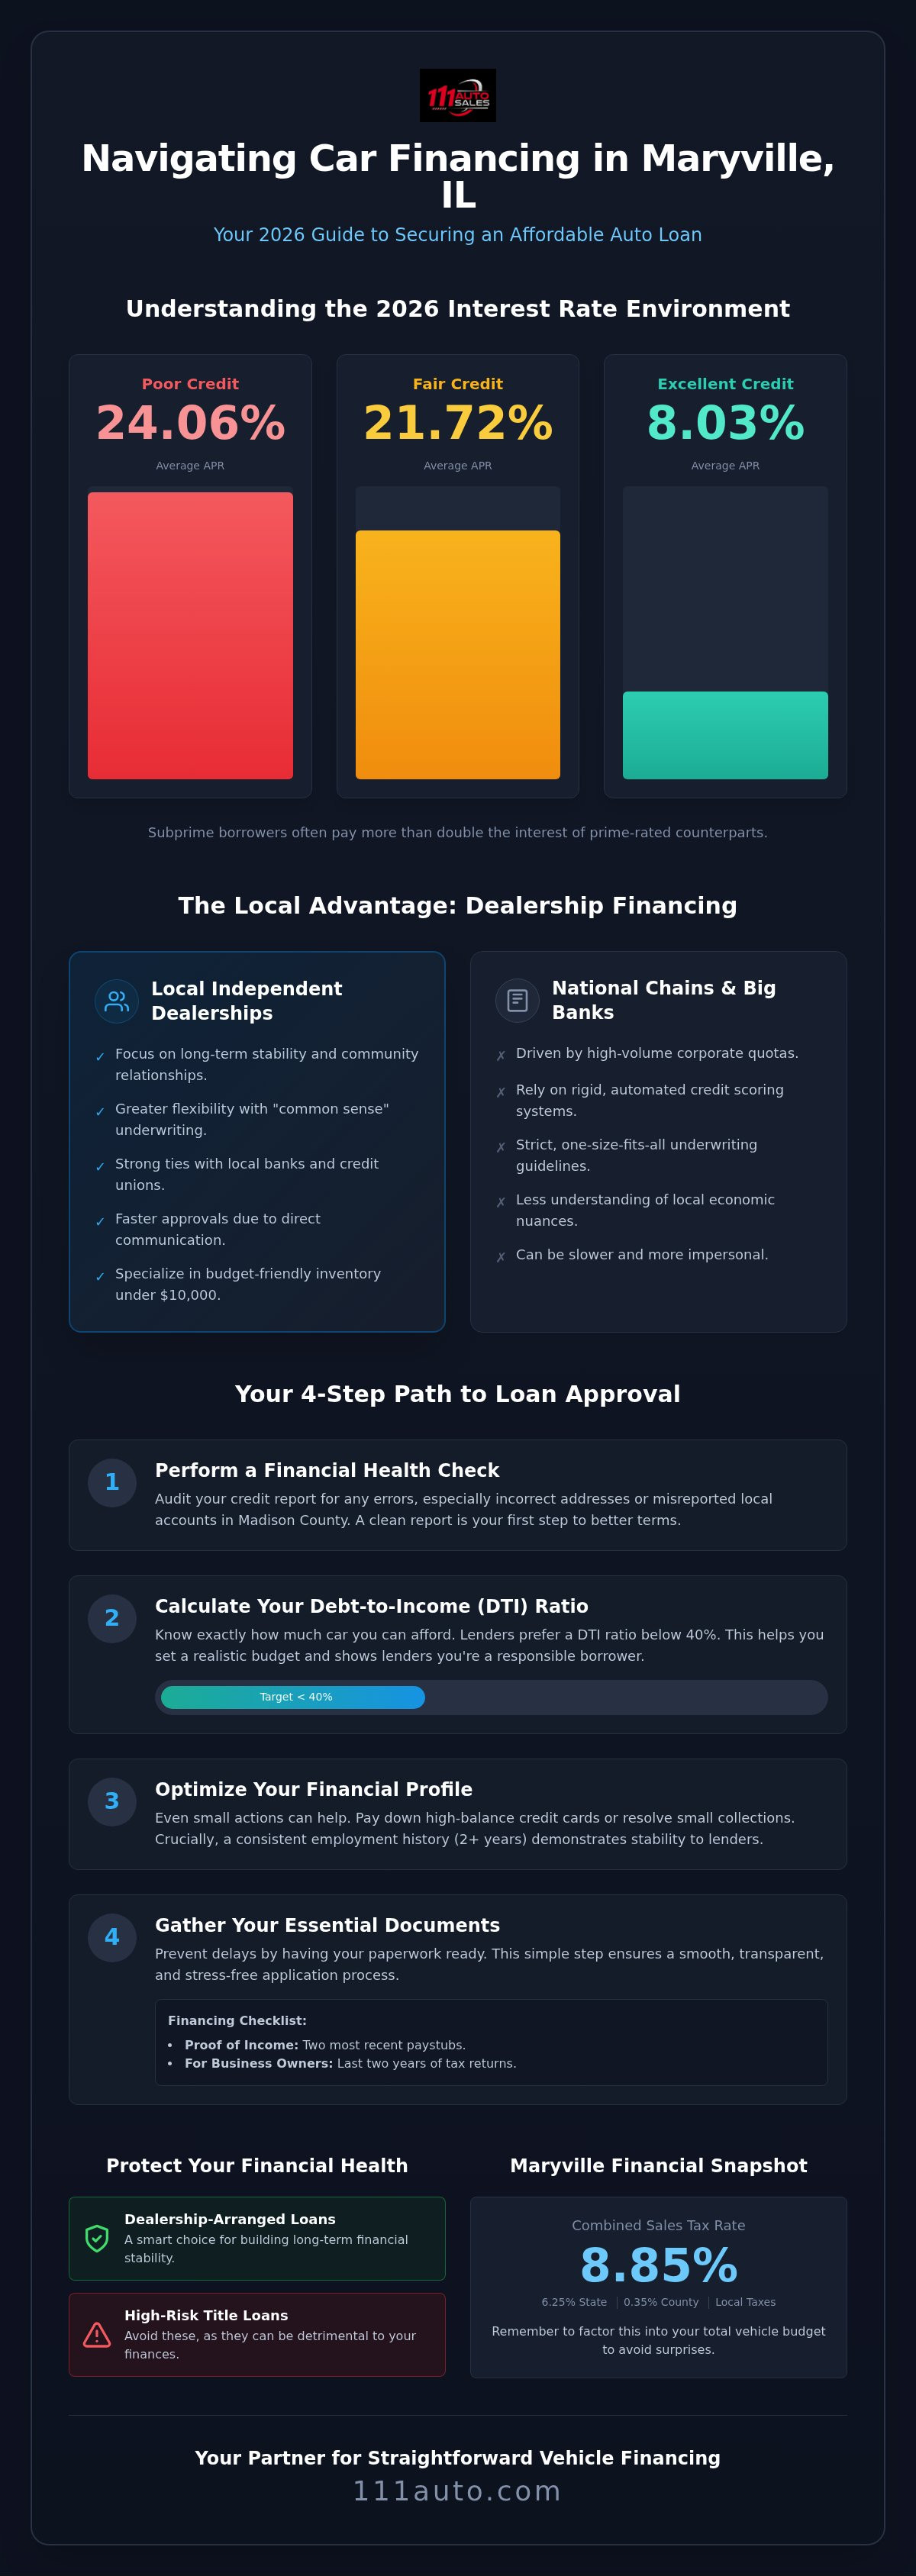
Interest rates for used vehicles remain higher than those for new cars across all credit tiers in 2026. Data from Q2 2026 shows that while a buyer with excellent credit might see an APR of 8.03% on a used vehicle, those with fair credit are facing rates around 21.72%. The age of the vehicle also plays a critical role; older models often carry slightly higher rates due to perceived lender risk. In the current market, the gap between prime and subprime rates is wider than ever, with subprime borrowers often paying more than double the interest of their prime-rated counterparts.
How to Prepare Your Financial Profile for Approval
Securing vehicle financing Maryville IL starts long before you step onto the lot. A structured approach reduces the risk of rejection and ensures you get the most favorable terms available for your situation. Being prepared also helps you avoid the stress of last-minute documentation hurdles during the approval process.
Start by preparing for an auto loan through a thorough audit of your credit report. Check for errors that might be specific to your history in Madison County, such as incorrect address records or misreported local accounts. Next, calculate your true debt-to-income ratio (DTI). Lenders generally prefer a DTI below 40%; knowing this number helps you determine how much of your monthly income can realistically go toward a car payment. When you set your budget, remember that Maryville has a combined sales tax rate of 8.85%. This includes the 6.25% Illinois state tax, the 0.35% Madison County tax, and local special taxes. Factoring these costs in early prevents surprises at the signing table.
Credit Score Optimization for Auto Loans
You don't need a perfect score to get approved, but small changes can have a big impact within 30 days. Paying down high credit card balances or resolving small outstanding collections can provide a quick score boost before you apply. If you have a thin credit file with limited history, don't assume it's an automatic rejection. Local independent dealerships often prioritize consistent employment history over a long credit track record. Showing at least two years of steady work in the Metro East area demonstrates the stability lenders look for when approving vehicle financing Maryville IL.
The Essential Maryville Financing Checklist
Gathering your documents early prevents delays and keeps the process transparent. Most lenders in the Maryville area will require the following items to verify your application:
- Proof of income: Your two most recent paystubs or the last two years of tax returns if you're a local small business owner.
- Proof of residency: A recent utility bill or bank statement showing your Maryville or Metro East address.
- Identification: A valid Illinois driver's license and your current auto insurance information.
Having these items ready allows you to focus on finding the right vehicle at 111 Auto Sales LLC without the stress of missing paperwork. A strong down payment strategy also helps; putting even a small amount down can significantly lower your monthly costs on inventory under $10,000.
Comparing Financing Options: Dealerships vs. Title Loans
When you begin looking for vehicle financing Maryville IL, it's vital to distinguish between purchase financing and title loans. These two products serve entirely different purposes. Purchase financing is a loan used to acquire a vehicle you don't yet own, allowing you to build equity over time. A title loan involves using a car you already own as collateral for a high-interest cash loan. For residents seeking long-term financial stability, purchase financing is the superior choice. It provides a structured path to ownership rather than risking an existing asset for short-term cash flow.
You also have choices within dealership models. Traditional dealer-arranged financing involves the dealer acting as a bridge to local banks and credit unions. In contrast, "Buy Here, Pay Here" options allow the dealership to finance the vehicle directly. This is often a lifeline for those with significant credit hurdles who have been rejected by traditional institutions. Regardless of the loan type, Metro East commuters should consider Gap Insurance. If you drive heavily between Maryville and St. Louis, your vehicle's mileage might cause it to depreciate faster than your loan balance decreases. Gap insurance covers that financial gap if the car is totaled, ensuring you aren't left paying for a vehicle you can no longer drive. According to the FTC guide to vehicle financing, understanding these specific contract terms is the best way to avoid the predatory practices that can occur in the used car market.
The Risks of Title Loans in Maryville
Title loans are notoriously risky and expensive. While lenders often promise you can "keep your car" while borrowing cash, the reality is often a cycle of debt. Title loan APRs can be 10 times more expensive than standard auto loans, sometimes reaching triple digits. If you miss a single payment, the lender can repossess your only means of transportation. At 111 Auto Sales LLC, the focus remains on sustainable purchase loans. These products are designed to help you stay on the road while successfully managing your vehicle financing Maryville IL.
Dealer-Direct Financing Benefits
The primary benefit of dealer-direct financing is the convenience of one-stop shopping. You can select your vehicle, value your trade-in, and secure your loan in a single afternoon. These loans offer customized terms that can be aligned with your specific pay cycle, whether you're paid weekly or bi-monthly. Dealership financing leverages a network of multiple local lenders simultaneously to find the most competitive rate for your specific credit profile. Your vehicle choice also impacts your terms; lenders often view SUVs and trucks differently than sedans due to their historically stronger resale value in the Madison County market.
Step-by-Step Guide to the Application Process
The journey toward securing vehicle financing Maryville IL is more efficient when you follow a structured path. Modern tools allow you to handle much of the groundwork before visiting the dealership. This transparency ensures that when you arrive, you can focus on the quality of the vehicle rather than stressing over the paperwork. A predictable process benefits both the lender and the buyer by setting clear expectations from the start.
Navigating the Online Application
Starting your inquiry online is a smart move. You can use a car loan calculator to estimate your monthly payments based on different down payment amounts. Secure online portals protect your sensitive data while providing the dealership with the necessary information to begin the approval process. It's important to understand the difference between credit inquiries. A 'soft' pull is often used for pre-qualification and doesn't impact your score. A 'hard' pull occurs when you officially apply for the loan, which is a standard part of finalizing your vehicle financing Maryville IL.
Once you've narrowed down your budget, the next phase is vehicle selection. A test drive is essential to ensure the pre-owned truck, SUV, or sedan meets your expectations. During this stage, you'll work with a consultant to match your pre-approved terms to the specific car you've chosen. This phase is where the theoretical numbers from your application become a concrete reality. It's the best time to ask questions about the vehicle's history and performance.
Closing the Deal in Maryville
Before you sign the final contract, you'll receive a Truth in Lending Act (TILA) disclosure. This document is a federal requirement that clearly outlines the annual percentage rate (APR), the finance charge, the amount financed, and the total of payments. Reviewing this fine print ensures you understand the total cost of ownership over the life of the loan. You can also choose to integrate a used truck warranty Pontoon Beach into your monthly payment. This adds an extra layer of protection for your investment, especially for vehicles priced under $10,000.
The final steps involve accounting for Illinois-specific fees. Your contract will include documentation fees, title transfers, and registration costs for the Maryville area. Once the paperwork is signed and the insurance is verified, you'll take delivery of your vehicle. The process is designed to be logical and predictable, removing the uncertainty often associated with auto lending. If you're ready to start, apply for financing online today to see your options in minutes.
Why 111 Auto Sales LLC is Maryville's Choice for Financing
Choosing the right partner for vehicle financing Maryville IL involves more than just finding a low interest rate. It's about working with a dealership that understands the specific needs of the Metro East community. 111 Auto Sales LLC has built a reputation for providing stable, predictable financing solutions since its inception. As a locally owned independent dealership, our focus remains on personal service rather than meeting corporate sales quotas. This approach allows for a level of flexibility that larger franchises simply cannot match, especially when it comes to matching a monthly payment to a realistic household budget.
One of the primary reasons residents choose 111 Auto Sales LLC is the access to a specialized inventory. Finding used trucks under 10000 Pontoon Beach can be difficult at traditional dealerships that prioritize newer, high-margin vehicles. We recognize that Maryville drivers need reliable transportation that doesn't lead to long-term financial strain. Our team audits every application with a focus on long-term success, ensuring that the terms of your loan are as durable as the vehicle you drive home. We take pride in being a one-stop shop where inventory, financing, and protection come together seamlessly.
Financing for Every Budget
We specialize in helping buyers find reliable used SUVs under 10000 Pontoon Beach. This price point is ideal for first-time buyers or families looking for a secondary vehicle without taking on massive debt. If you've faced credit challenges in the past, our experience with local lending trends allows us to find solutions that national banks often overlook. We maintain a no-pressure sales environment where transparency is the standard. You'll receive clear answers about your interest rate, total cost, and payment schedule before you make any commitment to vehicle financing Maryville IL.
Protecting Your Investment
Reliability is a core pillar of our business. While we focus on budget-friendly inventory, we also prioritize long-term protection. We recommend extended warranties for all our pre-owned vehicles to safeguard against unexpected repair costs. A significant benefit of our financing process is the ability to roll the cost of these protection plans directly into your monthly payment. This ensures you have comprehensive coverage without a large upfront expense. It's a professional, straightforward way to manage the risks of used car ownership while keeping your monthly costs predictable. Contact us today to start your application and discover how simple local financing can be.
Take the Next Step Toward Your New Vehicle
Securing reliable vehicle financing Maryville IL doesn't have to be a source of stress. By auditing your credit profile and choosing purchase financing over high-risk title loans, you protect your long-term financial health. We've explored how a transparent, step-by-step application process removes the guesswork from buying a pre-owned truck, SUV, or sedan. Preparation and local expertise are your best tools for finding a monthly payment that fits your budget perfectly.
111 Auto Sales remains dedicated to the Metro East community with an A+ commitment to every customer. We specialize in budget-friendly inventory under $10,000 and offer extended warranty options on all models to ensure your investment is protected. Our team is ready to help you navigate the 2026 lending market with honesty and professional guidance. You can Apply for Vehicle Financing Near Maryville Today to see how our personalized service makes the difference. We look forward to helping you drive home in a vehicle you love with terms that make sense for your future.
Frequently Asked Questions
Can I get vehicle financing in Maryville with a 500 credit score?
Yes, you can secure vehicle financing Maryville IL even with a credit score around 500. While national banks might decline these applications, local independent dealerships prioritize your current stability and employment history. They use common sense underwriting to look beyond the number on your credit report. Providing a larger down payment or showing steady income from a Madison County employer can significantly improve your chances of approval for a reliable pre-owned vehicle.
What is the typical down payment required for a used car in Maryville?
A typical down payment for a used car in the Maryville area generally ranges from 10% to 20% of the vehicle's purchase price. However, for inventory priced under $10,000, some lenders may accept a flat dollar amount instead of a percentage. Putting more money down reduces your monthly payments and can help you secure a lower interest rate. We recommend discussing your specific budget with a finance specialist to find a strategy that fits your cash flow.
How long does the auto loan approval process take at 111 Auto Sales?
The auto loan approval process is designed for speed and efficiency, often taking just a few hours or even less. If you start by using our secure online application tools, we can begin the pre-approval process before you even arrive at the lot. Once you select your vehicle and provide the necessary documentation, our local banking ties allow us to finalize the contract quickly. Most customers can complete the entire process and take delivery in a single afternoon.
Is it better to get a loan from my bank or the dealership?
Both options have distinct advantages depending on your credit profile. A bank loan provides a pre-set budget, but dealership financing offers the convenience of one-stop shopping and access to multiple lenders at once. This competition among lenders often results in more flexible terms for those with unique credit situations. Dealers also specialize in used car values, which can simplify the approval process for budget-friendly inventory that traditional banks might find difficult to collateralize.
Can I finance a vehicle that costs less than $10,000?
Yes, you can definitely finance vehicles priced under $10,000. While some large lenders have minimum loan amounts that exclude budget-friendly cars, we specialize in this segment of the market. Financing a lower-cost vehicle is an excellent way for first-time buyers to build credit without the burden of a massive monthly payment. Our team works with specialized lenders who understand the value and reliability of our pre-owned trucks, SUVs, and sedans in this price range.
What documents do I need to bring to the dealership for financing?
To ensure a smooth approval for vehicle financing Maryville IL, you should bring several key documents. These include your valid Illinois driver's license, your two most recent paystubs, and a utility bill to prove your residency in the Metro East area. You will also need to provide current auto insurance information. Having these items ready allows our finance team to verify your application details immediately and prevents any delays in taking delivery of your chosen vehicle.
Do you offer financing for trucks and SUVs specifically?
Yes, we provide comprehensive financing options for our entire inventory, including pre-owned trucks and SUVs. Lenders in the Madison County area often view these vehicles favorably due to their strong resale value and durability. Whether you need a truck for work or a spacious SUV for your family, our finance specialists can match you with a loan product that accounts for the specific utility and value of these larger vehicles while keeping your payments affordable.
Can I include an extended warranty in my monthly car payment?
Yes, we highly recommend rolling the cost of an extended warranty directly into your monthly car payment. This allows you to protect your investment without needing a large upfront cash payment for coverage. Including the warranty in your financing ensures that you have predictable monthly costs that cover both your loan and potential mechanical repairs. It's a professional way to manage the risks of used car ownership while maintaining the long-term stability of your household budget.


