
You've likely spent weeks visiting lots in Granite City or Collinsville, only to face the same frustrating rejection because of a past financial mistake. It's exhausting to need a reliable vehicle for work while fearing that your credit score makes you unbankable. This is why finding USED CAR ST LOUIS BAD CREDIT FINANCING SUBPRIME AUTOLOANS GUARANTEED FINANCING that actually works for your budget is so critical in 2026. You deserve a transparent process that prioritizes your need for a safe SUV or truck without the high-interest anxiety common in today's market.
We understand that a credit score is just a number and doesn't reflect your current ability to manage a monthly payment. You probably feel that guaranteed financing sounds like a hollow promise, especially with 2026 subprime interest rates often exceeding 19 percent. This article will show you how to secure a reliable used car under $10,000 while building a clear path to credit recovery. We'll explore the differences between subprime loans and buy-here-pay-here options, explain how regional interest rate caps protect your wallet, and help you find a vehicle backed by a protective warranty.
Key Takeaways
- Learn how to navigate USED CAR ST LOUIS BAD CREDIT FINANCING SUBPRIME AUTOLOANS GUARANTEED FINANCING by understanding the specific lending requirements of the Metro East market in 2026.
- Discover why choosing a pre-owned vehicle priced under $10,000 is the most effective way to keep your monthly payments manageable while dealing with higher subprime interest rates.
- Understand the critical differences between subprime auto loans and "Buy Here Pay Here" models to ensure your payments actually help rebuild your credit score.
- Follow a streamlined four-step approval process that focuses on your current income and residency rather than just your past credit history.
- Find out how an extended warranty provides a vital safety net for your investment, ensuring your used SUV or truck remains reliable for years to come.
Understanding Bad Credit Auto Financing in the St. Louis Metro East
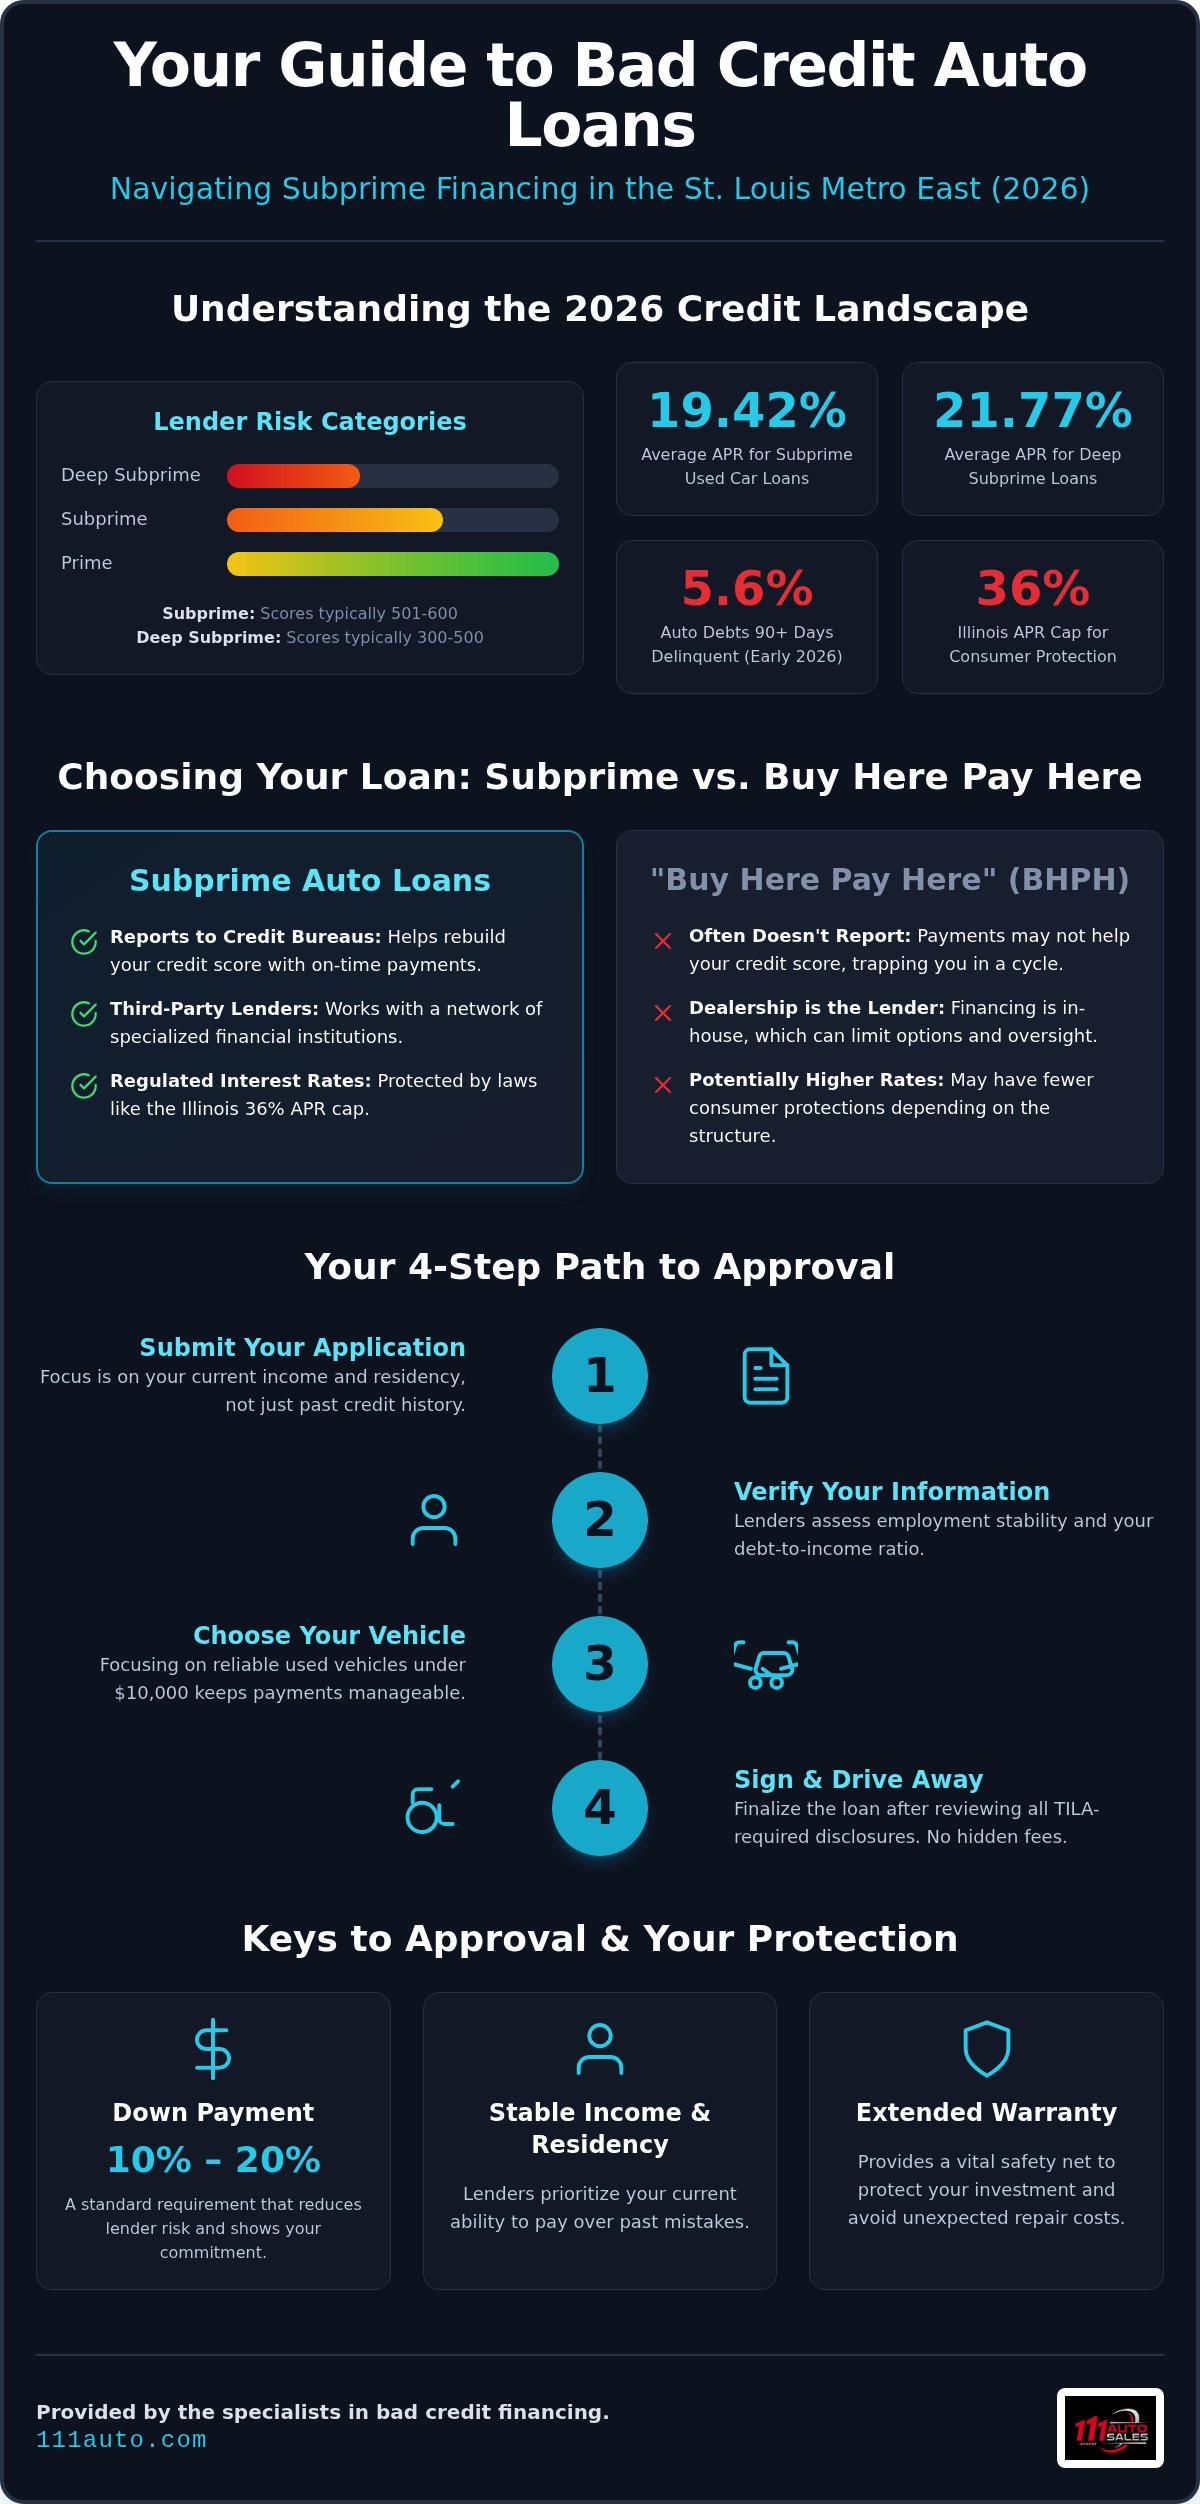
In 2026, bad credit isn't a single label but a spectrum lenders use to assess risk. Most automotive financiers categorize scores between 501 and 600 as subprime, while scores from 300 to 500 fall into the deep subprime tier. Traditional banks in Pontoon Beach and the surrounding Metro East have significantly tightened their underwriting standards this year. This shift follows data showing that 5.6 percent of all outstanding auto debt reached a 90-day delinquency status in early 2026. Consequently, many buyers find that their local bank no longer offers the flexibility needed for their situation.
Securing a USED CAR ST LOUIS BAD CREDIT FINANCING SUBPRIME AUTOLOANS GUARANTEED FINANCING package requires understanding these market shifts. While traditional institutions say no, independent dealerships like 111 Auto Sales LLC specialize in finding paths to approval by focusing on inventory priced under $10,000. It's vital to distinguish between legitimate subprime options and predatory lending. In Illinois, for example, the Predatory Loan Prevention Act caps interest rates at a 36 percent APR for non-depository lenders. This provides a legal safeguard that protects your wallet from the unregulated rates sometimes found in other markets.
What is a Subprime Auto Loan?
Subprime lending involves providing credit to borrowers who don't meet the criteria for prime interest rates due to past financial setbacks. These loans differ from standard financing because they account for a higher probability of default by using adjusted interest rates and specific down payment requirements. During the first quarter of 2026, the average APR for a subprime used car loan was 19.42 percent, while deep subprime loans averaged 21.77 percent. A subprime auto loan serves as a technical tool for credit recovery by reporting your consistent payment history to major credit bureaus.
Why St. Louis Buyers Face Credit Challenges
The local economy in the Metro East presents unique challenges for many households. Medical debt, past bankruptcies, or significant student loans often result in thin credit files that traditional algorithms reject instantly. Lenders in Granite City and Collinsville look closely at these factors when reviewing applications. The emotional weight of a loan rejection can be heavy, but it's often a reflection of a lender's rigid policy rather than your current financial stability. Moving past a rejection means finding a partner that looks at your current income and residency rather than just a historical score.
The Truth About Guaranteed Financing and Subprime Auto Loans
Many St. Louis residents see "guaranteed financing" signs and feel a mix of hope and skepticism. In the automotive industry, this term doesn't mean every applicant receives a loan regardless of circumstances. Instead, it signals that the dealership works with specialized lenders who prioritize your ability to pay over your past credit score. Securing USED CAR ST LOUIS BAD CREDIT FINANCING SUBPRIME AUTOLOANS GUARANTEED FINANCING often depends on meeting a minimum income threshold and providing a down payment that offsets the lender's risk. In 2026, a down payment of 10 to 20 percent is standard for subprime approvals, as it demonstrates a commitment to the loan and reduces the overall finance charge.
Transparency is your strongest defense against hidden fees. Lenders are required by the Federal Truth in Lending Act (TILA) to disclose all finance charges and the total cost of the loan before you sign. The Consumer Financial Protection Bureau emphasizes that understanding these terms is essential for long-term financial health. A reputable dealer in Pontoon Beach will walk you through every line of the contract to ensure you understand your obligations. This clarity is vital because subprime delinquency rates reached 5.5 percent in May 2026, highlighting the need for loans that are truly affordable for your specific budget.
How Dealerships Secure Your Approval
Independent dealerships maintain relationships with a broad network of subprime lenders. These partners look beyond FICO scores to verify your employment stability and local residency. When you apply, the focus shifts to your debt-to-income ratio. If your current earnings can comfortably support a monthly payment on a vehicle under $10,000, your chances of approval increase significantly. Choosing a dealer with established lender ties is the most effective way to manage this process. You can start by viewing our inventory of pre-owned trucks and SUVs to see which options fit your current financial situation.
Guaranteed vs. Traditional Financing
Traditional financing through a bank can take days and requires a pristine credit history. In contrast, guaranteed or subprime options offer a fast track for those who need a vehicle immediately for their daily commute. The documentation requirements are different; you'll need recent pay stubs and utility bills rather than just a high credit score. This streamlined approach allows many Metro East drivers to secure a safe vehicle in a single afternoon. For more details on these programs, read our guide to Easy Used Car Financing Options in Pontoon Beach. This comparison shows that subprime loans are designed for speed and accessibility for the working families of Granite City and Collinsville.
Subprime Loans vs. Buy Here Pay Here: Making the Right Choice
In Granite City and the wider Metro East, buyers often choose between Buy Here Pay Here (BHPH) lots and subprime financing. BHPH dealers act as their own bank. They lend money directly to you, often without a traditional credit check. While this sounds convenient, it frequently leads to a "churn" cycle. This happens when a dealer sells a low-quality vehicle, repossesses it after a single missed payment, and resells it to the next buyer. It's a business model built on turnover rather than your long-term success.
In 2026, subprime loans average between 19.42 and 21.77 percent APR. BHPH rates can be significantly higher, though Illinois law now caps these at a 36 percent APR. Choosing USED CAR ST LOUIS BAD CREDIT FINANCING SUBPRIME AUTOLOANS GUARANTEED FINANCING through a subprime lender is generally a safer financial move than relying on a lot-funded contract. Subprime lenders are third-party institutions that have a vested interest in seeing you complete the loan term.
Which Option Rebuilds Your Credit?
Major credit bureaus like Equifax, Experian, and TransUnion rely on data from lenders to build your score. Most BHPH lots do not report your on-time payments to these bureaus. This means you could pay off a car over three years and still have the same low credit score you started with. Subprime lenders are different because they are structured to report your activity monthly. Consistently making your subprime auto loan payments on time creates a documented history of reliability that directly raises your FICO score over time.
The Long-Term Cost of Financing
Calculating the total cost of ownership over a 48-month term reveals the true impact of your choice. A BHPH loan often involves high weekly payments and a vehicle that may not last the length of the contract. It's a safer strategy to secure a subprime loan on a reliable used truck under 10000. This approach keeps your principal balance low and your monthly payments manageable. By focusing on affordable inventory, you avoid the cycle of debt that occurs when interest charges outpace the value of the vehicle. Lower principal amounts also mean you pay less in total interest over the life of the loan.
How to Secure Your Subprime Auto Loan Approval in 4 Steps
Securing USED CAR ST LOUIS BAD CREDIT FINANCING SUBPRIME AUTOLOANS GUARANTEED FINANCING is a methodical process. While traditional banks rely heavily on a digital score, subprime lenders focus on your current ability to pay. Following these four steps ensures you walk into the dealership with the highest probability of driving home the same day.
- Step 1: Gather your proof of income. Lenders typically require pay stubs from the last 30 days. If you receive Social Security or disability benefits, bring your award letter.
- Step 2: Verify your residence. Stability is a key metric for Metro East lenders. A recent utility bill, such as electric or water, confirms you live within the service area of St. Louis, Granite City, or Collinsville.
- Step 3: Budget for affordability. Focus your search on inventory priced under $10,000. This price point keeps the principal loan amount low, making it easier for lenders to approve the contract.
- Step 4: Maintain full transparency. Disclose past repossessions or bankruptcies early. Lenders will see these on your report; being upfront allows the finance manager to position your application correctly from the start.
The Metro East Buyer's Checklist
Preparation is the difference between a quick approval and a wasted trip. You will need a valid driver's license, a list of personal references, and proof of active car insurance. Self-employed individuals or 1099 contractors should provide the last three months of bank statements to verify consistent deposits. This documentation helps lenders understand your cash flow when a traditional W-2 is not available. Having these items ready allows you to focus on choosing the right vehicle, such as the ones found in our Durable Used Family SUVs in Pontoon Beach buying guide.
Maximizing Your Approval Odds
A modest down payment is the most effective way to lower your interest rate. By putting money down, you reduce the lender's risk and the total amount of interest you'll pay over the life of the loan. If you have an existing vehicle, a trade-in can serve as your down payment, even if it has high mileage. Every dollar of equity you bring to the table makes your subprime loan structure more attractive to secondary lenders. Honesty about your credit history prevents delays during the verification phase. When you are ready to start, apply for financing online to see which pre-owned trucks or sedans fit your budget.
Why 111 Auto Sales LLC is the Choice for Bad Credit Financing in St. Louis
Finding a dealership that understands the local economy is essential for Metro East drivers. Many large franchise dealers in the area push inventory priced at $20,000 or higher, which often leads to payment shock for those with challenging credit. At 111 Auto Sales LLC, we take a different approach by specializing in high-quality pre-owned SUVs, trucks, and sedans priced under $10,000. When you are searching for USED CAR ST LOUIS BAD CREDIT FINANCING SUBPRIME AUTOLOANS GUARANTEED FINANCING, our focus on affordability ensures your monthly payments remain manageable. Our Pontoon Beach location is specifically positioned to serve neighbors in Granite City and Collinsville with a straightforward buying process.
Our independent status is a significant benefit for our customers. We aren't tied to a single corporate lender's rigid rules. Instead, we maintain the flexibility to work with various subprime partners to find the specific loan structure that fits your current income. This independence allows us to offer solutions that many larger lots simply cannot match. We prioritize stability and transparency, ensuring you know exactly what your obligations are before you drive off the lot. Our goal is to provide a professional environment where your past credit history doesn't prevent you from securing reliable transportation for work and family life.
Reliable Inventory You Can Trust
We select our inventory based on long-term durability rather than just aesthetic appeal. For working families, a vehicle is a tool for survival. This is why we emphasize finding a used SUV under 10000 that has been vetted for mechanical soundness. By focusing on this price bracket, we help you keep your principal loan balance low. A lower principal means you pay less in total interest over the life of the loan, making it easier to stay current on your payments and successfully rebuild your credit score. Our inventory of trucks and sedans is constantly updated to provide the best possible options for the Metro East market.
Protecting Your Purchase with a Warranty
A sudden mechanical failure is one of the biggest risks for anyone managing a subprime budget. We believe that a protective safety net is vital for every purchase. We offer extended warranty options for all our pre-owned vehicles to help you avoid the stress of unexpected repair costs. This coverage is especially important for those with limited emergency savings who cannot afford a major bill alongside their car payment. You can read more about how these protections work in our guide to a Used Truck Warranty Pontoon Beach. The mission at 111 Auto Sales LLC is to get St. Louis residents driving again with a safe, reliable vehicle and a clear path toward a better financial future.
Drive Your Success with Reliable Metro East Financing
Securing a vehicle when your credit is less than perfect doesn't have to be a source of anxiety. The key to long-term success lies in selecting affordable inventory and avoiding the high-turnover cycles of traditional buy-here-pay-here lots. By focusing on vehicles priced under $10,000, you ensure that your monthly payments remain manageable even with 2026 interest rates. This strategic approach protects your budget while providing a documented path to rebuild your credit score through consistent, on-time payments.
Finding USED CAR ST LOUIS BAD CREDIT FINANCING SUBPRIME AUTOLOANS GUARANTEED FINANCING is finally possible through a partner that understands the specific needs of the St. Louis Metro East area. We remain committed to offering specialized inventory and extended warranties that safeguard your automotive investment. Whether you are in Granite City, Collinsville, or Pontoon Beach, reliable transportation is within your reach. Take the first step toward a safer SUV or truck by starting your application now.
Get Pre-Approved for Your Next Vehicle at 111 Auto Sales Today!
You have the power to move past previous financial challenges and get back on the road with confidence. We look forward to helping you secure the keys to your next reliable vehicle.
Frequently Asked Questions
Can I get a car loan in St. Louis if I have a recent bankruptcy?
Yes, you can secure financing even with a recent bankruptcy on your record. While traditional banks often reject these applications immediately, subprime lenders in the St. Louis Metro East look at your current ability to pay. Most lenders require that your bankruptcy is discharged or that you have court permission if it is an active Chapter 13. Providing proof of steady employment and residency in Granite City or Collinsville helps demonstrate your current financial stability.
What is the minimum credit score required for a subprime auto loan?
There is no absolute minimum credit score for a subprime auto loan. In 2026, lenders typically categorize scores between 300 and 500 as deep subprime. Instead of focusing solely on a number, independent dealerships in Pontoon Beach prioritize your debt-to-income ratio and employment history. If you can prove a consistent monthly income that supports a payment, your chances of approval remain high regardless of where your score currently sits on the spectrum.
How much down payment do I need for guaranteed financing?
A down payment of 10 to 20 percent is generally required to secure USED CAR ST LOUIS BAD CREDIT FINANCING SUBPRIME AUTOLOANS GUARANTEED FINANCING. This payment reduces the lender's risk and shows your commitment to the loan. While some marketing claims suggest zero down, a modest payment significantly improves your approval odds and lowers your total interest costs. You can use a trade-in vehicle to cover part or all of this requirement at our Pontoon Beach location.
Do you offer financing for used trucks under $10,000?
Yes, we specialize in financing pre-owned trucks, SUVs, and sedans priced under $10,000. These vehicles are ideal for subprime budgets because the lower principal amount makes the loan more affordable for both the lender and the buyer. Our inventory serves residents throughout St. Louis and the Metro East who need reliable work vehicles without the burden of a massive debt. Every truck in this price range is selected for its long-term durability.
Will my on-time payments be reported to the credit bureaus?
Yes, your on-time payments are reported to major credit bureaus like Equifax and Experian. This is a critical advantage of subprime financing over traditional buy-here-pay-here lots. By making your payments on schedule, you build a positive credit history that can eventually help you qualify for lower interest rates in the future. It's a proven method for rebuilding your financial standing while maintaining the reliable transportation you need for your daily commute in the Metro East.
Can I get an auto loan if I am a first-time buyer with no credit?
First-time buyers with no credit history, often called "thin files," are excellent candidates for subprime loans. Lenders view a lack of credit differently than a history of defaults. By providing proof of residency in Maryville or Troy and showing consistent income, you can establish your first line of credit. This process allows you to drive a safe used vehicle while starting your credit journey with a manageable loan on a car priced under $10,000.
What happens if I have a trade-in but still owe money on it?
If you have a trade-in with an existing balance, we can often work to include that equity into your new loan structure. This depends on the value of the vehicle and the requirements of the subprime lender. While owing more than the car is worth is a challenge, our finance team in Pontoon Beach has experience managing these situations. We help you transition into a more affordable used vehicle that better fits your current financial situation in the St. Louis area.
Are extended warranties available for cars bought with subprime financing?
Extended warranties are available for all pre-owned vehicles, including those purchased through USED CAR ST LOUIS BAD CREDIT FINANCING SUBPRIME AUTOLOANS GUARANTEED FINANCING programs. We believe these warranties are essential for protecting your investment against unexpected mechanical issues. Having this coverage provides peace of mind for buyers in Granite City and Collinsville who may not have a large emergency fund. It ensures your vehicle stays on the road while you focus on making your monthly payments.


