
Could a lower monthly payment end up costing more over the life of a used-car loan? For shoppers focused on understanding used car financing terms Cahokia IL, the key is to look beyond the payment and read the full offer. A longer loan term may lower what’s due each month, but it means you owe for longer and may increase the total finance charge.
It’s understandable to compare offers by the payment that fits your monthly budget. But APR, loan term, down payment, amount financed, fees, and total of payments all affect what a deal costs. This guide explains these terms and shows how to compare dealer-arranged financing with an offer from a bank or credit union.
You’ll also find questions to ask before signing and a checklist of information to bring when discussing financing with a local dealership. If you’re considering an optional warranty, review its documents separately from the loan so you can see each commitment clearly. The goal is to understand the terms before you agree.
Key Takeaways
- Understanding used car financing terms Cahokia IL starts with knowing how APR, amount financed, and loan term shape the agreement.
- Compare written offers using the same vehicle price and transaction details, then review the payment alongside fees and total payments.
- Check that the vehicle and buyer details in the contract match your understanding before reviewing the loan terms.
- Review optional items, including warranty options, separately so you can identify what’s included in the financing agreement.
- Ask a local dealership to explain any difference between the written offer and contract before signing.
Used Car Financing in Cahokia, IL: Agreement Details
Choosing a vehicle can feel straightforward until unfamiliar financing terms make the paperwork harder to assess. Understanding used car financing terms Cahokia IL starts with a simple definition: financing means borrowing money to pay for a vehicle and repaying it under agreed terms. The agreement states the amount financed, payment schedule, interest, and other applicable terms.
Financing can be arranged in different ways. A dealership may help arrange a loan through a lender, or a buyer may seek financing directly from a bank or credit union. The overview of Car finance explains these broad approaches and distinguishes financing from leasing. Whichever route you consider, terms depend on the lender, applicant, and transaction. An estimate or application doesn’t guarantee approval or final terms.
Who are the parties to a used-car loan?
The buyer purchases the vehicle and agrees to repay the loan. A selling dealership sells the vehicle and may help arrange financing, but that doesn’t automatically make it the lender. The lender is the creditor providing the loan; a separate loan servicer may handle payments for the lender. A co-buyer is another person named on the agreement who shares responsibility for the loan. Check the paperwork to identify the lender and any co-buyer. If it isn’t clear who receives your payments, ask before signing.
What should Cahokia-area shoppers expect to review?
Review the written offer, any disclosures provided with it, and the final contract. A verbal estimate can start the conversation, but the documents set out the proposed terms and obligations you’d accept by signing. Confirm the vehicle and buyer details first, then check that the final terms match what you discussed.
Compare written offers before committing, whether you’re shopping locally or considering financing from another lender. Look at all the terms, not just an estimated payment. If a figure or condition changes between the offer and contract, ask for an explanation and updated paperwork before signing. This keeps your decision grounded in documents you can review.
APR, Amount Financed, and Loan Term: Used-Car Financing Terms Explained
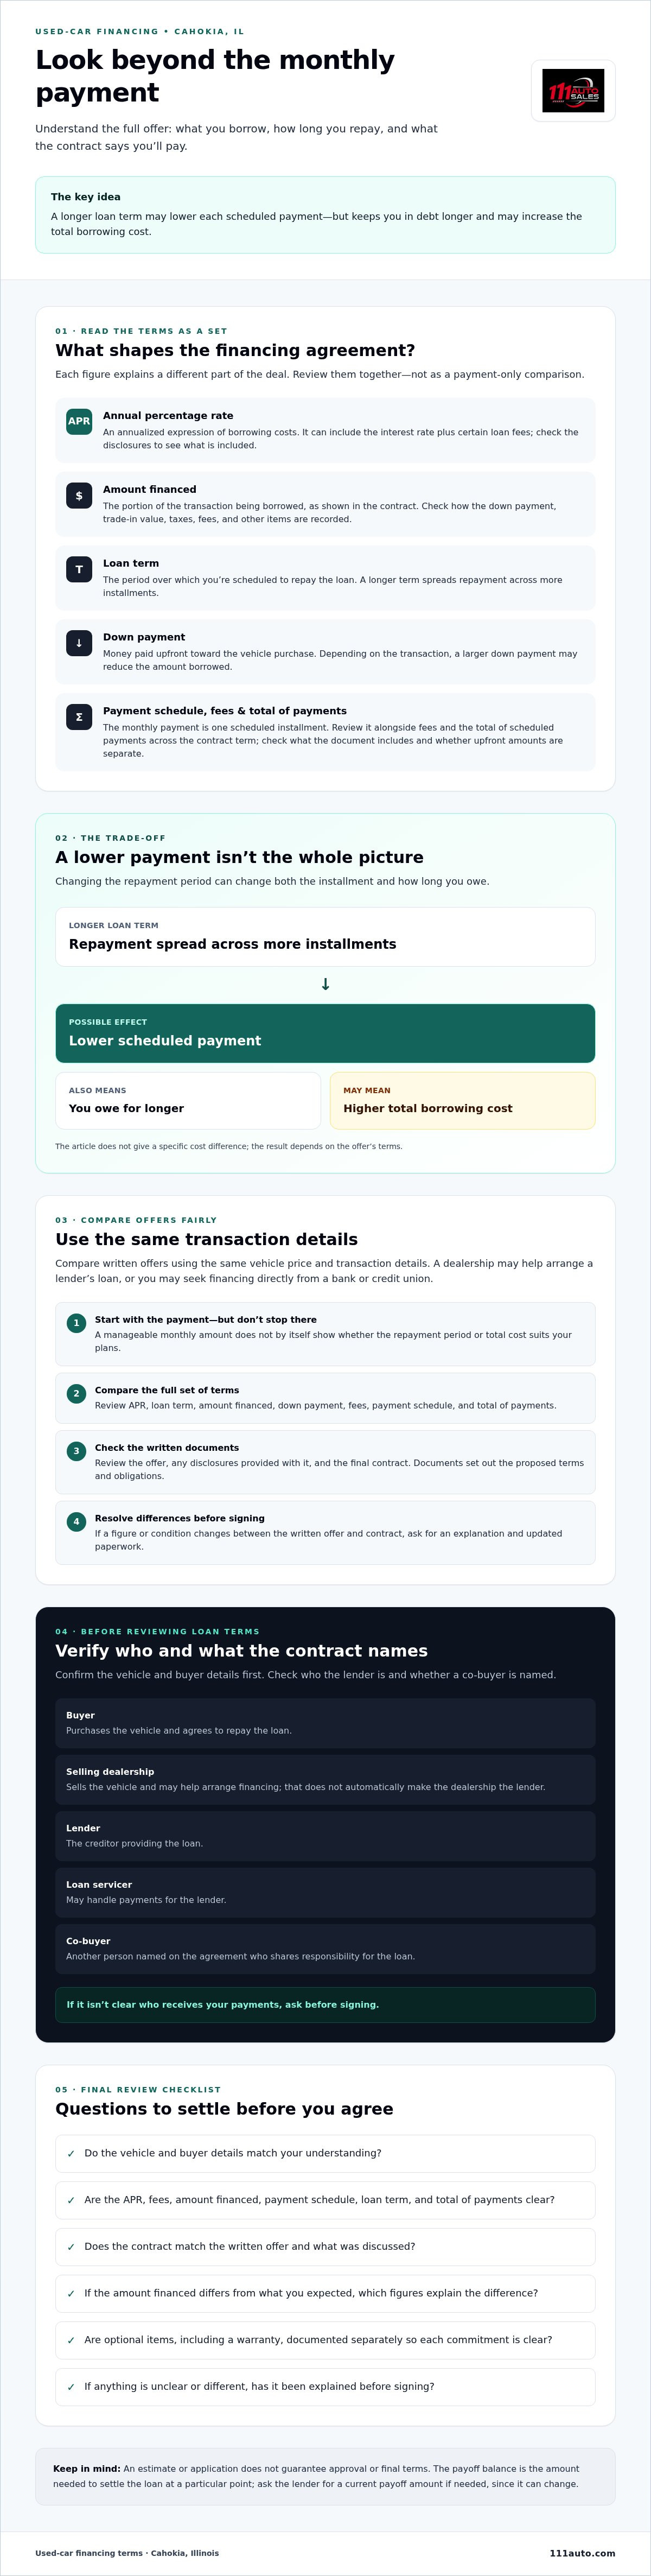
These figures work together, so review them as a set rather than treating any one as the full cost of borrowing. The annual percentage rate (APR) expresses borrowing costs as an annualized percentage. Unlike a simple interest rate, APR can include the interest rate plus certain loan fees. The costs included depend on the agreement, so check the disclosures to see how APR relates to the interest rate and listed charges.
The amount financed is the portion of the transaction being borrowed, as shown in the contract. The loan term is the period over which you’re scheduled to repay it. A longer term spreads repayment across more installments, which may reduce each scheduled payment but keeps you in debt longer and can increase the total borrowing cost. Use the Consumer Financial Protection Bureau’s auto loan resources to explore loan terms and compare offers. When understanding used car financing terms Cahokia IL, read APR, fees, payment schedule, and total payments together before deciding what fits your budget.
How are down payment and amount financed different?
A down payment is money you pay upfront toward the vehicle purchase. Depending on the transaction, a larger down payment may reduce the amount you need to borrow. Check how the contract records your down payment, any trade-in value, taxes, fees, and other items. If the amount financed differs from what you expected, ask which figures explain the difference.
What do payment, total of payments, and payoff balance mean?
Your monthly payment is the scheduled installment, not a complete measure of affordability. A payment may look manageable while the full repayment period or total cost doesn’t suit your plans. The total of payments generally refers to the scheduled installments across the contract term. Confirm what the document includes and whether upfront amounts are listed separately.
The payoff balance is the amount needed to settle the loan at a particular point. It isn’t necessarily the original amount borrowed: payments, interest accrual, and the timing of a payoff request can affect the current figure. Ask the lender for a current payoff amount if you need one, since it can change. If you’re reviewing vehicle financing options, you can discuss financing options with 111 Auto Sales and ask how the figures in a written offer are presented.
How to Compare Used-Car Financing Offers Beyond the Monthly Payment
Start by matching the assumptions behind each offer. Ask each lender to quote financing for the same vehicle and transaction details, including vehicle price, down payment, trade-in value, taxes, fees, and optional products. Otherwise, a lower payment could reflect a different loan amount or longer repayment period rather than a better offer. For understanding used car financing terms Cahokia IL, put written figures side by side.
Use a worksheet and fill it in from each written offer. If a figure isn’t provided, ask for it instead of estimating.
| Compare | Offer A | Offer B |
|---|---|---|
| APR | ||
| Amount financed | ||
| Loan term | ||
| Scheduled payment | ||
| Fees and optional products included | ||
| Total of payments |
A longer term can reduce the scheduled payment by spreading repayment over more time, but it also extends how long you owe. Overall cost depends on APR, amount financed, fees, and other contract details, so a lower payment doesn’t necessarily mean a lower total cost. The final terms are those in the lender’s offer and the agreement you sign, not figures in an illustrative estimate.
Dealer-arranged financing or an outside lender?
With dealer-arranged financing, the dealership helps connect the purchase with a lender. With outside financing, you seek an offer directly from a bank, credit union, or another lender. Either route may be worth comparing, but available terms depend on the lender and your application. Request written offers based on matching vehicle and transaction details. If you’re considering a sedan, see this guide to used sedan financing in Pontoon Beach for related context.
Which questions help reveal the full borrowing commitment?
Before choosing an offer, ask these questions and note the answers:
- Who is the lender, and is this offer final or estimated?
- What does the stated APR include, and how does it differ from the interest rate?
- Which fees or optional products are included in the amount financed?
- What is the total of payments over the scheduled term?
- Can you provide a written explanation of any term I don’t understand?
The Federal Trade Commission’s Buying a Used Car guide offers additional information for shoppers purchasing from a dealer. Keep the offers together, compare the figures, and ask about discrepancies before signing.
Reviewing a Used-Car Financing Offer: A Practical Checklist
Before signing, review the paperwork in a consistent order. This can help you catch mismatched details and separate the loan from optional products. For shoppers understanding used car financing terms Cahokia IL, checking the contract against the written offer is more useful than relying on a payment estimate alone.
- Confirm the vehicle and buyer details. Check that the vehicle description and the names of everyone on the agreement are correct.
- Review the loan terms. Verify APR, amount financed, payment schedule, loan term, fees, and total of payments against the written offer.
- Review optional items separately. Ask whether each product is optional, whether its cost is included in the amount financed, and where its terms are documented.
- Resolve questions before signing. Ask about any difference between the written offer and contract, and request copies of the documents to review.
Take the time you need to read the documents. If a figure or term has changed, ask what explains the difference and request updated paperwork if needed. Don’t rely on a verbal explanation when the written documents don’t match. Make sure you understand the agreement before deciding whether to proceed.
What documents and details should you have ready?
Bring identification and any application information the lender requests. Requirements can vary, so check with the dealership before your visit rather than assuming which documents you’ll need. If you have an outside pre-approval and want to compare it, bring the written terms. Set a budget that accounts for the overall cost of owning the vehicle, including insurance, fuel, and maintenance, not only the loan payment.
How should you evaluate optional products and contract details?
Ask whether an optional product is included in the offer, what its written terms say, and how its cost is treated if financed. Don’t assume a warranty is included or that specific coverage, cancellation rules, or lender conditions apply. Review the product documents for those details and compare them with the loan paperwork. For SUV-specific financing context, see this used SUV financing guide for Pontoon Beach.
Have questions about reviewing used-vehicle financing options? Discuss financing options with 111 Auto Sales before making your decision.
Explore Used-Car Financing Options Near Cahokia with 111 Auto Sales
Once you understand the figures in a financing offer, ask how they apply to a vehicle you’re considering. 111 Auto Sales LLC is an independent used-vehicle dealership in Pontoon Beach that serves Cahokia-area shoppers and offers financing options. Terms depend on the offer and applicant, so ask for current details rather than assuming a particular rate, payment, or approval.
What can you discuss with a local used-car dealership?
Bring your questions and ask which financing options are currently available and what information is needed to discuss them. You can clarify who the lender is, which documents describe the offer, and how to compare its written terms with outside financing. If you’re considering an optional warranty, request its product documents and review it separately from the loan so you can understand its terms and cost.
Your vehicle choice can shape the questions you ask. If you’re considering a sedan, this related guide to used-car financing options in Pontoon Beach offers additional context. Confirm current details directly for the vehicle and financing offer you’re considering. Understanding used car financing terms Cahokia IL means applying general definitions to the specific written documents in front of you.
How can you take the next step with confidence?
Keep the process practical. Bring your questions, any outside pre-approval details you want to compare, and the written offer if you have one. Review the final agreement carefully and check that its terms match what was discussed. Ask for clarification about any difference before deciding.
You can explore used sedans, SUVs, trucks, and vans by category, while confirming directly which vehicles are currently available. Consider the vehicle and financing together. A clear understanding of both can help you decide whether the option fits your needs and budget.
For a practical next step, discuss available used-car financing options with 111 Auto Sales and ask about current vehicle details. You can take time to understand the written terms before deciding whether to proceed.
Make Your Financing Decision With Clarity
Understanding used car financing terms Cahokia IL can help you evaluate an offer with greater confidence. Focus on the full agreement: compare APR, amount financed, loan term, fees, and total payments rather than relying on the monthly payment alone. Before signing, check that the contract matches the written offer and review optional warranty documents separately from the loan.
Questions are a useful part of the process. Ask who the lender is, clarify any figures or conditions you don’t understand, and take time to review the paperwork. A clear explanation can help you decide whether the vehicle and financing terms fit your needs.
111 Auto Sales LLC is an independent used-vehicle dealership in Pontoon Beach serving Cahokia-area shoppers. Financing options and optional extended warranties are available to discuss, though specific terms depend on the offer and your situation. Discuss used-car financing options with 111 Auto Sales and review the available used-vehicle selection. Take the next step at your own pace, with the information you need to make a considered choice.
Frequently Asked Questions
What does APR mean when financing a used car?
APR, or annual percentage rate, is an annualized measure of borrowing cost. It reflects the interest rate and may include certain loan fees, so it can differ from the interest rate alone. Check the written disclosures to see how APR is presented alongside fees, the payment schedule, and total payments. APR comparisons are most useful when offers use the same vehicle price, down payment, and loan term.
Is the monthly payment the best way to compare used-car loans?
No. A monthly payment shows the scheduled installment, but it doesn’t reveal the full cost or length of the commitment. Compare APR, amount financed, term, fees, and total of payments across written offers based on the same vehicle and transaction details. A lower payment could reflect a longer term, which means repaying over more time. Review the entire agreement to decide which offer fits your budget and needs.
What is the difference between a down payment and an amount financed?
A down payment is money paid upfront toward the vehicle purchase. The amount financed is the portion of the transaction borrowed, as shown in the contract. A larger down payment may reduce the amount borrowed, depending on the transaction. Check how the paperwork accounts for your down payment, trade-in value, taxes, fees, and optional products. Ask for clarification if the amount financed doesn’t match your understanding of the transaction.
Can I use an outside lender instead of dealership-arranged financing?
Yes, you can explore financing from a bank, credit union, or another lender rather than relying only on dealer-arranged financing. Ask each lender for written terms and compare offers using the same vehicle price, down payment, trade-in, and other transaction details. Terms and availability depend on the lender and your application. If you have an outside pre-approval, bring the written details so you can compare the actual figures.
Does choosing a longer loan term always make a used car more affordable?
No. A longer term may lower each scheduled payment by spreading repayment over more time, but you’ll be paying for longer and the total borrowing cost may increase. Whether the offer works for you depends on APR, amount financed, fees, and contract terms. Consider the overall budget for owning the vehicle, not just the installment. Compare total payments and repayment length before choosing a loan.
Should an extended warranty be included in my used-car financing?
Not automatically. Treat an extended warranty as an optional product and review its terms separately from the loan. Ask whether it’s included in the offer, what the documents say it covers, and whether its cost is added to the amount financed. Don’t assume coverage, exclusions, or cancellation rules. Compare the product paperwork with the financing contract, and make sure you understand how any selected option affects the agreement before signing.
What should I check before signing used-car financing documents?
Confirm the vehicle and buyer details, then check the lender, APR, amount financed, term, payment schedule, fees, and total payments. Compare the contract with the written offer and ask about any unexplained difference. Review optional products separately, request copies, and take time to read the documents. For understanding used car financing terms Cahokia IL, shoppers can ask 111 Auto Sales in Pontoon Beach about current options. The dealership serves Cahokia, Granite City, Collinsville, St. Louis, Belleville, Maryville, Troy, Alton, Highland, O’Fallon, Glen Carbon, and Swansea.


