
Could a limited credit history be one part of a first car loan application rather than an automatic roadblock? If you’re researching car loans for college students with no credit Troy IL, it’s reasonable to wonder whether variable student income and little borrowing history will make approval difficult. Lenders may also consider income, employment, a down payment, and whether a qualified co-signer is part of the application. Approval and terms depend on the lender.
A practical plan starts with knowing what you can comfortably afford, gathering the right documents, and comparing more than the monthly payment. This guide explains what lenders may consider beyond a credit score, what to prepare before applying, and how to review APR, loan length, and total repayment cost. You’ll also learn how a used vehicle may fit a student budget and explore financing options near Troy. 111 Auto Sales in Pontoon Beach offers pre-owned sedans, SUVs, trucks, and vans, along with vehicle financing. With a clear budget and organized application, you can take informed next steps without assuming a particular loan outcome.
Key Takeaways
- Having no credit history is different from having negative credit history, and neither alone determines a lender’s decision.
- For car loans for college students with no credit Troy IL, compare applying independently, using a qualified co-signer, or making a down payment. None guarantees approval.
- Build a budget that accounts for recurring vehicle expenses, not just a potential monthly loan payment.
- Review APR, loan length, total repayment, and fees together to understand the full cost of financing.
- Use a clear sequence before choosing a vehicle: set your budget, organize documents, explore financing, then compare pre-owned vehicle categories that fit your needs.
Can college students with no credit get car loans near Troy, IL?
Possibly. Having limited or no credit history doesn’t, by itself, determine the outcome of an auto-loan application. Lenders assess applications under their own criteria, so approval, interest rate, and repayment terms depend on the lender and the applicant’s circumstances. Preparation can help you understand your options, but it can’t guarantee a particular result.
A first-time auto loan is financing used to purchase a vehicle when the borrower has little or no previous auto-loan experience. It’s separate from a student loan, which is borrowed to pay for education expenses. Student-loan payments or history may appear in a credit file, depending on the account and reporting, but a student loan is not the same product as an auto loan.
What does “no credit” mean for a first car loan?
A student with a thin credit file has little recorded borrowing and repayment history for a lender to review. That’s different from negative credit history, which may include reported late payments or other adverse marks. A no-credit borrower is someone whose credit file contains too little borrowing history to show a clear pattern of repayment.
A credit score can be one part of a lender’s review, but it doesn’t guarantee approval or denial on its own. For an overview of understanding your credit score, see how scores are used in the United States. A lender may also consider other information in the application, with specific criteria varying by lender.
Why does local context matter for Troy students?
For students in Troy and the Metro East, exploring a used vehicle and financing in the same regional market can make the search more practical. 111 Auto Sales in Pontoon Beach serves shoppers from Troy and nearby communities, including Granite City, Collinsville, St. Louis, Belleville, Maryville, Alton, Highland, O’Fallon, Glen Carbon, Swansea, and Cahokia. Its pre-owned sedans, SUVs, trucks, and vans offer different vehicle categories to consider alongside financing options.
Searching for car loans for college students with no credit Troy IL is a starting point, not a promise that every application will qualify. Focus on understanding the application and proposed terms before choosing a vehicle. Start by organizing a realistic budget and the information a lender may request, then review the financing details available for your situation.
How can a student prepare for a no-credit auto-loan application?
Preparation can make the application process clearer, even though no document or financial detail guarantees approval. Organize your budget and information before applying so you can answer questions accurately and judge whether a proposed payment fits your student finances.
Which documents and income details should students organize?
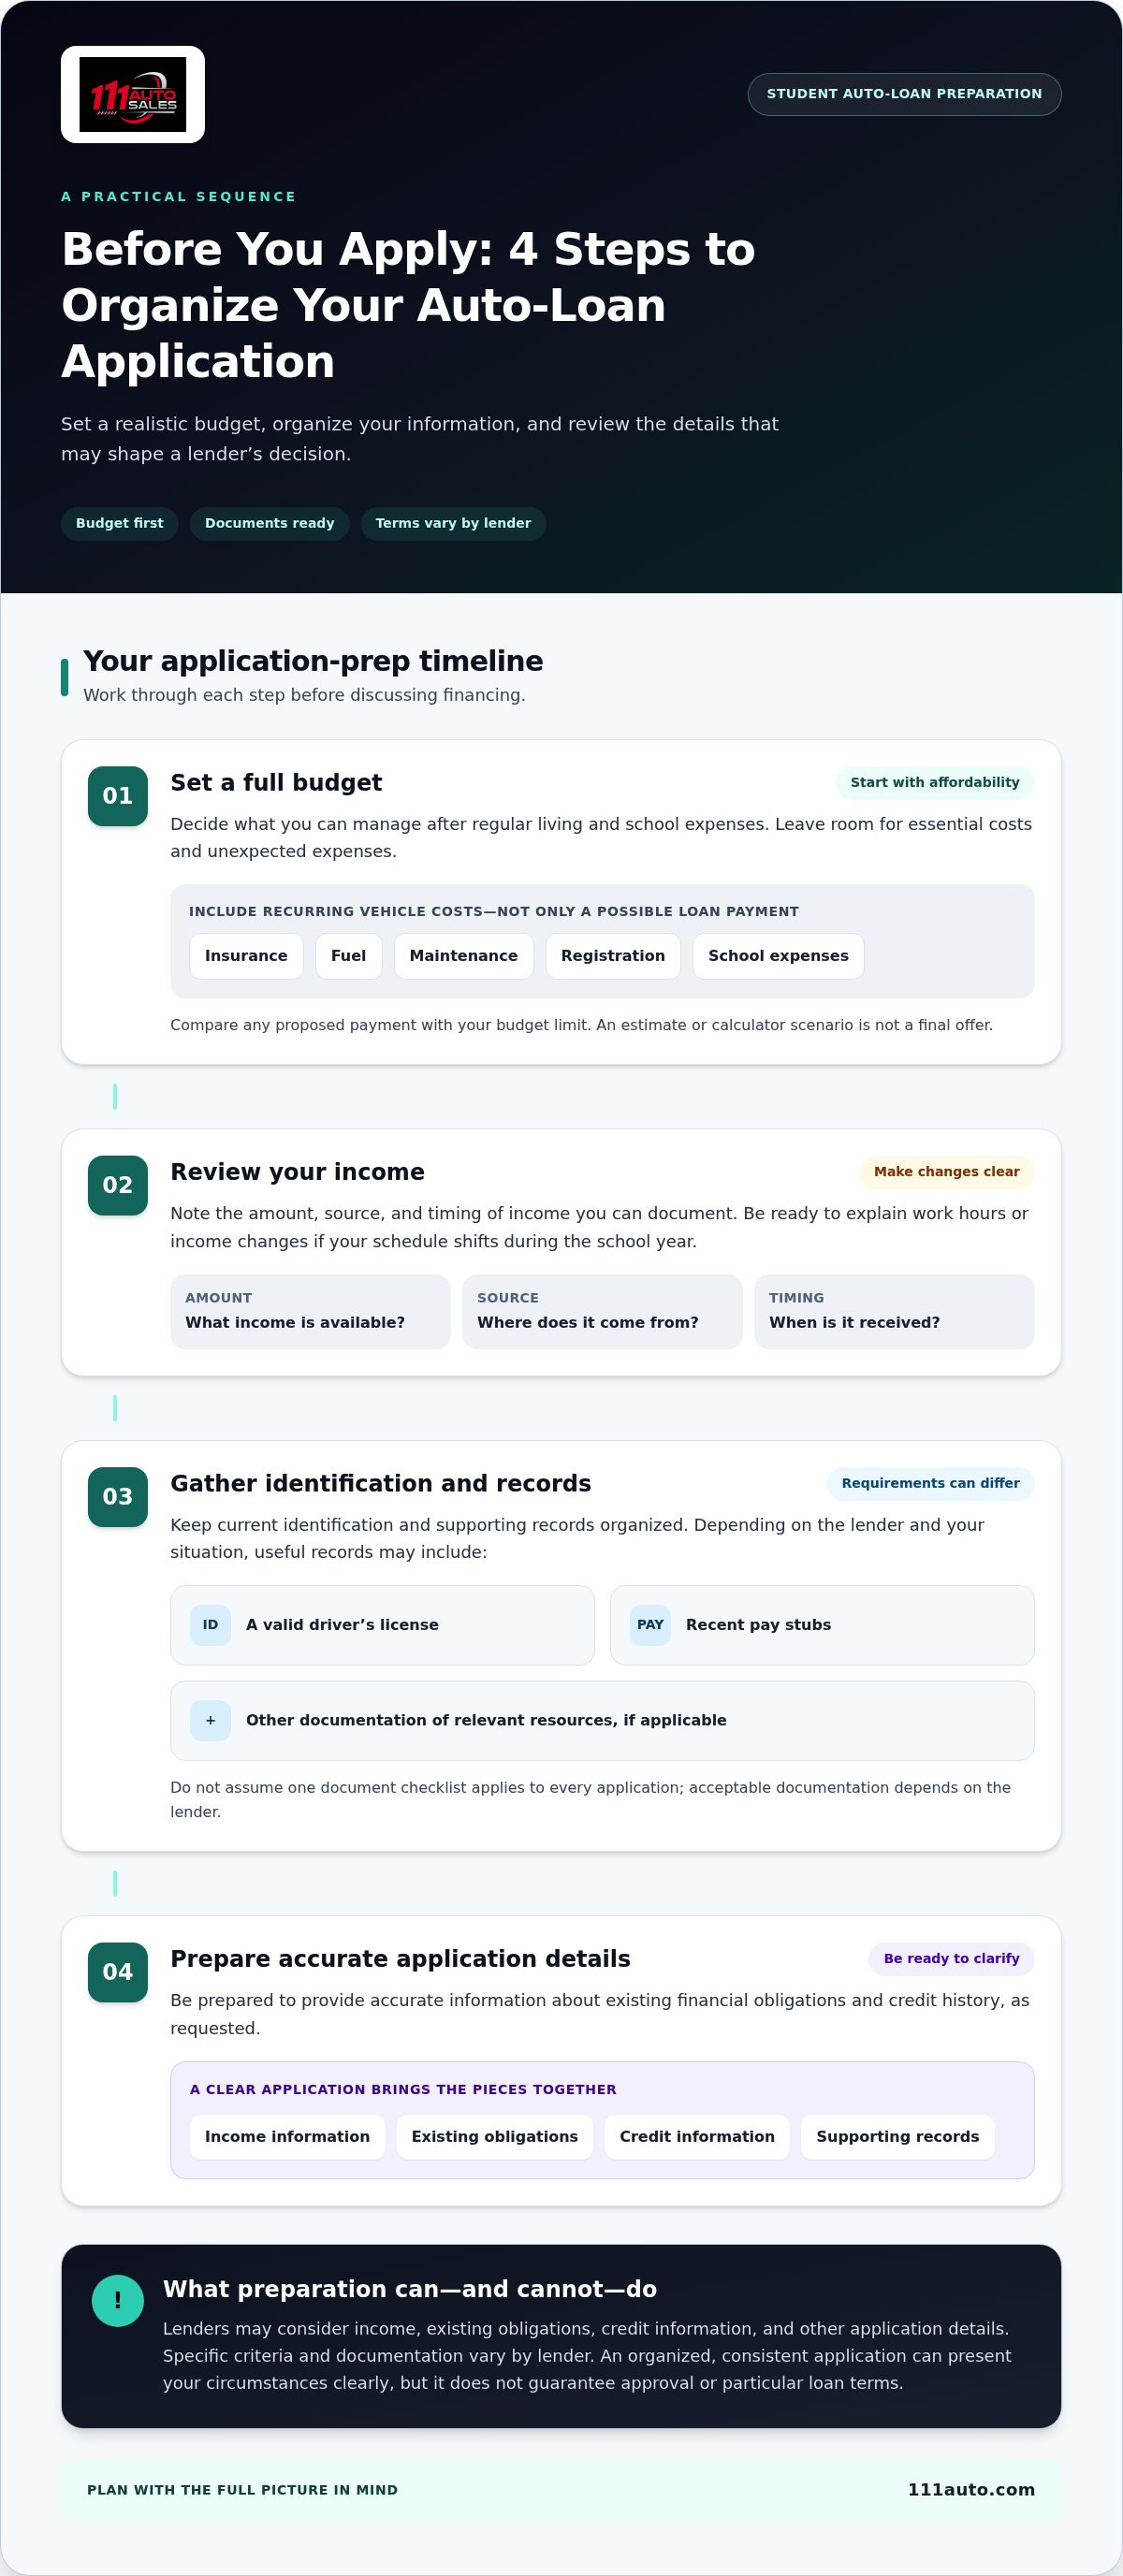
Start with identification and current information about income. Depending on the lender and your situation, useful records may include a valid driver’s license, recent pay stubs, or other documentation of relevant resources. Requirements vary, so don’t assume one checklist applies to every application. Be ready to describe work hours or income changes if your schedule shifts during the school year.
Use this sequence to get ready:
- Set a full budget. Decide what you can manage after regular living and school expenses.
- Review income. Note the amount, source, and timing of income you can document.
- Gather identification. Keep your current ID and supporting records organized.
- Prepare application details. Be ready to provide accurate information about existing financial obligations and credit history, as requested.
Lenders may assess income, existing obligations, credit information, and other details in an application. Which factors matter, and what documentation is acceptable, depends on the lender. A complete, consistent application presents your circumstances clearly, but doesn’t determine the lender’s decision.
How should students set a realistic car budget?
Don’t plan around a potential loan payment alone. Add recurring costs such as insurance, fuel, maintenance, and registration. Then account for school-related expenses and income that may vary with your class or work schedule. A personal budget or loan calculator can help you test payment scenarios, but an estimate isn’t a final offer.
Before discussing financing, decide what amount leaves room for essential expenses and unexpected costs. Compare any proposed payment against that limit. For plain-language definitions of APR, down payment, and co-signer, review the Consumer Financial Protection Bureau’s guide to understanding auto loan terms.
With a budget and documents in order, students considering car loans for college students with no credit Troy IL can approach the next step with a clearer picture of what they can afford. Explore pre-owned vehicles and financing options as part of your planning.
No credit, a co-signer, or a down payment: what should students weigh?
No credit history doesn’t automatically make financing impossible. It means a lender has limited borrowing history to assess, so the rest of the application may matter. Lenders review the full application because repayment capacity, credit information, and loan details together provide a fuller picture than any single factor. The available choices have different responsibilities and costs, and none guarantees approval or particular terms.
A student can apply independently, include a qualified co-signer, or contribute a down payment. Applying alone focuses the application on the student’s own information. A co-signer may add another person’s financial and credit details for the lender to consider. A down payment reduces the amount being financed. Which approach fits depends on the student’s circumstances and the lender’s criteria.
Could a co-signer help a student with no credit?
A co-signer may give a lender additional information to consider, but agreeing to co-sign carries real responsibility. Under the loan agreement, the co-signer may be responsible for payments if the student doesn’t pay. That obligation can affect both people, so discuss the repayment plan, payment responsibilities, and possible impact on the co-signer’s finances before applying.
Read the proposed loan documents together before signing. Make sure both people understand who is responsible, what happens if a payment is missed, and the total obligations described in the agreement. A co-signer’s involvement doesn’t promise approval or a particular interest rate.
Does a down payment or part-time income change the application?
A down payment can reduce the amount borrowed, while documented part-time income can help show the resources available for payments. Students with changing work hours should consider how steady that income is across the school year and whether it leaves enough for regular expenses. These details may contribute to the lender’s assessment, but neither guarantees approval, a lower rate, or specific terms.
Compare the options against a realistic budget. Applying independently may avoid involving someone else, while a co-signer means shared responsibility under the agreement. Paying money upfront may lower the amount financed, but shouldn’t leave you without funds for essential expenses. For students considering car loans for college students with no credit Troy IL, a sound choice is one they understand and can manage under the terms offered.
What steps should Troy students take before choosing a used car loan?
Separate the financing decision from the vehicle choice. This sequence can help you assess what fits your finances before focusing on a specific vehicle:
- Set your budget. Account for a potential payment and recurring ownership expenses, then decide what remains manageable.
- Organize your documents. Keep identification, income details, and other application information ready.
- Explore financing. Review the options available for your circumstances without assuming approval or particular terms.
- Compare the written terms. Look beyond the monthly payment to APR, loan length, total repayment, and any fees shown in the agreement.
- Select a vehicle. Match your choice to your budget, regular driving, and campus routine.
Which loan terms should a first-time borrower compare?
APR represents the annual cost of borrowing, while a monthly payment is the amount due each month under the loan schedule. A payment that seems manageable doesn’t show the full cost of the loan. Review the APR alongside the amount financed and the total repayment stated in the offer.
Loan length is the scheduled repayment period. A longer term spreads payments over more time, but may also increase the total amount repaid and extend how long you owe. Fees can affect the amount due or the overall cost, so read how each one is described in the written agreement. If a term or charge is unclear, ask for an explanation before signing. Loan terms and applicable legal details can vary, so rely on the current written agreement and relevant official information rather than assumptions.
How should the vehicle fit the student’s budget and routine?
Consider where you’ll drive most, how much passenger or cargo space you need, and what campus parking is like. A pre-owned sedan may suit a student who mainly commutes alone and wants a vehicle sized for everyday trips, but it isn’t the right fit for everyone. Choose based on your actual use, not features you’re unlikely to need, and make sure the vehicle’s cost works with your full budget.
If you need more room, explore pre-owned SUV options alongside the financing details. For students comparing car loans for college students with no credit Troy IL, keeping the vehicle choice and loan terms within a realistic budget can make the decision more manageable. Explore used vehicles and financing options as you consider your next step.
How can 111 Auto Sales help students near Troy explore financing?
For students researching car loans for college students with no credit Troy IL, considering a used-vehicle search alongside financing options can make the process more practical. 111 Auto Sales is a used-car dealership in Pontoon Beach serving shoppers from Troy and nearby communities. The dealership offers vehicle financing and pre-owned sedans, SUVs, trucks, and vans to consider as you compare your transportation needs with your budget.
What can students consider when shopping at a local used-car dealership?
Start with how you’ll use the vehicle. A student commuting to class may have different space and driving needs from someone regularly carrying passengers, work equipment, or personal belongings. Consider those needs alongside the full ownership budget, including costs beyond a potential loan payment. The right vehicle is one that fits both your routine and what you can manage financially.
Consider vehicle selection and financing together. The vehicle you choose affects how much you may need to finance, while the proposed loan terms affect whether the purchase fits your budget. Review the written terms carefully and don’t assume a particular vehicle or application will lead to a specific approval outcome.
Optional extended warranty packages are a separate protection decision, not a requirement for financing. Consider whether this additional coverage suits your circumstances and review its terms independently from the loan agreement. Keeping those decisions separate makes it easier to understand what you’re agreeing to.
What should students do next near Troy, Illinois?
Before exploring vehicles, prepare a clear budget and organize your application information. Be ready to discuss which vehicle categories fit your needs and review financing terms in writing. Ask for an explanation of any part of the purchase or loan process you don’t understand. A lender’s decision and available terms depend on the individual application, so approach the process with realistic expectations.
111 Auto Sales gives Troy-area shoppers a local place to consider pre-owned vehicles and financing together. Take the next step at your own pace: Explore used vehicles and financing at 111 Auto Sales.
Take Your First Loan Step With a Clear Plan
A first auto loan can feel uncertain without an established credit history, but preparation gives you a clearer way to evaluate your options. Set a realistic budget that includes ongoing vehicle expenses, organize your application information, and compare APR, loan length, fees, and total repayment rather than focusing only on the monthly payment. A co-signer or down payment may be worth considering, but neither guarantees approval or specific terms.
For students exploring car loans for college students with no credit Troy IL, 111 Auto Sales is a local dealership in Pontoon Beach serving Troy and nearby communities. You can consider pre-owned sedans, SUVs, trucks, and vans while exploring vehicle financing. Optional extended warranties are a separate choice to weigh against your needs and budget.
Take the next step at your own pace. Explore used vehicles and financing at 111 Auto Sales, and move forward with a plan that fits your circumstances.
Frequently Asked Questions
Can a college student get a car loan with no credit?
Yes, a college student may be able to get a car loan with no established credit history, but approval depends on the lender and the individual application. Lenders may consider documented income, existing obligations, credit information, and other application details. Students researching car loans for college students with no credit Troy IL can prepare by setting a realistic budget and organizing relevant information before exploring financing.
Does having no credit mean I will be denied an auto loan?
No. Having no credit history doesn’t automatically mean a student will be denied. A thin credit file gives a lender limited repayment history to assess, while negative credit history may include recorded late payments or other adverse marks. Neither a credit score nor the absence of one guarantees an outcome. Lenders use their own criteria, so approval, APR, and loan terms depend on the application.
Can a co-signer help a student qualify for a car loan?
A co-signer may give a lender additional financial and credit information to consider when the student has little borrowing history. However, a co-signer may share legal responsibility for the loan and could be responsible for payments if the student doesn’t pay. Both people should discuss repayment expectations and read the proposed agreement together before signing. A co-signer doesn’t guarantee approval or specific terms.
How much should a college student budget for a car loan?
Set a limit based on your full monthly budget rather than choosing a payment in isolation. Include expected loan payments along with insurance, fuel, maintenance, registration, school costs, and other regular expenses. If your work hours or income change during the semester, leave room for that variation. Compare APR, loan length, and total repayment, too, since a manageable payment alone doesn’t show the complete borrowing cost.
What documents may a student need for an auto-loan application?
Gather a valid form of identification and current information about income before starting an application. Depending on the lender and your circumstances, this may include recent pay stubs or other documentation of relevant resources. Be ready to provide accurate application details, including information about existing obligations. Requirements vary, so no single document list applies to every lender, and submitting paperwork doesn’t ensure approval.
Is dealership financing an option for students near Troy, IL?
Yes, dealership financing is an option students can explore near Troy. 111 Auto Sales is based in Pontoon Beach and serves shoppers from Troy, Granite City, Collinsville, St. Louis, Belleville, Maryville, Alton, Highland, O’Fallon, Glen Carbon, Swansea, and Cahokia. The dealership offers financing with pre-owned sedans, SUVs, trucks, and vans. Optional extended warranties are a separate purchase decision, and financing approval and terms depend on the application.


