
Could a lower monthly payment end up costing more over the life of a loan? When you’re exploring used car financing Pontoon Beach IL, the payment is only one part of the decision. Your credit history may affect the financing terms available, and the loan term can change both the monthly amount and the total repayment.
Before choosing a vehicle or applying for financing, it helps to understand how the terms work. This guide explains what commonly shapes a financing decision and how to compare loan terms with your budget, rather than focusing only on a target monthly payment.
We’ll cover how to prepare, what to review when comparing financing options, and how to match a pre-owned sedan, SUV, truck, or van to your needs and budget. You’ll also learn why extended warranty options are a separate consideration in planning for vehicle ownership. At 111 Auto Sales LLC in Pontoon Beach, you can explore pre-owned vehicles and financing together as part of your shopping process.
Key Takeaways
- Used car financing Pontoon Beach IL is easier to evaluate when you consider your budget and vehicle needs alongside the financing terms.
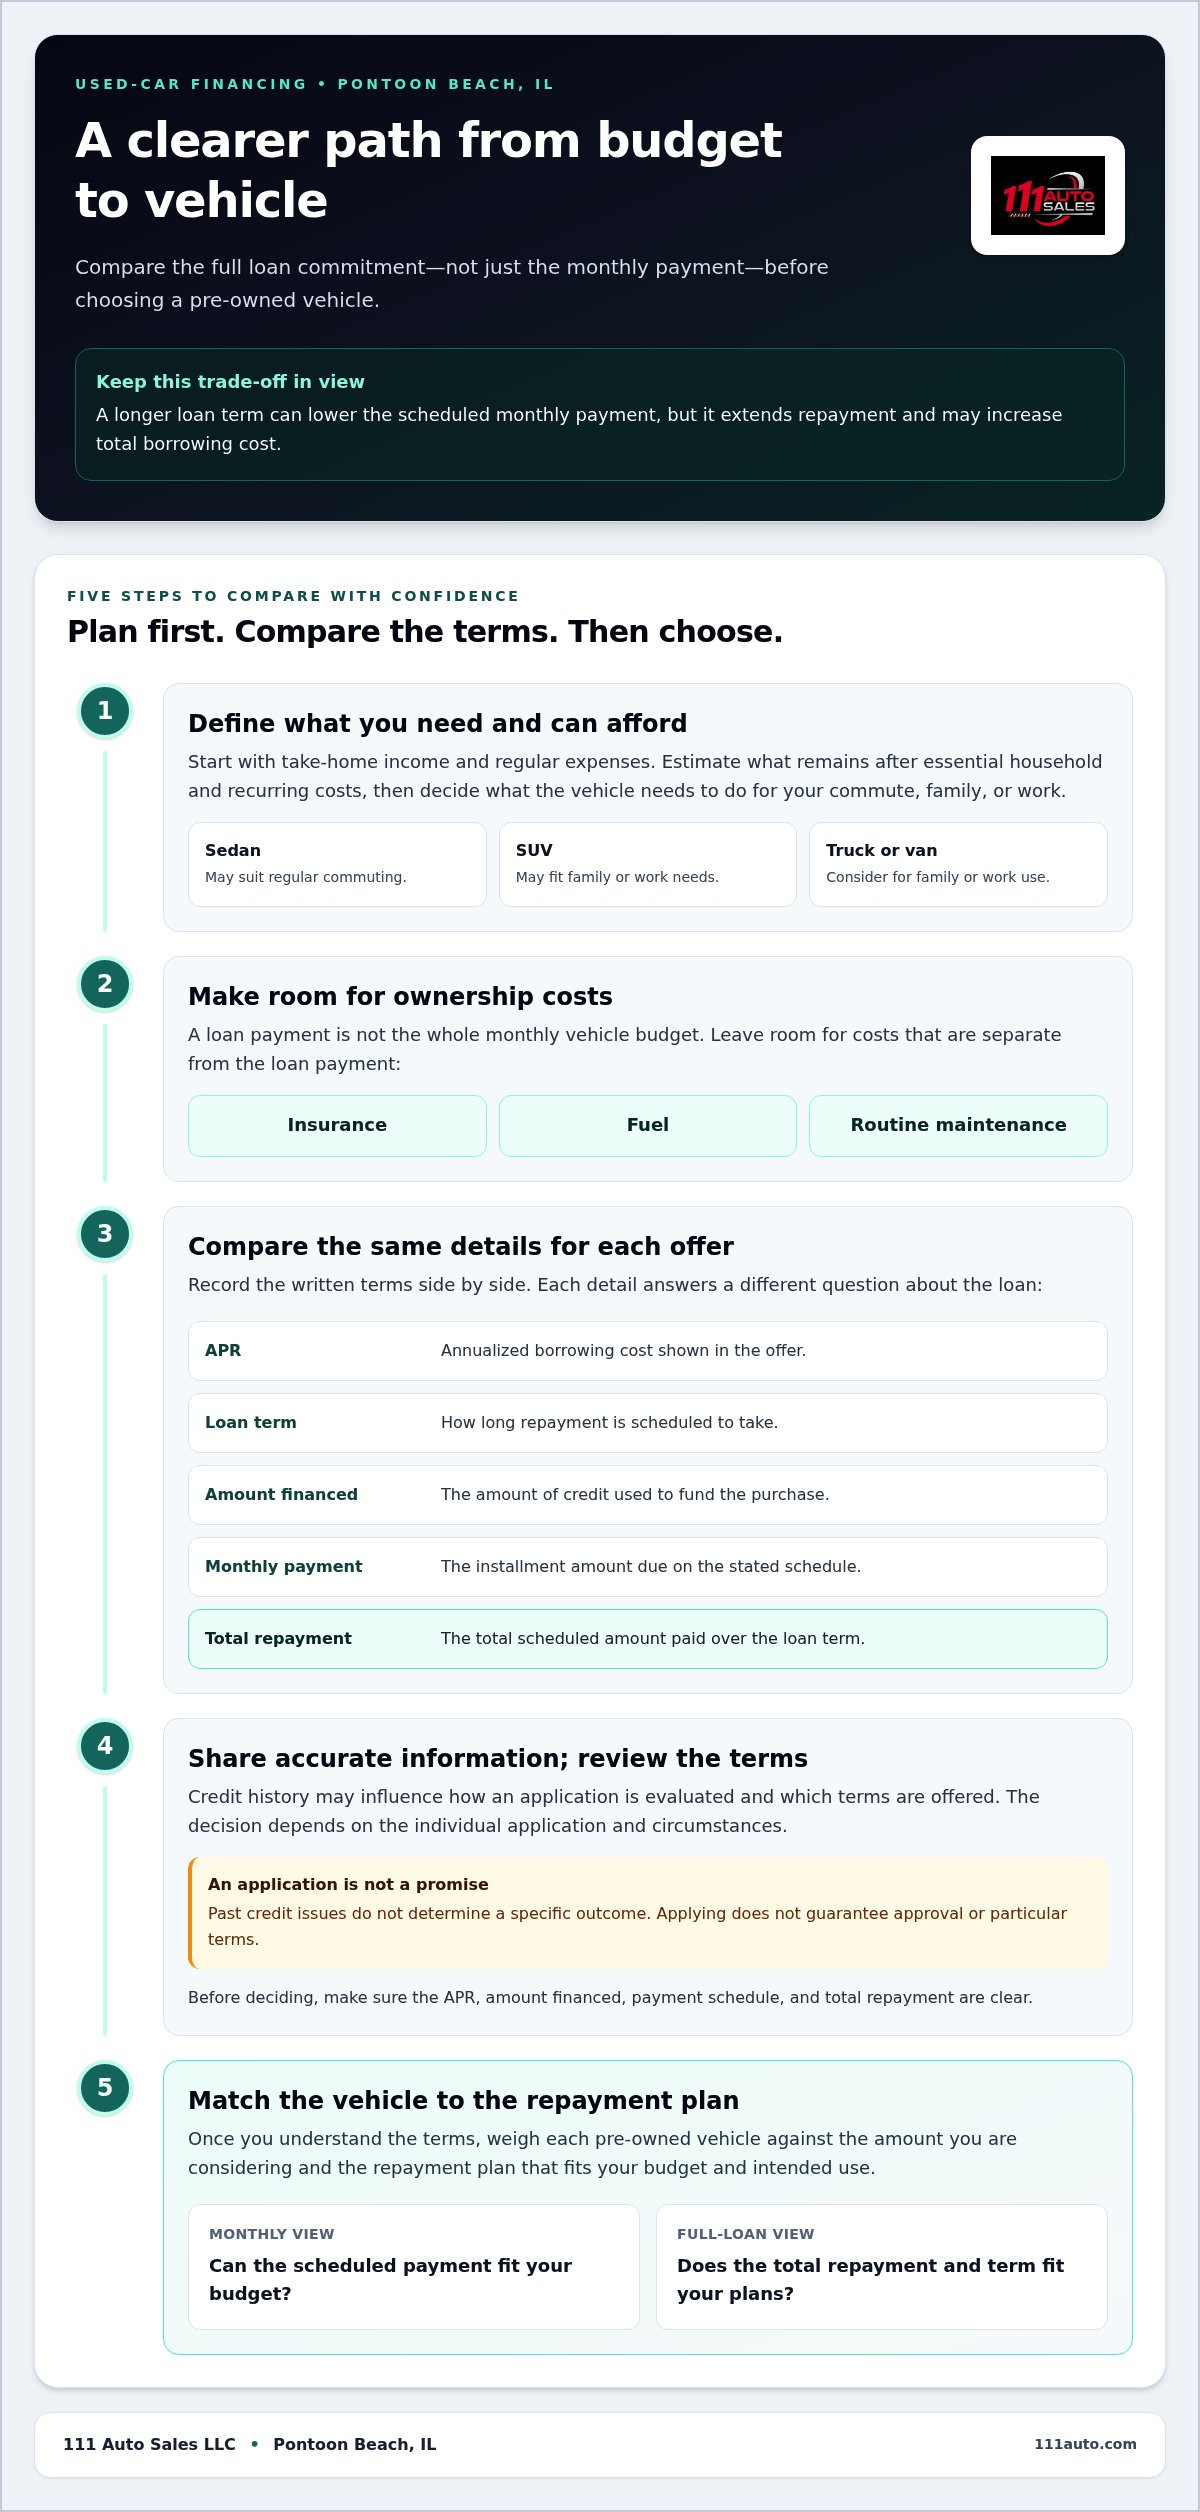
- Compare APR, loan term, amount financed, monthly payment, and total repayment. A manageable payment alone doesn’t show the full loan commitment.
- Past credit issues don’t determine a specific approval outcome. Applying is not a guarantee of approval or particular terms.
- Prepare by setting a budget, gathering relevant information, discussing financing, comparing terms, and then choosing a vehicle.
- Consider how pre-owned sedans, SUVs, trucks, and vans at 111 Auto Sales fit your intended use and budget.
Pontoon Beach, IL Used Car Financing: Budget & Needs
Financing a vehicle can feel uncertain, especially if your credit history raises questions or you’re unsure what fits your budget. With used car financing Pontoon Beach IL, start by defining what you need the vehicle to do and what you can comfortably afford. Used-car financing means borrowing to purchase a pre-owned vehicle and repaying the amount borrowed under agreed terms.
Consider the vehicle and financing together. A car that suits your commute, family, or work still has to fit your finances over time. A sedan may work well for regular commuting, while an SUV, truck, or van may better meet family or work needs. Vehicle type, amount borrowed, and financing terms all shape the decision. For a neutral introduction to understanding car finance options, review how vehicle financing can be structured.
What does used car financing involve?
You choose a pre-owned vehicle and consider how to pay for it. 111 Auto Sales sells pre-owned vehicles and provides financing options as part of the purchase process. The financing decision and terms depend on the individual application and circumstances, so neither approval nor particular terms can be assumed in advance.
These terms help make an offer easier to understand:
- Principal: The amount borrowed to purchase the vehicle.
- APR: The annual percentage rate, a measure of borrowing cost expressed as a yearly rate.
- Loan term: The period over which the loan is scheduled to be repaid.
- Monthly payment: The amount scheduled for each installment under the agreed terms.
How to set a comfortable vehicle budget
Begin with your take-home income and regular expenses. Then account for ownership costs alongside any expected loan payment. Insurance, fuel, and maintenance can affect what feels manageable each month, even though they aren’t part of the loan payment itself.
- Estimate what remains after essential household and recurring expenses.
- Leave room in your budget for insurance, fuel, and routine maintenance.
- Consider how often you’ll drive and whether the vehicle must support family or work needs.
A longer loan term can reduce the scheduled monthly payment by spreading repayment over more time, but it also means carrying the loan for longer. Depending on the terms, a longer repayment period may increase the total borrowing cost. Judge affordability by your overall ownership plan, not by a monthly payment in isolation.
Compare Used Car Financing Terms Before Choosing a Vehicle
A financing offer is more than a monthly payment. Compare its main terms side by side before settling on a vehicle, so you can see how the loan structure affects your monthly budget and the full repayment commitment. For shoppers researching used car financing Pontoon Beach IL, this makes it easier to consider financing and vehicle choice together.
Which financing details should buyers compare?
APR is the annualized cost of borrowing, while your monthly payment is the amount scheduled for each installment. The APR reflects the cost of credit under the loan’s stated terms; the payment shows what you’re scheduled to pay regularly. A lower payment may come with a longer repayment period, so compare total repayment as well as the monthly amount. The FTC guide to car financing offers additional guidance on comparing offers and reviewing contract terms.
| Financing detail | What to record and review |
|---|---|
| APR | The annualized borrowing cost shown in the offer. |
| Loan term | How long repayment is scheduled to take. |
| Amount financed | The amount of credit used to fund the purchase. |
| Monthly payment | The installment amount due on the stated schedule. |
| Total repayment | The total scheduled amount paid over the loan term. |
Record the same details for each offer you’re comparing, and review the written terms rather than relying on a payment estimate alone. Down payment, vehicle selection, credit profile, and loan structure can all affect an offer. A longer term may reduce each scheduled payment, but extends the time you’re repaying. Consider the total repayment and whether the term fits your plans for the vehicle.
How can credit history affect a used-car loan?
Credit history may influence how an application is evaluated and which terms are offered. It doesn’t determine a specific outcome on its own, and no general rule can guarantee approval or a particular APR. The financing decision depends on the individual application and circumstances.
Provide accurate, complete information. Clear and consistent details can help avoid unnecessary questions during the application process. If terms are presented, compare them with your budget and make sure the APR, amount financed, payment schedule, and total repayment are clear before deciding.
Once you’ve identified financing terms that fit your needs, explore the pre-owned vehicle selection at 111 Auto Sales LLC. Weigh each vehicle against the amount and repayment plan you’re considering.
Address Credit Concerns and Common Used-Car Financing Misconceptions
Past credit issues can make financing feel uncertain, but they don’t make the outcome predictable. Credit history is one part of an application, not a guarantee of approval or a specific rate. An application allows your individual circumstances to be reviewed; it doesn’t promise that financing will be offered or that the terms will match your expectations.
Only a review of your individual application can determine the financing terms available to you. Keep that distinction in mind as you consider used car financing Pontoon Beach IL. Set a realistic vehicle budget first, so you can compare any offer with your actual needs rather than feeling pressured to stretch because financing might be available.
Can buyers with limited or challenged credit apply?
You can begin a financing conversation without assuming what the decision will be. Depending on the financing process, factors such as income, existing financial obligations, down payment, and credit history may be considered. Their relevance and effect can vary from one application to another, so general advice or another person’s experience can’t predict your result.
Be straightforward and provide accurate information. This gives the application a clear basis for review and helps avoid confusion if details need clarification. Focus on what you can plan: the vehicle that meets your needs, the amount you’re comfortable financing, and the payment and repayment period that fit your budget.
Does a lower payment always mean a better loan?
Not necessarily. A payment can change with both the amount financed and the loan length. Spreading repayment over a longer period may lower each scheduled payment, but it also keeps you in repayment longer and can increase the total amount paid under the terms. Consider the full commitment, not just whether the next payment seems manageable.
The vehicle matters, too. A lower payment on a vehicle that doesn’t suit your commute, family responsibilities, or work needs may not be the right fit. Compare the vehicle and financing as one decision: review the amount financed, APR, term, scheduled payment, and total repayment together. The Consumer Financial Protection Bureau’s guidance on negotiating your auto loan explains why buyers should look beyond the monthly amount and understand the terms they’re considering.
Before proceeding, consider whether the vehicle serves its intended purpose and whether the repayment plan leaves room for regular ownership expenses. A careful review won’t predict an approval decision, but it can help you make a more informed choice if terms are offered.
Prepare for Used Car Financing in Pontoon Beach Step by Step
Preparing for a financing conversation can help you connect your budget with a vehicle that suits your day-to-day needs. If you’re considering used car financing Pontoon Beach IL, work through these steps before choosing a pre-owned vehicle at 111 Auto Sales LLC.
- Set a practical budget. Review income and regular expenses, then consider what room remains for a vehicle payment, insurance, fuel, and maintenance. Keep your intended payment range in mind without treating it as the full cost of ownership.
- Gather relevant information. Prepare accurate personal, contact, income, and housing details for the financing process. Identification and income information are examples of details that may be requested. Requirements vary by application and process.
- Discuss financing. Share your budget and intended vehicle use as you discuss financing with the dealership. Clear, consistent information can keep the conversation focused on your circumstances and goals.
- Compare proposed terms. Review the APR, loan term, amount financed, scheduled payment, and total repayment. Make sure you understand the written terms and how they fit your budget before deciding.
- Choose a vehicle that fits. Consider your commute, family space, or work needs, then weigh the vehicle against the financing terms. Avoid choosing by payment alone.
Before the financing discussion, organize the details you may need. An application might ask for identification, current contact details, income information, or housing details. The documents and details requested can vary, so provide information that’s accurate and consistent throughout the process.
Next, match the vehicle type to its purpose. A sedan may suit regular commuting, while an SUV may offer the space your household needs. A truck or van may better suit certain work or transport needs. At 111 Auto Sales LLC in Pontoon Beach, you can explore pre-owned sedans, SUVs, trucks, and vans, including budget-friendly vehicles priced under $10,000. For more focused reading, see this used sedan financing guide and used SUV financing resource.
Before deciding, make sure the proposed APR, repayment period, and payment are clear, and consider whether the vehicle fits your broader ownership budget. Explore pre-owned vehicles and financing at 111 Auto Sales LLC as you plan your next steps.
Explore Used Car Financing and Pre-Owned Vehicles at 111 Auto Sales
At 111 Auto Sales LLC, vehicle financing is part of the pre-owned vehicle shopping process in Pontoon Beach. We offer pre-owned sedans, SUVs, trucks, and vans, giving shoppers several vehicle types to consider as they weigh daily needs against their budget. Our inventory includes budget-friendly vehicles priced under $10,000, so you can compare options with your spending plan in mind.
What can shoppers expect when exploring financing locally?
Start with a practical conversation about what you need from a vehicle, the budget you’ve set, and the financing options you’re considering. Whether you’re commuting, making room for family, or looking for work transportation, explaining your priorities can help keep the vehicle search focused. Financing decisions and terms depend on the individual application and process, so this conversation isn’t a promise of approval or specific terms.
111 Auto Sales LLC serves Pontoon Beach and nearby Metro East communities, including Granite City and Collinsville. Looking at vehicle needs and financing together can help make the next step clearer: compare suitable vehicle types, then review the applicable financing terms before deciding.
What is a useful next step for Pontoon Beach car buyers?
Begin by reviewing pre-owned vehicles and narrowing your search to options that suit your everyday use. A sedan may fit a commute, while an SUV, truck, or van may better support household or work needs. Consider each vehicle in relation to the financing terms offered, rather than treating the vehicle and loan as separate decisions.
Extended warranty options are another consideration in planning vehicle ownership. They’re separate from financing and aren’t a requirement for a loan. Review the warranty terms separately as you consider how to plan for ownership.
Before moving forward, make sure you understand the applicable financing terms and feel comfortable with your vehicle choice. A careful review can help you make a decision based on both your needs and your budget. Explore used vehicles and financing at 111 Auto Sales LLC.
Take the Next Step Toward a Used Vehicle That Fits
A confident purchase starts with a clear budget and a vehicle that suits your everyday needs. As you consider used car financing Pontoon Beach IL, compare APR, loan term, monthly payment, and total repayment rather than judging an offer by its payment alone. Credit history may affect an application, but it can’t predict a specific approval decision or financing terms.
111 Auto Sales is a Pontoon Beach dealership serving nearby Metro East communities, with pre-owned sedans, SUVs, trucks, and vans, plus vehicle financing. Our inventory includes vehicles priced under $10,000, and extended warranty options are available as a separate part of planning for ownership. Consider the vehicle alongside the financing terms, and take time to understand the full commitment before deciding.
Explore used vehicles and financing at 111 Auto Sales to compare your options and find a pre-owned vehicle that fits your needs and budget.
Frequently Asked Questions
Can I get used car financing in Pontoon Beach with bad credit?
You may apply, but past credit issues don’t predict whether financing will be approved or what terms may be offered. Each application is reviewed based on individual circumstances and the financing process. For used car financing Pontoon Beach IL, set a realistic vehicle budget before applying, then evaluate any proposed terms against what you can manage. Applying is not a guarantee of approval, a particular APR, or a specific payment.
What information do I need to apply for used car financing?
Be ready to provide accurate personal and financial information. Exact requirements vary by application and financing process. Examples may include identification, contact details, income information, and housing details. Keep your information consistent and review it before submitting. 111 Auto Sales serves shoppers in Pontoon Beach and nearby communities, including Granite City, Collinsville, St. Louis, Belleville, Maryville, Troy, Alton, Highland, O’Fallon, Glen Carbon, Swansea, and Cahokia.
Does applying for used car financing affect my credit score?
It can, depending on whether the application involves a hard or soft credit inquiry. A hard inquiry may affect your credit score, while a soft inquiry generally doesn’t. The effect depends on the inquiry and your credit profile. Before authorizing an application, understand what type of inquiry will be used and whether it may affect your credit. Don’t assume every financing conversation or application has the same impact.
How much should I put down on a used car?
Choose a down payment that fits your finances without leaving too little for regular expenses and ownership costs. The amount can affect how much you finance and may influence the terms offered, but there’s no single amount that suits every buyer. Consider your income, expenses, insurance, fuel, and maintenance needs. Review the resulting amount financed, payment, and total repayment before deciding what feels manageable.
What should I compare when reviewing a used car loan?
Compare the APR, loan term, amount financed, scheduled monthly payment, and total repayment. APR reflects the annualized cost of borrowing under the stated terms, while the payment is the scheduled installment. A lower payment may result from a longer term, which extends repayment. Review all the figures together and make sure the written terms are clear before agreeing. The monthly payment alone doesn’t show the full commitment.
Can I choose my used car before discussing financing?
You can browse vehicles and identify the type that may suit your needs before discussing financing. Consider how you’ll use it, such as commuting, carrying family, or supporting work. Before making a final purchase decision, discuss financing and compare the proposed terms with your budget. Vehicle selection and financing affect one another, so reviewing both together can help you avoid focusing on a vehicle or payment in isolation.
Are extended warranties part of used car financing?
Extended warranty options are a separate consideration from financing, not automatically a required part of a loan. 111 Auto Sales offers extended warranty options alongside pre-owned sedans, SUVs, trucks, and vans. If you’re considering one, review its terms separately from the APR, loan term, and repayment details. This helps you understand the financing commitment and warranty option as distinct parts of planning for vehicle ownership.


