
What if the biggest obstacle to owning a vehicle isn't your budget, but the bank's refusal to fund it? Many drivers assume that lower price tags make for easier approvals, but most national lenders actually reject applications for amounts below five figures. If you're looking into financing a used car under $10000 Pontoon Beach, you've likely realized that standard financing routes often feel closed to budget-conscious buyers. It's frustrating to find a vehicle that fits your life only to be told the loan amount is too small for a traditional lender's time.
You deserve a path to ownership that respects your financial boundaries without sacrificing vehicle quality. This guide explains how to secure a loan for a sub-$10,000 vehicle while managing the current 2026 interest rate landscape. We'll break down the monthly payment math, explain why local expertise beats national algorithms, and show you how to ensure your affordable car remains a reliable asset through smart warranty choices. From understanding Illinois tax credits to finding specialized lenders, you'll gain the clarity needed to drive away with confidence.
Key Takeaways
- Understand why national banks often reject small-dollar loans and how specialized lenders bridge this gap for budget-friendly vehicles.
- Learn how to navigate the 2026 interest rate landscape by seeing how credit scores and vehicle age directly influence your monthly payments.
- Evaluate the strategic benefits of financing versus paying cash to preserve your emergency savings for future maintenance.
- Discover the specific steps for financing a used car under $10000 Pontoon Beach through local experts who specialize in affordable, high-quality inventory.
- Gain long-term peace of mind by learning how to include extended warranty options in your finance package for vehicles priced under $10,000.
Why Financing a Used Car Under $10,000 is Different
Financing a vehicle priced below the five-figure mark requires a specific strategy. While the car financing basics remain the same, the execution changes when you're looking at "small-dollar" auto loans. Many buyers assume that a smaller loan is easier to get. In reality, the opposite is often true because of how national lenders structure their portfolios. If you're looking into financing a used car under $10000 Pontoon Beach, you'll find that the local market operates differently than national aggregators suggest.
The primary reason for this difference is the profit margin for the lender. Processing a loan involves fixed costs, including credit checks, administrative labor, and title filing. For a large bank, these costs stay the same whether the loan is for $5,000 or $50,000. As a result, many national institutions simply exit the budget market, leaving a "lender gap" that only specialized local players can fill. Understanding how to navigate this gap is the first step toward securing reliable transportation.
The Minimum Loan Amount Hurdle
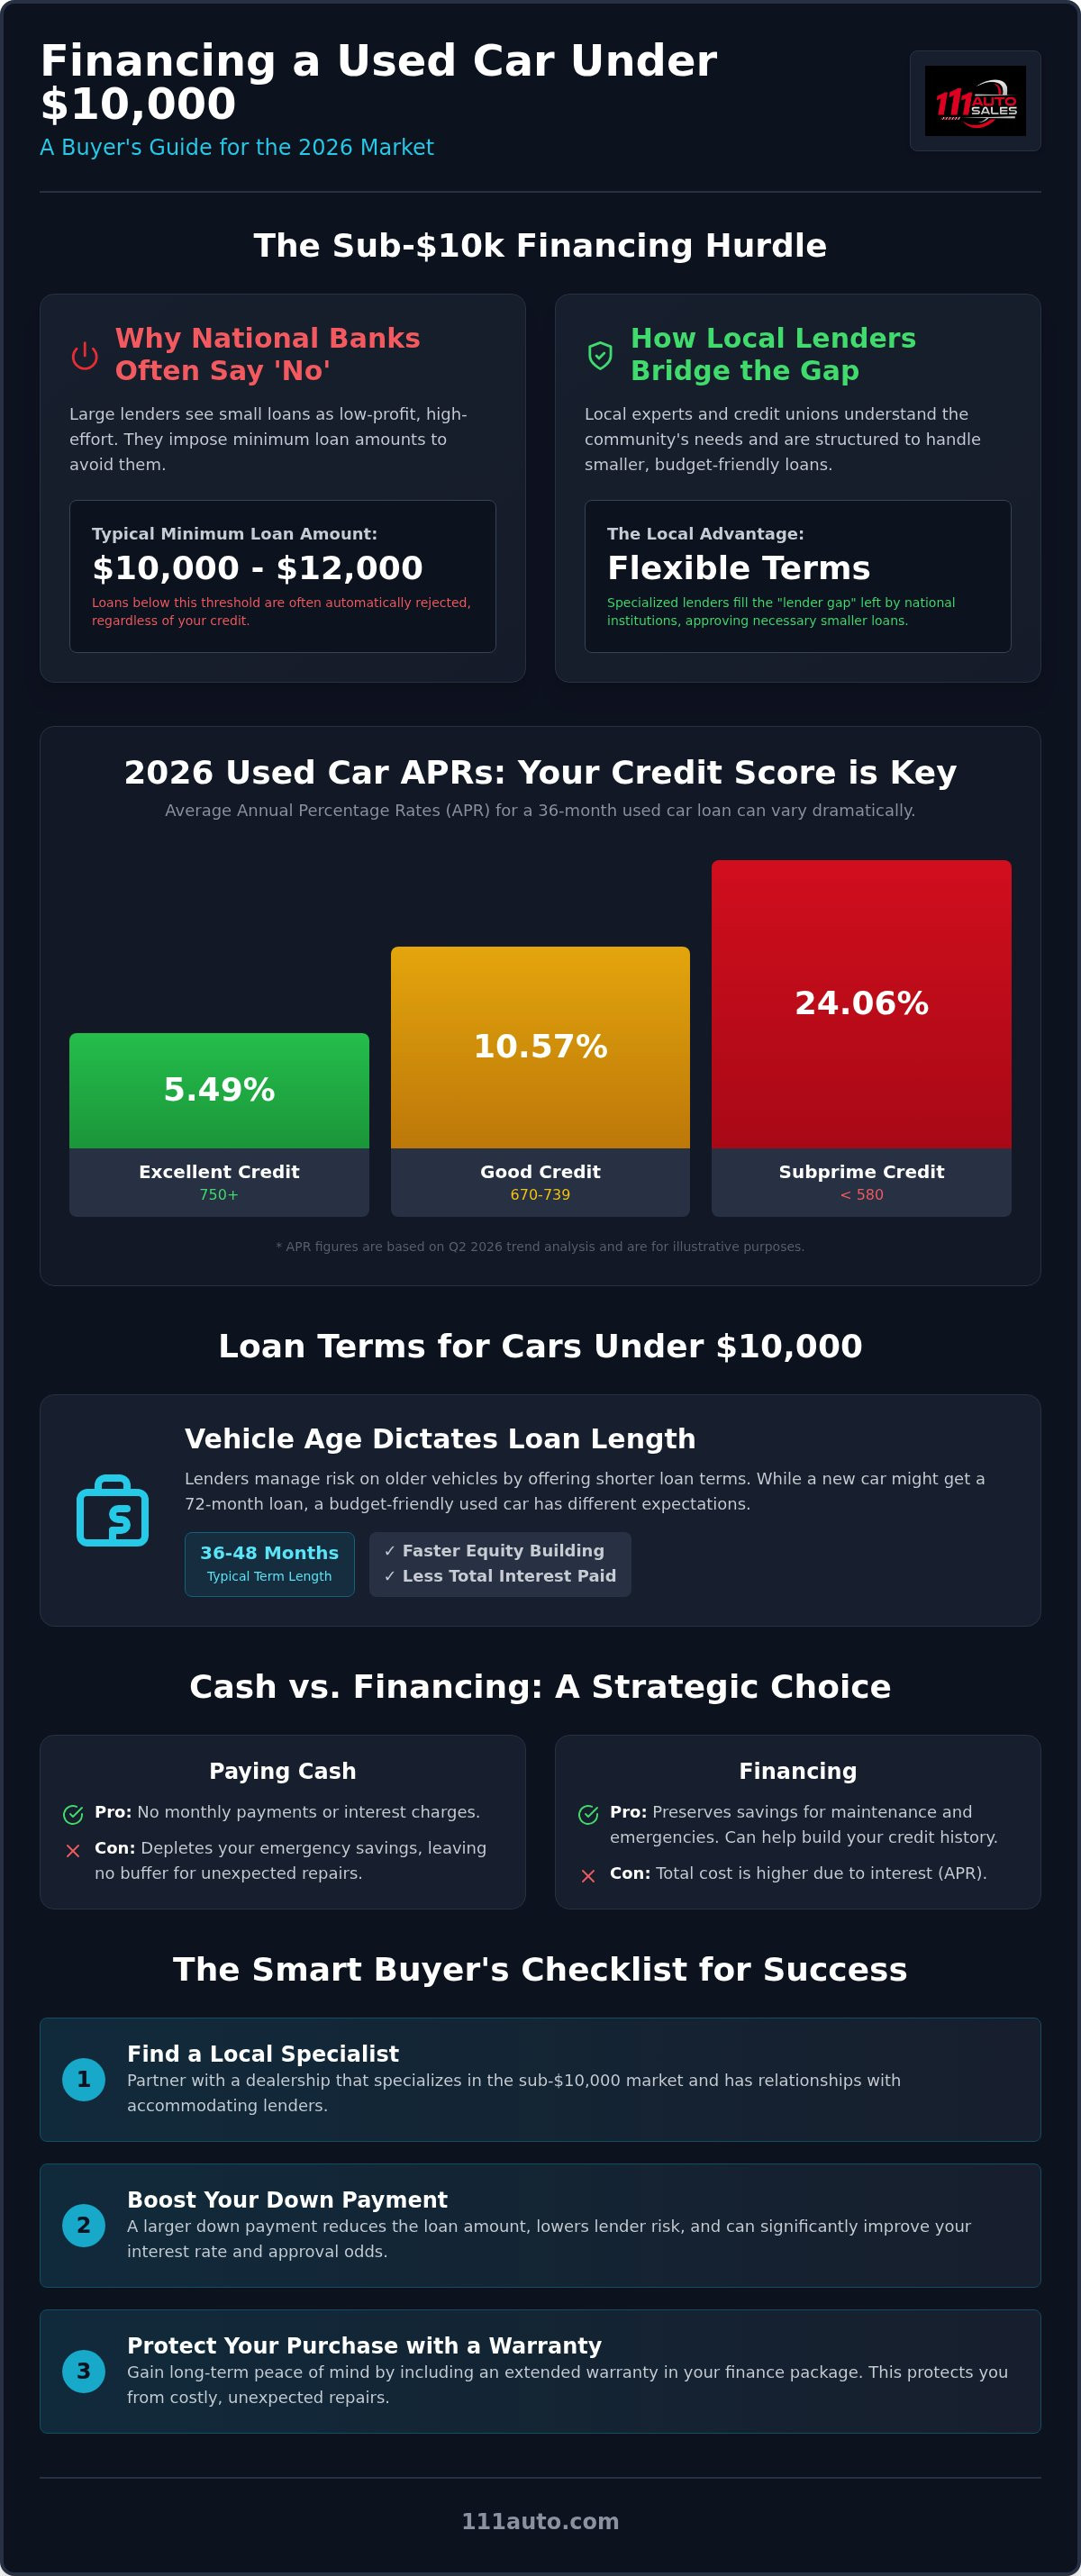
Major financial institutions often set a floor for auto loans, typically between $10,000 and $12,000. They do this because small loans generate less interest income relative to the work required to maintain them. This creates a significant problem for buyers who have a healthy down payment. If you find a reliable vehicle for $9,000 and have $2,000 to put down, your loan amount drops to $7,000. A big bank might reject this application purely because the amount is too low for their system.
This hurdle often forces buyers to reconsider their down payment strategy. You might need to keep more cash in your pocket to ensure the loan stays above a lender's minimum threshold. Alternatively, you can look toward independent dealerships and credit unions. These organizations are more likely to offer flexible small-dollar products that cater to the Pontoon Beach community's actual needs rather than arbitrary corporate minimums.
Vehicle Age vs. Loan Terms
In 2026, the age and mileage of a vehicle play a decisive role in loan eligibility. Lenders view older, high-mileage vehicles as higher risks because the collateral value is lower. To manage this risk, they often restrict the length of the loan. While a new SUV might qualify for a 72 or 84-month term, a car under $10,000 will likely be limited to 36 or 48 months. Consider these factors when planning your budget:
- Equity Building: Shorter terms help you build equity faster, which is vital for older vehicles.
- Loan Duration: Lenders want to ensure the car outlasts the loan term.
- Monthly Balance: A shorter term means a slightly higher monthly payment, but you'll pay significantly less in total interest.
Success in financing a used car under $10000 Pontoon Beach depends on the dealership's network. Establishments like 111 Auto Sales LLC work with lenders who specifically understand this price bracket. These partners recognize that an affordable car is a necessity, not a luxury, and they offer terms that reflect the reality of the used car market.
Understanding Used Car Finance Rates in 2026
Interest rates in 2026 aren't just a single number. They're a reflection of risk. When you're financing a used car under $10000 Pontoon Beach, lenders look at a combination of your personal financial health and the asset you're buying. In the Metro East area, current trends show that rates for used vehicles are stabilizing, but they remain highly sensitive to your credit profile and the loan-to-value ratio. Annual Percentage Rate (APR) represents the total yearly cost of borrowing money, including both interest and lender fees, expressed as a percentage.
A larger down payment is your most effective tool for lowering these rates. By putting more money down, you reduce the lender's exposure. This often moves you into a lower risk category, potentially shaving percentage points off your APR. Similarly, your debt-to-income (DTI) ratio matters. Lenders want to see that your total monthly debt payments, including the new car loan, don't exceed a specific portion of your gross monthly income. Keeping this ratio low increases your chances of approval for budget-friendly vehicles. You can get a good deal on a car by managing these variables before you ever step onto a lot.
Credit Score Tiers and Their Impact
Your credit score is the primary driver of your interest rate. In August 2026, borrowers with excellent credit (750+) can see rates as low as 5.49% for a 36-month term. Those in the "good" credit tier (670-739) averaged around 10.57% APR according to Q2 data. Subprime borrowers with scores under 580 might face averages closer to 24.06%. It's vital to check your score through a reputable service before visiting a dealership in Pontoon Beach. Knowing your tier allows you to walk into a negotiation with realistic expectations and a firm grasp of your buying power.
The Role of the Vehicle's Value
Lenders don't just guess what a car is worth. They use industry standards like J.D. Power or Black Book to determine the "book value" of a vehicle. If you try to finance a car for significantly more than its book value, a practice known as over-financing, your interest rate will climb. This is because the lender has no way to recover their money if the car is totaled or repossessed. To avoid this, consider seeking used car loan pre-approval in Pontoon Beach to lock in your rates based on verified valuations. This transparency ensures you aren't paying a premium for the convenience of the loan. If you're ready to see how these rates apply to our inventory, you can browse our current selection of pre-owned sedans and SUVs to find a match for your budget.
Cash vs. Financing: Which is Better for a $10,000 Budget?
Deciding whether to pay cash or take out a loan for a budget vehicle often comes down to your personal liquidity needs. While paying cash eliminates interest costs, it also drains your liquid savings in a single transaction. For many residents, financing a used car under $10000 Pontoon Beach is a strategic move to maintain a financial safety net. If you spend your entire $10,000 savings on a car, you have zero reserves for life's unexpected turns. Financing allows you to keep that capital working for you elsewhere while you pay for the vehicle in manageable increments.
A well-managed auto loan also serves as a powerful tool for credit enhancement. Consistent, on-time payments on a small-dollar loan demonstrate reliability to future lenders. This can lead to better rates on larger future purchases like a home or a newer truck. However, cash makes more sense if you're in a high-interest tier where the APR exceeds the potential return on your savings. You should consult the FTC guide on used car financing to understand how different payment structures impact your legal protections and total cost.
Pros and Cons of Financing a Budget Car
Financing isn't just about spending money you don't have; it's about cash flow management. Consider these trade-offs before making your choice:
- Pro: You preserve liquid savings for emergencies, medical bills, or home repairs.
- Pro: You can often afford a slightly newer model with better safety features and lower mileage.
- Con: You'll pay interest over the life of the loan, increasing the vehicle's total cost.
The 'Maintenance Reserve' Strategy
Smart buyers never spend their last dollar on the car's sticker price. Every used vehicle, regardless of its initial quality, will eventually require maintenance. If you have $10,000, a common strategy involves financing $7,000 of the purchase and keeping $3,000 in a dedicated repair fund. This "maintenance reserve" ensures that a $500 alternator replacement doesn't become a financial crisis. You can use our car loan calculator to test different cash and finance splits to see how they impact your monthly bottom line. By balancing your down payment with your financing needs, you secure both a reliable vehicle and financial peace of mind.
How to Secure Financing in the Pontoon Beach Area
When you're financing a used car under $10000 Pontoon Beach, you need a systematic approach to ensure your application is processed quickly. Securing a loan for a budget vehicle requires moving through specific steps that satisfy both state regulations and lender requirements. Start by gathering your local residency and income documentation. Lenders in the Metro East area typically require your two most recent pay stubs and a utility bill to verify your address. Once your paperwork is ready, research the inventory at local dealerships like 111 Auto Sales. Focusing on local specialists ensures you're looking at vehicles that already meet the small-dollar loan criteria discussed earlier.
Local Requirements for Metro East Buyers
Illinois has specific documentation standards for title and registration that you must meet at the time of purchase. You'll need a valid Illinois driver's license and proof of auto insurance that meets state minimums. Local lenders prefer seeing steady employment within the St. Louis or Metro East area because it suggests a stable commute and a reliable income stream. If you're a regular commuter, finding used sedan financing in Pontoon Beach is often a more straightforward process when you can prove your income is consistent with local industry standards.
Next, get a professional trade-in appraisal for your current vehicle. Even an older car can significantly reduce the total amount you need to borrow. Finally, review your loan agreement for hidden fees or prepayment penalties. Some lenders charge a fee if you pay off the car early, while others might include "add-ons" that you didn't request. It's better to identify these details before you sign the final contract.
Navigating the Trade-In Process
Your current car acts as a built-in down payment that lowers your loan-to-value ratio. In Illinois, the value of your trade-in vehicle can be deducted from the taxable amount of the new purchase. This tax credit can save you a significant amount on the state's 6.25% sales tax rate. Local dealers often provide better trade-in values than national car-buying sites because they understand the specific demand for certain models in Pontoon Beach. To get the maximum value, clean the interior and gather any maintenance records you have. A well-documented service history proves the car was cared for, which directly increases the dealer's offer.
If you're ready to start the appraisal process and see your options, browse our pre-owned trucks and SUVs to see what fits your trade-in budget.
Affordable Financing Solutions at 111 Auto Sales
At 111 Auto Sales, we believe that reliable transportation is a fundamental necessity. Our approach to financing a used car under $10000 Pontoon Beach is built on the reality that a lower price point shouldn't result in a lower standard of service. We specifically curate our inventory to meet the needs of budget-conscious Metro East drivers. These are individuals who need a vehicle capable of handling daily commutes across the McKinley or Chain of Rocks bridges without the constant fear of a breakdown. By focusing on cars, trucks, and SUVs that fall within this price bracket, we ensure our customers find options that are both affordable and mechanically sound.
The 111 Auto Sales Financing Advantage
Our team provides direct access to a network of local lenders who specialize in the Illinois used car market. These partners understand the value of small-dollar loans. They don't impose the arbitrary $10,000 or $12,000 floors common at national banks. We prioritize transparency in every transaction. You won't find hidden surprises or unexplained fees when you review your contract. Instead, you'll see clear terms tailored to your specific credit profile. For those looking for larger family vehicles, you can consult our used SUV financing resource guide to see how we structure deals for high-demand models. We focus on the facts of your financial situation rather than just a computer-generated score.
Protecting Your Investment
An extended warranty is a critical component of a successful budget car purchase. When a vehicle is priced under $10,000, it often has higher mileage, which naturally increases the risk of mechanical wear. We help you choose a protection plan that fits your budget. We can often bundle the cost directly into your monthly payment. This strategy is essential because a warranty prevents you from "double-paying" for a car, which happens when you're stuck making a monthly loan payment on a vehicle that is sitting in a repair shop because you can't afford the fix.
Our inventory undergoes a rigorous selection process to ensure every sedan, van, or truck on our lot is ready for the road. We don't just sell "cheap" cars. We provide verified transportation solutions that respect your financial boundaries. By combining specialized lending with optional warranty protection, we offer a level of security that national aggregators cannot match. If you're ready to find a vehicle that fits your life, visit our lot in Pontoon Beach to see our current selection of pre-owned vans and trucks.
Take the Wheel with Confidence in Pontoon Beach
Securing reliable transportation doesn't require a six-figure income or a massive loan. By understanding the 2026 lending landscape, you can navigate the "lender gap" and find small-dollar financing that fits your budget. Remember that preserving your liquid savings through a maintenance reserve is often safer than spending your last dollar on a cash purchase. Local expertise is your greatest asset when financing a used car under $10000 Pontoon Beach, as it ensures you benefit from Illinois-specific tax credits and transparent contract terms.
At 111 Auto Sales, we've built a specialized budget-friendly lender network specifically for the Metro East community. We proudly serve Pontoon Beach and Granite City with a curated inventory where extended warranties are available on all vehicles. This combination of financial flexibility and mechanical protection gives you the peace of mind you deserve. Don't let national banking hurdles stand in your way. Browse our inventory of reliable used cars under $10,000 and apply for financing today! We're ready to help you find a vehicle that works for your life and your wallet.
Frequently Asked Questions
Can I get a car loan for exactly $5,000 or $7,000?
Yes, you can secure a loan for $5,000 or $7,000, but you won't typically find these through national banks. Major institutions often set a $10,000 floor to maintain profit margins. To find these small-dollar amounts, you'll need to work with independent dealerships or local credit unions that specialize in budget-friendly financing. These lenders understand the Metro East market and offer products specifically designed for lower purchase prices.
What is a good interest rate for a used car under $10,000 in 2026?
A good interest rate in 2026 depends entirely on your credit tier. For buyers with excellent credit (750+), a rate near 5.49% is considered competitive. Those in the good credit range (670-739) should expect averages around 10.57%. If your score is lower, rates can rise significantly. Locking in a rate below the national average for your specific credit tier is the primary goal for any buyer.
Do I need a down payment to finance a budget used car?
You don't always need a down payment, but providing one is highly beneficial. Putting 10% to 20% down reduces the lender's risk and lowers your monthly obligation. In the sub-$10,000 market, even a small down payment of $1,000 can move you into a better interest rate tier. It also helps you stay "above water" on the loan, ensuring you don't owe more than the car's market value.
Is it harder to finance a car from a private seller than a dealership?
Yes, financing a private sale is significantly more difficult than working with a dealership. Banks view private transactions as higher risk because there is no professional inspection or verified title processing. Most lenders prefer the security of a dealership that handles the Illinois state paperwork and ensures the vehicle meets specific safety standards. Dealerships also have established relationships with multiple lenders, increasing your chances of approval.
How does my credit score affect my ability to buy a car under $10k?
Your credit score is the single most important factor when financing a used car under $10000 Pontoon Beach. It determines your APR, which directly impacts your total cost of ownership. A higher score unlocks lower rates and more flexible terms, while a lower score may require a larger down payment. Checking your score before you shop allows you to understand which lender tiers you qualify for in the current 2026 market.
What happens if the car I finance needs a major repair?
If a financed car needs a major repair, you are still legally obligated to continue making your loan payments. This is a common anxiety for budget buyers. To protect yourself, it's wise to bundle an extended warranty into your financing or maintain a dedicated repair fund. These safety nets ensure that a mechanical failure doesn't lead to a financial crisis or a missed payment that could damage your credit score.
Can I finance a car that is more than 10 years old?
Yes, you can finance vehicles older than 10 years, though the loan terms will be shorter. Most lenders limit these loans to 36 or 48 months to ensure the debt is settled while the car is still operational. Interest rates may be slightly higher for older models to offset the depreciation risk. It's important to choose a vehicle with a documented service history to satisfy the lender's valuation requirements.
Are there specialized loans for first-time buyers in Pontoon Beach?
Yes, there are specialized programs for first-time buyers in the Pontoon Beach area. These loans are designed for individuals with "thin" credit files who have steady income but limited borrowing history. Local dealerships often partner with lenders who look at your employment stability and residency rather than just a credit score. These programs are an excellent way to secure reliable transportation while building a positive credit profile for the future.


