
What if you could walk onto a dealership lot already knowing exactly what you can afford, without the fear of a loan rejection? For many drivers, the most stressful part of buying a vehicle isn't picking the model; it's the uncertainty of the finance office. Securing a used car loan pre-approval in Pontoon Beach transforms you from a hopeful shopper into a confident buyer. It gives you the leverage to negotiate because your budget is already defined before you even see a price tag.
You likely worry about whether a monthly payment will fit your budget or if high interest rates will make a reliable truck or SUV too expensive. It's a valid concern when average APRs in Illinois can range from 8.03% for excellent credit to over 24% for those with poor credit. This guide will help you master the pre-approval process and explain how to use a car loan calculator to secure the best deal. You'll learn how to clarify your buying power, avoid hidden fees, and ensure a faster, more transparent path to your next vehicle.
Key Takeaways
- Learn the critical difference between a soft-pull pre-qualification and a hard-pull pre-approval to protect your credit score.
- Use a car loan calculator to factor in Illinois sales tax and registration fees for a realistic monthly budget.
- Securing a used car loan pre-approval in Pontoon Beach gives you significant negotiating power and speeds up the dealership process.
- Prepare for your application by gathering income verification and correcting credit report errors to secure the best possible interest rates.
- Discover how to align your pre-approved financing with reliable, affordable inventory like SUVs and trucks under $10,000.
What is Used Car Loan Pre-Approval and Why Does it Matter?
Many car buyers in Illinois start their journey by walking onto a lot, but the most successful ones begin at home. What is pre-approval? Simply put, it's a conditional commitment from a lender that tells you exactly how much they're willing to lend you based on your financial history. Obtaining a used car loan pre-approval in Pontoon Beach moves you to the front of the line. It signals to dealers that you're a serious, qualified buyer rather than just a window shopper.
When you have a pre-approval letter in hand, you essentially become a cash buyer. You don't have to wait for a dealership to run your credit through multiple lenders to see what sticks. You already know your interest rate, your maximum loan amount, and your expected monthly payment. This transparency allows you to focus entirely on the vehicle's quality and price. It's the most effective way to remove the mystery from the finance office and keep control of the transaction.
Pre-Approval vs. Pre-Qualification
It's easy to confuse these two terms, but they carry very different weights in the automotive industry. A pre-qualification is often based on a soft pull of your credit. This provides a ballpark estimate of what you might qualify for without affecting your credit score. It's a helpful starting point when you're just beginning to explore your options.
A formal used car loan pre-approval in Pontoon Beach involves a hard pull and a thorough review of your income and debts. It carries much more weight with a dealer because it represents a verified offer. You should use pre-qualification to narrow down your general price range and save the formal pre-approval for when you're ready to buy within the next 30 to 60 days. This strategy protects your credit score while ensuring you have a firm offer when you find the right vehicle.
The Benefits of Knowing Your Limit Early
Shopping without a confirmed budget often leads to frustration. You might fall in love with a premium SUV only to find out the monthly payments are double what you can afford. Knowing your limit early eliminates this heartbreak. It allows you to filter your search to reliable trucks, SUVs, or sedans that fit your actual financial capacity. With average APRs in Illinois ranging from 8.03% for excellent credit to over 24% for poor credit, knowing where you stand is essential for realistic budgeting.
Securing your financing beforehand also strengthens your negotiation position. In a competitive market, being able to close a deal quickly is a significant advantage. You can skip vehicles that are outside your range and focus on getting the best value for your money. This saves hours of dealership time and ensures the final paperwork is a simple formality rather than a high-stakes gamble.
How to Use a Car Loan Calculator for Better Budgeting
A digital calculator acts as your strategic planning tool before you commit to a purchase. It allows you to visualize how different loan structures impact your bank account. While a used car loan pre-approval in Pontoon Beach gives you a maximum ceiling, the calculator helps you find your "comfort zone" for monthly expenses. To get the most accurate results, you should follow a structured approach to inputting your data.
- Step 1: Input the total vehicle price. Don't just enter the sticker price; include estimated taxes and dealer fees to see the true cost.
- Step 2: Factor in your down payment or trade-in value. Reducing the principal amount immediately lowers the interest you'll pay over the life of the loan.
- Step 3: Select a realistic loan term. Most used car loans run between 36 and 72 months. Shorter terms save money on interest, while longer terms lower the monthly burden.
- Step 4: Enter your estimated interest rate. Use the rates provided in your pre-approval letter or current Illinois averages based on your credit tier.
Adjusting Variables for Your Ideal Payment
Small changes in your loan structure can lead to significant long-term savings. Increasing your down payment by even $1,000 can slash your interest costs and provide immediate equity in the vehicle. You must also weigh the trade-off between term length and total interest; a longer loan might look attractive monthly, but you'll pay more for the car in the end. A 1% interest rate change on a $10,000 loan over 60 months shifts your monthly payment by approximately $5, which adds up to $300 over the life of the loan. Following the proper steps for buying a used car ensures you don't overlook these mathematical realities.
Hidden Costs to Include in Your Calculation
Many buyers forget that the purchase price isn't the final number. In Illinois, you must account for a statewide sales tax of 6.25%, plus any applicable local taxes. Additionally, title and registration fees in our state currently total $316, consisting of a $165 title fee and a $151 registration fee. You should also consider the cost of an extended warranty, especially for older models, to protect against unexpected repairs. Using a calculator is particularly helpful when comparing used SUV financing Pontoon Beach options, as larger vehicles often have different insurance and maintenance profiles. Once you have these numbers, you can confidently browse the affordable inventory under $10,000 available today.
Comparing Local Financing Options in the Pontoon Beach Area
Finding the right source for your loan is just as important as finding the right vehicle. In the St. Louis metro area, you have several paths to secure a used car loan pre-approval in Pontoon Beach. Each option has distinct advantages depending on your credit history and the age of the vehicle you want to buy. Understanding these differences helps you avoid predatory lending and ensures you get a rate that fits your financial goals.
Local credit unions, such as Illinois Educators CU, often provide some of the most competitive rates in Madison County. For instance, rates for 2019 to 2022 models have been seen around 7.24% APR for qualified members as of August 2026. National banks offer convenience and robust mobile apps, but they can be more rigid with their lending criteria. One major factor all lenders consider is your Debt-to-Income (DTI) ratio. Most prefer a DTI below 36%, meaning your total monthly debt payments shouldn't exceed 36% of your gross monthly income. If your ratio is higher, you might find more success with local lenders who can look at your full financial picture.
It's also vital to distinguish between traditional auto loans and "Buy Here, Pay Here" models. Traditional loans involve a third-party lender, like a bank or credit union, which helps build your credit score through regular reporting. "Buy Here, Pay Here" lots act as the lender themselves. While they offer easier approval for those with poor credit, they often charge significantly higher interest rates and may not help improve your credit history. Stick to traditional financing whenever possible to ensure long-term financial health.
Credit Unions and Banks in Madison County
Lenders in the Granite City and Pontoon Beach area typically look for stability in your employment and residency. When you apply for a used car loan pre-approval in Pontoon Beach, expect a turnaround time of 24 to 48 hours for a formal letter. Many local institutions also offer special programs for first-time buyers or residents looking to rebuild their credit. These programs often include educational resources to help you manage your first major auto purchase responsibly.
The Advantage of Dealer-Assisted Financing
While banks are excellent, they often have strict limits on vehicle age or mileage. This is where dealer-assisted financing becomes a powerful tool. Dealers work with a diverse network of lenders, including those who specialize in older, more affordable models under $10,000. They can often find a middle ground that a single bank cannot offer. This process also streamlines your paperwork; you can often complete the application and drive away in your new vehicle the same day. It's a highly efficient way to secure used sedan financing Pontoon Beach while ensuring the lender is a reputable institution. Choosing a dealer with a strong local reputation ensures the financing terms are transparent and the vehicle has been properly vetted.
4 Steps to Secure Your Pre-Approval Before You Shop
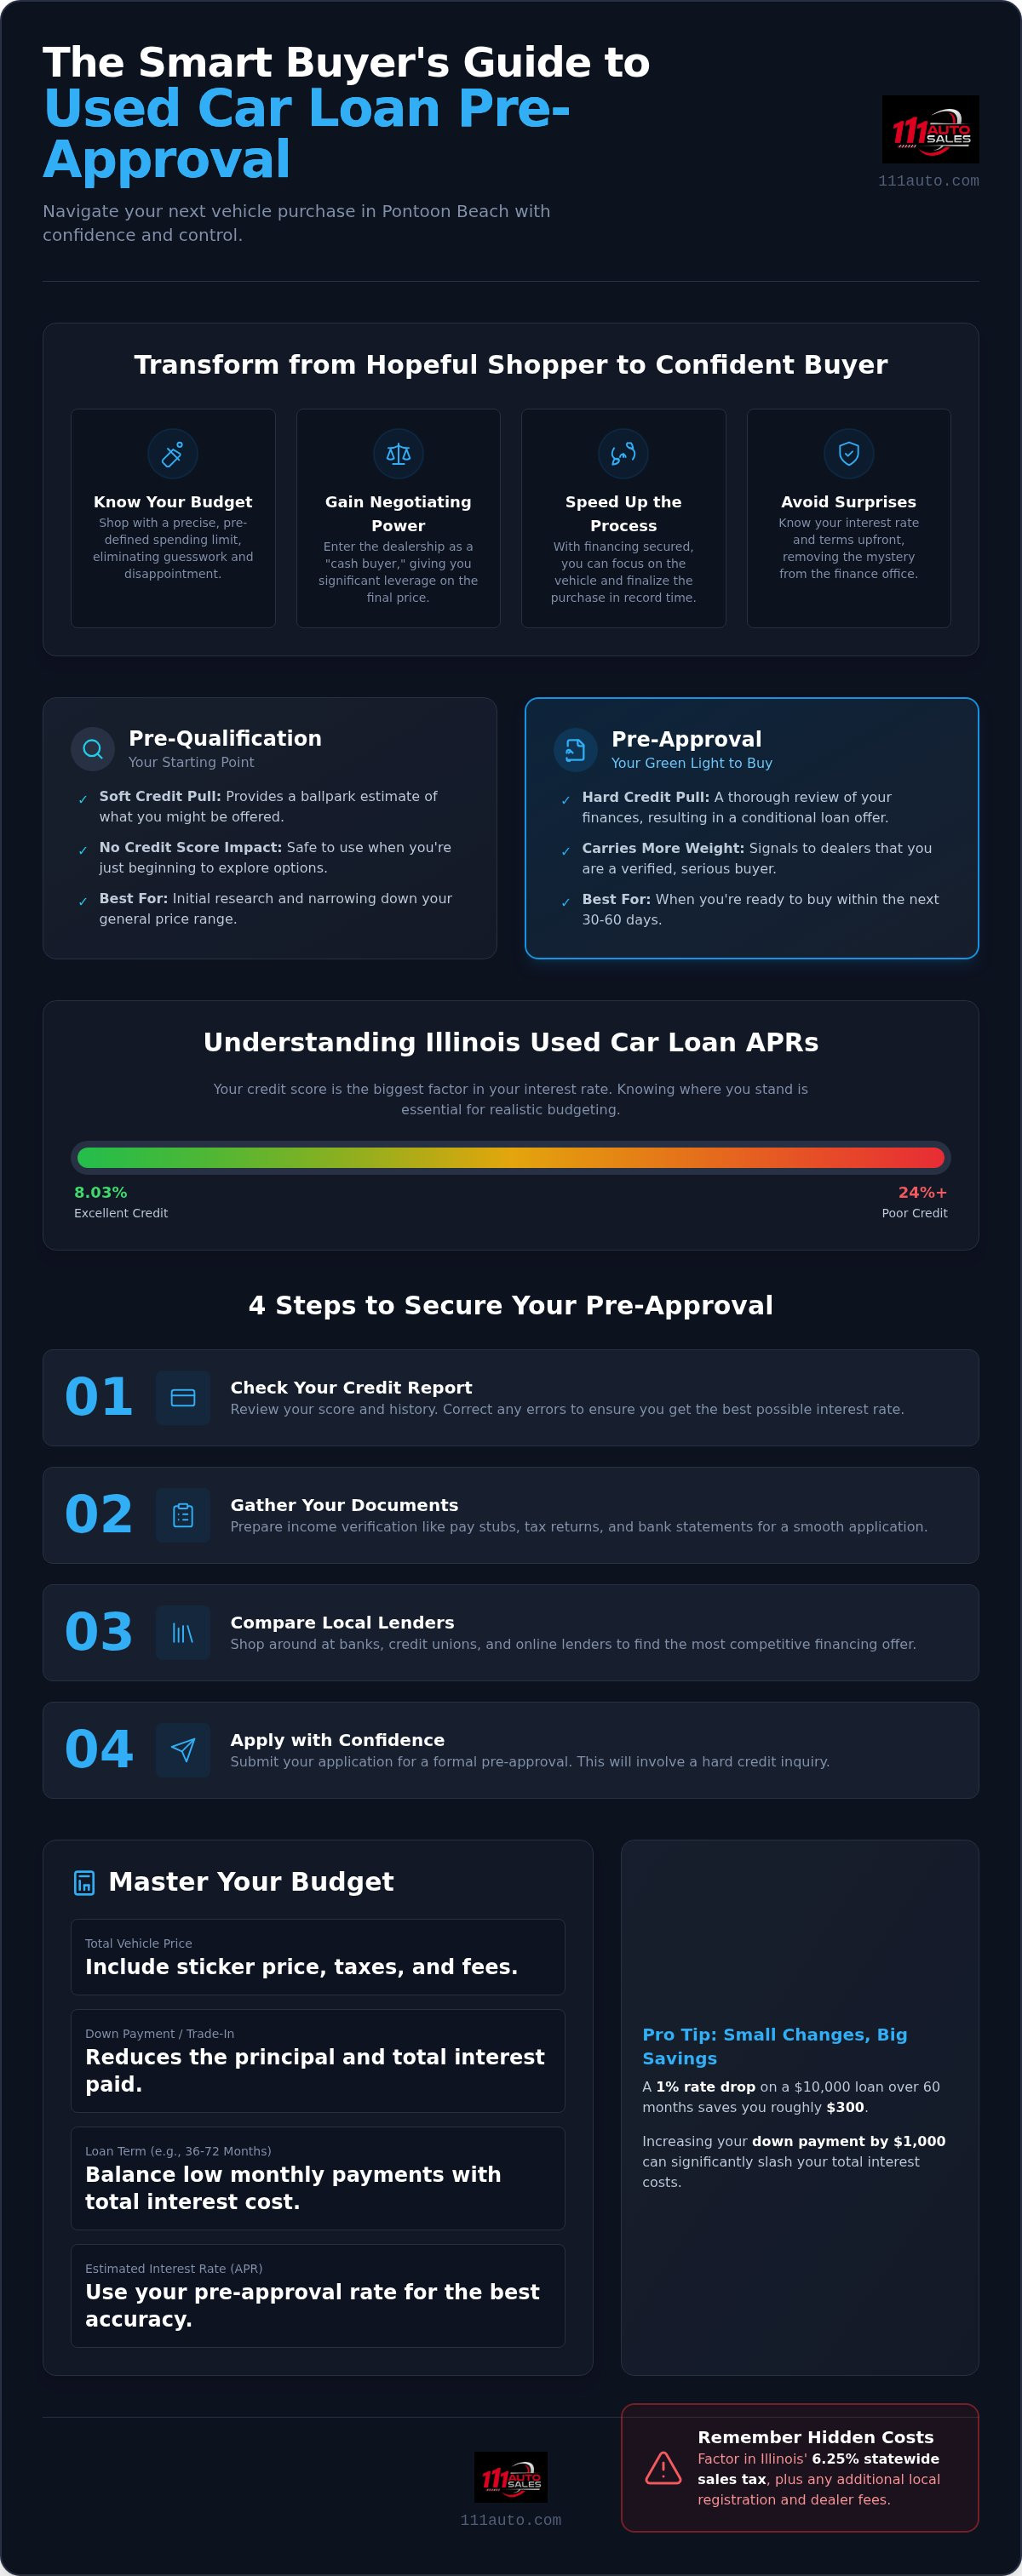
Securing a used car loan pre-approval in Pontoon Beach is a methodical process that requires preparation. If you walk into a dealership with your financing already arranged, you eliminate the pressure of on-the-spot credit decisions. This preparation allows you to focus on the vehicle's condition and history rather than worrying about whether the bank will say yes. Follow these four steps to ensure your application is as strong as possible.
- Check your credit report for errors. A single mistake on your report can drop you into a higher interest rate tier. Dispute any inaccuracies regarding late payments or open accounts before you apply.
- Gather your income verification. Lenders need to see a stable ability to repay the loan. Have your two most recent pay stubs or last two years of tax returns ready for review.
- Finalize your budget. Use the car loan calculator mentioned earlier to find a monthly payment that leaves room for insurance and maintenance.
- Submit your applications strategically. Apply to one to three lenders within a short window. This ensures you can compare offers without damaging your credit score through multiple independent inquiries.
Preparing Your Financial Documentation
Lenders in Madison County require specific proof to verify your identity and financial standing. For residents in the Pontoon Beach area, a utility bill or a signed lease agreement usually suffices as proof of residence. If you're self-employed, documentation is even more critical. You'll need to provide at least three to six months of bank statements to show consistent monthly deposits. Having your current auto insurance information ready is also a requirement, as lenders won't finalize a loan without proof that the collateral is protected. Proper documentation speeds up the verification process, often resulting in a faster approval letter.
Managing the Credit Inquiry Impact
Many buyers fear that applying for a loan will ruin their credit score. However, modern credit scoring models recognize "rate shopping." If you submit all your applications for a used car loan pre-approval in Pontoon Beach within a 14-day window, they're typically treated as a single hard inquiry. This protects your score while allowing you to find the most competitive APR. It's also vital to avoid taking on new debt, such as a new credit card or furniture loan, during this phase. Maintaining a stable credit profile makes it much easier to secure financing for high-demand vehicles, such as used trucks under 10000 Pontoon Beach. Once you have your letter, you can browse our reliable inventory with complete confidence.
Finalizing Your Purchase at 111 Auto Sales LLC
Once you hold a used car loan pre-approval in Pontoon Beach, the dealership experience changes completely. You're no longer wondering if you can afford a vehicle; you're simply choosing the one that best meets your needs. At 111 Auto Sales LLC, we specialize in making this transition as smooth as possible. We focus on reliable inventory, particularly trucks and SUVs under $10,000, ensuring your pre-approved amount goes further and provides real value.
Our team understands the local market and the specific requirements of Madison County lenders. When you bring your pre-approval to us, we don't just hand you a set of keys. We assist with the final lender verification, ensuring all paperwork matches the lender's criteria perfectly. This professional oversight prevents last-minute delays. It ensures the interest rate and terms you were promised are exactly what you receive in the final contract before you drive home to Granite City or Collinsville.
From Pre-Approval to the Driver's Seat
The process begins when you present your pre-approval letter to our sales team. This document serves as our roadmap. It allows us to bypass vehicles that don't fit your financial plan and head straight to the sedans, vans, or trucks that do. You can then spend your time test driving vehicles with the peace of mind that the math is already settled. Because the financing is largely pre-arranged, the transition from browsing our lot to signing the final papers is remarkably fast. Many of our customers find they can complete the entire purchase in a fraction of the time it takes at larger, less focused dealerships.
Protecting Your Investment Post-Purchase
A smart financial plan doesn't end with the loan signature. For budget-conscious buyers, an unexpected repair can be a significant financial setback. This is why we emphasize the role of extended warranties in our closing process. When finalizing your deal, you can often include the cost of a warranty within your pre-approved loan amount. This ensures your monthly payment covers both the vehicle and a safety net for the future. Protecting your investment this way provides long-term stability and keeps your transportation reliable for years to come. Explore our pre-owned SUVs Pontoon Beach and apply for financing today to secure a dependable vehicle that fits your life.
Step Into Your Next Vehicle With Confidence
Securing a used car loan pre-approval in Pontoon Beach is the most effective way to simplify your vehicle search. By defining your buying power before you visit the lot, you transform a stressful process into a structured, transparent transaction. You now understand how to use a calculator to account for Illinois sales tax and registration fees, ensuring your monthly budget remains sustainable. This preparation allows you to focus on what matters most: finding a reliable vehicle that fits your lifestyle.
At 111 Auto Sales LLC, we specialize in providing reliable vehicles under $10,000. As local experts in Pontoon Beach financing, we're here to help you match your pre-approval to the right truck, SUV, or sedan. We also offer extended warranty options to protect your investment for the long term. Take the final step toward a stress-free purchase today and see how easy the process can be when you have the right partner.
Get Pre-Approved and Browse Our Used Inventory Under $10,000
We look forward to helping you drive home in a vehicle that perfectly aligns with your financial goals and provides the reliability you deserve.
Frequently Asked Questions
How long does a used car loan pre-approval last in Illinois?
A pre-approval is typically valid for 30 to 60 days. This window gives you enough time to shop for a vehicle without rushing your decision. If you don't finalize a purchase within this timeframe, the offer expires and you'll need to re-apply. Keep in mind that your credit score and financial situation must remain stable during this period to keep the offer active.
Can I get pre-approved for a used car loan with bad credit?
Yes, you can secure a used car loan pre-approval in Pontoon Beach even with a lower credit score. Lenders specializing in subprime financing often look at your income stability and debt-to-income ratio rather than just a number. While your interest rate will likely be higher, often between 21% and 24% for scores under 669, having a pre-approval helps you understand exactly what's affordable.
Does a car loan calculator include sales tax and title fees?
Most basic calculators only account for the vehicle price, interest rate, and term. You must manually add the 6.25% Illinois state sales tax and any local taxes to get an accurate monthly payment. In Pontoon Beach, you should also factor in $316 for title and registration fees. Including these costs ensures your budget remains realistic and prevents surprises during the final signing.
What is a good interest rate for a used car loan in 2026?
As of August 2026, a good interest rate depends on your credit tier. Buyers with excellent credit see average APRs around 8.03%, while some local credit unions offer 7.24% for 2019 to 2022 models. If your score is between 740 and 799, you might find rates near 7.81%. These figures represent the current market standard for reliable used vehicles in the St. Louis area.
Will getting a pre-approval hurt my credit score significantly?
A pre-approval requires a hard credit pull, which typically results in a temporary dip of five points or less. This is a minor impact compared to the long-term benefit of securing a lower interest rate. If you apply to multiple lenders within a 14-day window, credit bureaus treat these as a single inquiry. This rate shopping protection allows you to compare offers without multiple penalties.
Can I use my pre-approval at any used car dealership in Pontoon Beach?
Most pre-approvals are open, meaning you can use them at any licensed dealership that meets the lender's requirements. However, some lenders may have restrictions on the age or mileage of the vehicle you choose. It's best to verify these terms with your bank or credit union before visiting a lot. This ensures your used car loan pre-approval in Pontoon Beach is ready to go when you find the right car.
What happens if the car I want is more than my pre-approved amount?
If the vehicle price exceeds your pre-approved limit, you'll need to cover the difference with a cash down payment. For example, if you're approved for $10,000 but the total cost is $11,000, you must provide the extra $1,000 upfront. Alternatively, you can look for a different vehicle that fits within your approved range. This is why using a calculator to set expectations early is so important.
Do I need a down payment if I am already pre-approved?
A down payment isn't always required by the lender, but it's highly recommended. Providing even 10% of the purchase price reduces the total amount you need to borrow, which lowers your monthly payments. It also decreases the total interest you'll pay over the life of the loan. A down payment creates immediate equity, protecting you if you need to sell or trade in the vehicle later.


