
Is it actually possible to drive away in a reliable vehicle when your budget is strictly four figures? Many drivers in the Metro East area assume that financing used cars under 10000 means settling for predatory interest rates or a vehicle that won't last the month. With the average age of cars on U.S. roads hitting a record 12.8 years in 2026, finding a balance between an affordable sticker price and a sustainable loan is more challenging than ever. You shouldn't have to choose between a manageable monthly payment and a car you can actually trust to get you to work.
We understand the anxiety that comes with high-mileage inventory and the uncertainty of credit approvals. This guide will show you how to master the financing process so you can secure a dependable sedan, SUV, or truck without overextending your bank account. We'll break down the latest 2026 lending trends, explain how to navigate credit hurdles, and help you calculate the true cost of ownership. By the end of this article, you'll have a clear roadmap to finding a budget-friendly vehicle that fits your lifestyle and your wallet. Our goal is to provide the stability and transparency you need to make an informed investment in your mobility.
Key Takeaways
- Learn why a $10,000 budget represents a strategic balance between reliability and affordability in the 2026 pre-owned market.
- Understand how the loan-to-value (LTV) ratio and vehicle age influence your approval odds when financing used cars under 10000.
- Discover the essential preparation steps for budgeting, including how to account for local tax, title, and license (TTL) fees.
- Gain insights into using strategic down payments to secure more manageable monthly terms regardless of your current credit score.
- Find out how local expertise in the Metro East area can help you navigate the specific challenges of the budget-friendly vehicle market.
The Value of Choosing Quality Used Vehicles Under $10,000
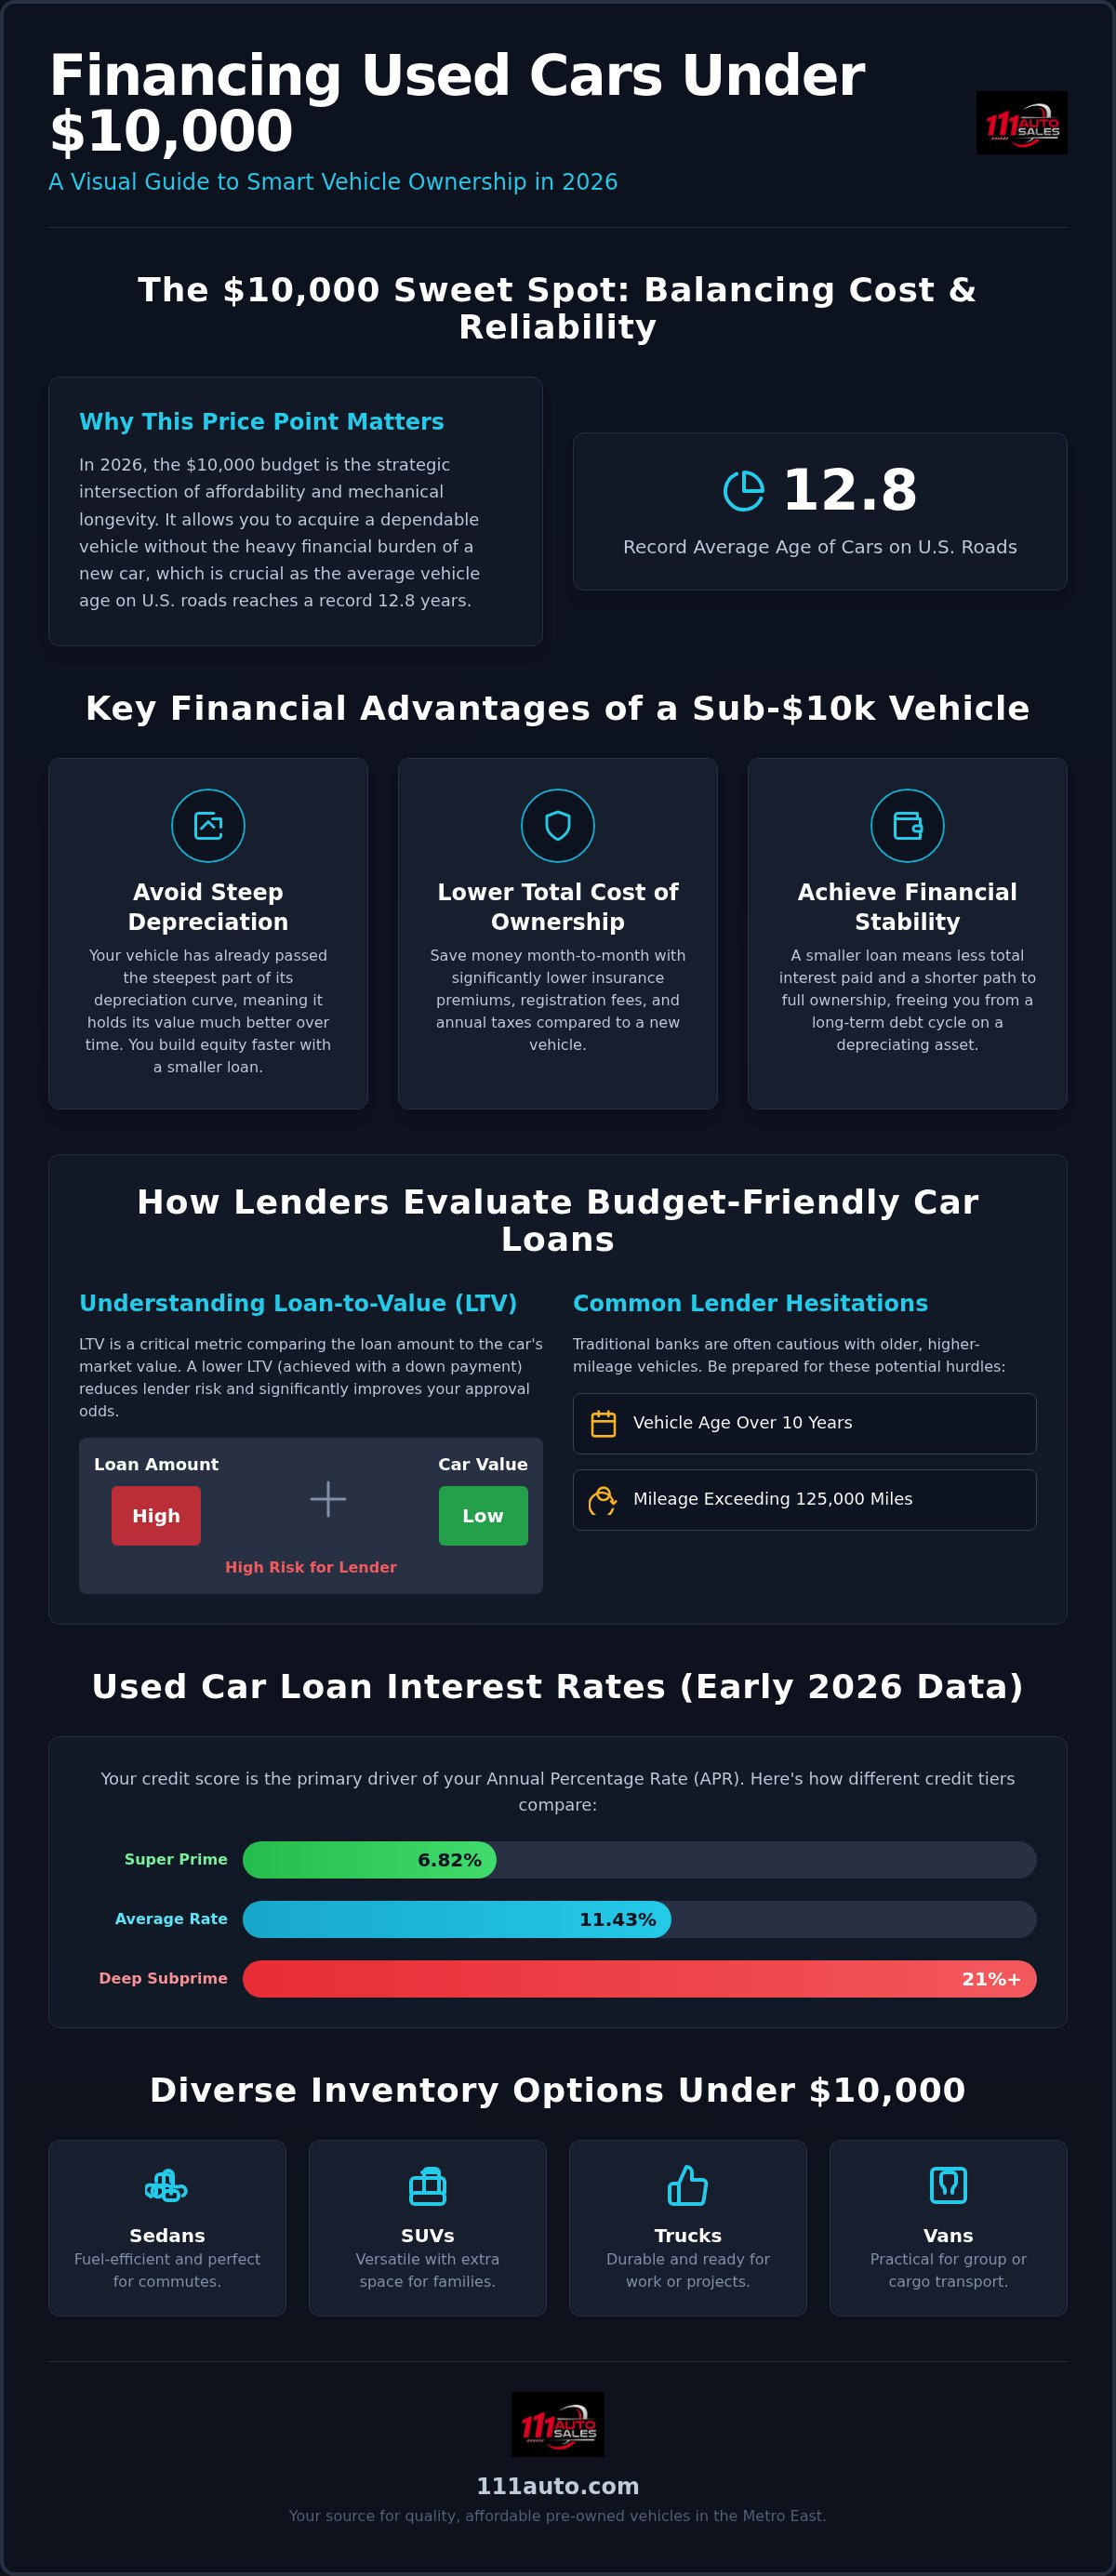
In 2026, the $10,000 price point represents a strategic threshold for budget-conscious buyers. It is the specific level where affordability and mechanical longevity intersect. While many associate "cheap" cars with neglected maintenance or hidden defects, the high-value pre-owned market at this price focuses on vehicles with proven track records. Choosing to focus on financing used cars under 10000 allows you to acquire a reliable daily commuter or a safe first car for a teenager without the heavy burden of a new vehicle's monthly payment.
The financial benefits extend far beyond the initial purchase price. Total cost of ownership is significantly lower because insurance premiums typically drop as a vehicle ages. Additionally, registration fees and annual taxes are often based on the car's current market value. By staying under the $10,000 mark, you reduce your recurring monthly expenses, leaving more room in your budget for routine maintenance and personal savings. This approach prioritizes functional transportation over the vanity of a late-model sticker.
Lower Depreciation and Financial Stability
A new vehicle can lose a massive portion of its value the moment it leaves the lot. By the time a car enters the sub-$10,000 price bracket, it has already navigated the steepest part of its depreciation curve. This means the vehicle retains its value much better during your ownership. If you decide to sell or trade it in three years, the price difference will be much smaller than it would be with a newer model.
Smaller loan amounts also lead to faster equity building. Understanding how car financing works is essential here. When you borrow less, you pay less in total interest over the life of the loan. This creates a sense of financial stability and peace of mind. You aren't trapped in a long-term debt cycle for an asset that is rapidly losing value. Instead, you are making a calculated investment in your mobility.
Diverse Inventory Options in the Metro East
The Metro East market provides a wide range of choices for those financing used cars under 10000. You aren't limited to one specific body style. Drivers can find a variety of used sedans for sale Pontoon Beach that offer excellent fuel economy for commutes to Granite City.
- Fuel-Efficient Sedans: Ideal for long highway drives and city parking.
- Versatile SUVs: Perfect for families needing extra cargo space for weekend trips to Collinsville.
- Work-Ready Trucks: Durable options for local tradespeople or DIY enthusiasts.
- Reliable Vans: Practical solutions for group transportation and local deliveries.
This diversity ensures that your vehicle matches your actual driving needs. Whether you are navigating neighborhood streets or local interstates, the sub-$10k market offers the flexibility to find a vehicle that is both practical and affordable.
How Financing Works for Budget-Friendly Pre-Owned Cars
Securing financing used cars under 10000 differs significantly from buying a late-model vehicle. Lenders classify these loans differently because the collateral, the car itself, is older and often carries higher mileage. Many traditional banks hesitate to finance vehicles over 10 years old or with more than 125,000 miles. It's why specialized lending structures are necessary for this market segment. A critical factor in your approval is the loan-to-value (LTV) ratio. This metric compares the total loan amount to the vehicle's actual market value. If the LTV is too high, lenders see increased risk. Keeping your loan amount close to the car's appraised worth improves your chances of a favorable response.
Understanding APR and Interest Rates
Lenders assess risk based on the likelihood of the vehicle reaching the end of its mechanical life before the loan is paid. As of early 2026, the average interest rate for a used car loan sits at 11.43%. However, your specific rate depends heavily on your credit tier. Super Prime borrowers might see rates around 6.82%, while those in the Deep Subprime category could face rates exceeding 21%. Following professional tips for buying a new or used car can help you prepare your finances before applying. Most sub-$10k loans utilize fixed rates. This ensures your monthly payment remains predictable throughout the life of the agreement. Lenders don't just look at credit scores; they also evaluate the specific age of the car. A 5-year-old car generally commands a lower rate than a 10-year-old model because it represents a more stable asset.
Loan Terms for Older Vehicles
The age of the vehicle directly dictates how long you can take to pay it off. While a new car might offer a 72-month term, budget-friendly vehicles usually require shorter windows, typically between 24 and 48 months. Shorter terms are actually a strategic advantage. You pay significantly less in total interest and build equity in the car much faster. This means you'll own the vehicle outright sooner, providing you with a debt-free asset. Balancing a manageable payment with a shorter duration is the key to long-term financial health. It prevents you from being "underwater" on a loan where you owe more than the car is worth. If you're ready to explore your options, you can browse our budget-friendly inventory to see what fits your needs.
Key Factors That Impact Your Sub-$10,000 Auto Loan
Lenders evaluate more than just the borrower when financing used cars under 10000. They look at the relationship between your financial health and the vehicle's current condition. Your credit score serves as the primary indicator of risk. However, your debt-to-income (DTI) ratio is equally significant. A low DTI suggests you have enough monthly cash flow to handle a new payment without defaulting. For budget vehicles, lenders also scrutinize mileage and overall condition. A car with 140,000 miles is viewed differently than one with 90,000 miles, even if the price is identical. They want to ensure the car will remain operational for the entire duration of the loan term.
The Power of the Down Payment
A substantial down payment is your most effective tool for securing favorable terms. Aiming for 10% to 20% of the purchase price can drastically lower your interest rate by reducing the lender's exposure. It also helps bridge the gap if a car's price is slightly higher than the lender's specific loan limit for that model. You can use a car loan calculator to visualize how even a small increase in your upfront payment reduces your monthly obligation and total interest. This strategy ensures you don't start your loan with negative equity. It creates an immediate buffer that protects you if you need to sell the vehicle unexpectedly.
Protecting Your Investment
Reliability is the biggest concern for buyers in this price range. While we've discussed the value of quality inventory, mechanical issues can happen with any high-mileage vehicle. This makes extended warranties vital for long-term peace of mind. According to the FTC guide to buying a used car, understanding your warranty options is a key part of the purchasing process. Many lenders allow you to roll the cost of an extended warranty directly into your financing. This creates a single, predictable monthly payment that covers both the loan and potential major repairs. It effectively transfers the risk of expensive breakdowns from your savings account to the warranty provider. This ensures your budget stays intact even if a major component requires service.
Step-by-Step Guide to Securing Your Used Car Loan
Preparation is the foundation of a successful vehicle purchase. You should begin by requesting a free copy of your credit report to identify and dispute any inaccuracies. Even a small error can negatively impact your score and lead to higher interest charges. Once your credit is verified, establish a total budget that accounts for more than just the monthly payment. You must include local tax, title, and license (TTL) fees to avoid surprises at the signing table. This preparation ensures that financing used cars under 10000 remains a sustainable financial decision rather than a burden.
Preparing Your Financial Documents
Local lenders in the Metro East area require specific proof of stability. For W-2 employees, this usually means providing your two most recent pay stubs. if you're a self-employed buyer, be prepared to show at least three to six months of bank statements to verify consistent income. You'll also need a valid driver's license and proof of current auto insurance. Having these documents organized before you visit the dealership accelerates the approval process and demonstrates that you are a serious, well-prepared borrower.
Reviewing the Fine Print
Before you sign any contract, examine the Truth in Lending disclosure. Pay close attention to the "Total of Payments" figure. This represents the actual amount you'll pay over the life of the loan after interest is added. You should also verify that there are no prepayment penalties. These fees punish you for paying off the car early, which is a strategy many budget-conscious buyers use to save on interest. Finally, ensure the specific vehicle, such as one of our used SUVs under 10000 Pontoon Beach, meets the lender's age and mileage requirements. Some institutions won't fund older models regardless of your credit score.
Finalizing your purchase is the last step in a successful journey. Getting pre-approved gives you a clear maximum loan amount, allowing you to shop with confidence and stay within your means. If you are ready to see what's possible for your budget, you can view our current financing options today to get started.
Financing Your Next Vehicle with 111 Auto Sales LLC in Pontoon Beach
111 Auto Sales LLC stands as a dedicated partner for drivers seeking stability in the secondary market. Our focus remains on the specific needs of the Metro East community, where reliable transportation is a necessity rather than a luxury. We specialize in maintaining an inventory tailored to budget-conscious buyers. Every pre-owned sedan, SUV, truck, and van in our lot is selected to meet high standards for quality and transparency. By focusing on financing used cars under 10000, we provide a level of expertise that larger, generic franchises often overlook. We believe that a lower price point should never mean a compromise in service or professionalism.
Our team simplifies the complexities of financing used cars under 10000 by offering structured solutions that fit your specific monthly budget. We recognize that every financial situation is unique. Because we operate as an independent dealership, we maintain the flexibility to work closely with you throughout the entire approval process. This personalized attention removes the traditional burdens of car shopping from your shoulders. It allows you to focus on choosing the right vehicle for your daily commute while we handle the logistical details. Our goal is to ensure your financing is as reliable as the car you drive home.
A Local Approach to Auto Sales
We're proud to serve Pontoon Beach, Granite City, and the surrounding Illinois areas. Our deep roots in the Metro East automotive market allow us to build strong relationships with local lenders. These connections often translate into more efficient processing and clearer communication for our customers. From the initial test drive to the final signature on your loan contract, the 111 Auto Sales LLC process prioritizes a straightforward, factual approach. We don't use aggressive sales tactics. Instead, we provide the documentation and background information you need to make a confident decision. This commitment to honesty helps build the long-term trust that defines our business.
Start Your Application Today
Securing your next vehicle shouldn't be a source of stress. We offer a variety of reliable options, including a specialized selection of used trucks under 10000 Pontoon Beach for those needing extra utility. Our inventory is constantly updated to reflect the best values available in the current market. To protect your investment, we also provide extended warranty options that can be integrated into your financing plan. This ensures that you have coverage for major components, providing peace of mind well after you leave the lot.
You can jumpstart your journey by using our online tools to explore your options from the comfort of your home. If you're ready to secure a manageable monthly payment on a vehicle you can trust, we invite you to take the next step. Apply for financing at 111 Auto Sales LLC today! Our professionals are ready to help you navigate the process with the respect and expertise you deserve.
Secure Your Affordable Metro East Vehicle Today
Securing reliable transportation doesn't have to be a financial burden. By understanding the specific mechanics of financing used cars under 10000, you've taken the first step toward long-term stability. Success in this market segment depends on thorough preparation and choosing a partner that understands the local landscape. Organizing your financial documents early and providing a strategic down payment will significantly improve your loan terms. These steps ensure you build equity quickly while maintaining a manageable monthly budget.
111 Auto Sales LLC specializes in providing the Metro East community with a transparent path to ownership. We offer a curated inventory of budget-friendly vehicles and provide access to extended warranties for your peace of mind. Our local expertise ensures that every step of the process is handled with the precision and respect you deserve. It's time to stop worrying about high interest rates and start driving a vehicle that fits your lifestyle perfectly.
View Our Inventory of Used Cars Under $10,000 and see how simple affordable financing can be. We're here to help you move forward with confidence.
Frequently Asked Questions
Can I get a car loan if the vehicle is priced under $10,000?
Yes, you can secure a loan for vehicles in this price range. While some national lenders require a minimum loan amount of $7,500, independent dealers like 111 Auto Sales LLC specialize in financing used cars under 10000. These loans are specifically structured for vehicles with higher mileage or age. Our team works with a network of local lenders to find terms that fit your budget, ensuring you don't have to pay cash upfront for a reliable daily driver.
What is the typical down payment for a budget used car?
A typical down payment for a budget friendly car ranges between 10% and 20% of the purchase price. For a vehicle priced at $9,000, this means an upfront payment of $900 to $1,800. Providing a larger down payment is beneficial because it reduces your loan to value (LTV) ratio. This makes you a more attractive borrower to lenders and often results in a lower interest rate, which decreases your total cost of ownership over time.
How does my credit score affect my interest rate on an older vehicle?
Your credit score is the primary factor determining your APR. As of early 2026, Super Prime borrowers with scores above 780 see average rates near 6.82%. Conversely, Deep Subprime borrowers with scores under 500 may see rates around 21.58%. Higher scores signal lower risk to lenders, allowing them to offer more competitive terms. Improving your score by even 50 points before applying can save you hundreds of dollars in interest over a 48 month loan term.
Are there age or mileage limits for used car financing?
Many traditional banks impose strict limits, often refusing to finance cars over 10 years old or with more than 125,000 miles. However, 111 Auto Sales LLC works with lenders who understand the Metro East market and offer more flexibility. While age and mileage impact the interest rate and maximum loan term, we focus on the vehicle's actual condition and reliability. This approach allows us to help customers find quality transportation that other institutions might overlook.
Can I include an extended warranty in my auto loan?
Yes, you can roll the cost of an extended warranty directly into your financing package. This creates a single, predictable monthly payment that covers both your loan and potential mechanical repairs. Adding a warranty is a smart way to protect your investment, especially when financing used cars under 10000. It ensures that an unexpected repair bill won't disrupt your financial stability, providing long term peace of mind for buyers in Pontoon Beach and Granite City.
What documents do I need to bring to the dealership for financing?
You should bring a valid driver's license, proof of current auto insurance, and documentation of your income. W-2 employees typically need their two most recent pay stubs. Self employed buyers in the Metro East should provide three to six months of bank statements to verify consistent earnings. Having these documents ready when you arrive at our Pontoon Beach location streamlines the process. It allows our finance team to secure your approval quickly without unnecessary delays.
How long does the financing approval process take at 111 Auto Sales LLC?
The financing approval process at 111 Auto Sales LLC is designed to be efficient and transparent. Because we are a local, independent dealership, we can often provide answers much faster than large national chains. Most customers receive a decision shortly after submitting their application and required documentation. We prioritize your time and aim to get you behind the wheel of your sedan, SUV, or truck as quickly as possible while ensuring every detail of the contract is clear.


