
Walking into a dealership without a financing plan is like trying to hit a moving target in the dark. With the average price of a three-year-old vehicle climbing to $32,651 in 2026, the stakes for your budget have never been higher. You've likely felt the anxiety of wondering if your credit history will lead to a rejection or if the monthly payment will actually fit your lifestyle. It's frustrating to spend hours researching SUVs and trucks only to realize they're outside your reach. Securing a used car loan pre-approval in Pontoon Beach changes the entire dynamic. It transforms you from a hopeful browser into a prepared buyer with the leverage of a cash offer.
We believe that the financing process should be transparent and straightforward. This guide will show you how to lock in your budget and simplify your next purchase in the Metro East area. You'll learn how to navigate 2026 regulations, including the new federal tax deduction for vehicle loan interest and the Illinois 36% APR cap. We'll walk through the steps to secure a payment that works for you, whether you're looking for a premium sedan or a reliable vehicle under $10,000. By the end, you'll have a clear roadmap to shop with confidence and protect your investment with the right warranty options.
Key Takeaways
- Understand the critical difference between a soft pre-qualification and a formal pre-approval to establish your true buying power before visiting the lot.
- Secure your used car loan pre-approval in Pontoon Beach to gain the negotiating leverage of a cash buyer and streamline the entire purchasing process.
- Identify how your credit score and debt-to-income ratio impact your 2026 interest rates and overall loan eligibility under current Illinois regulations.
- Learn how to protect your investment through extended warranties and GAP coverage, ensuring long-term financial security for your pre-owned vehicle.
- Use your pre-approved status to efficiently filter our inventory of trucks, SUVs, and sedans, including our specialized selection of vehicles under $10,000.
What is Used Car Loan Pre-Approval and Why Do You Need It?
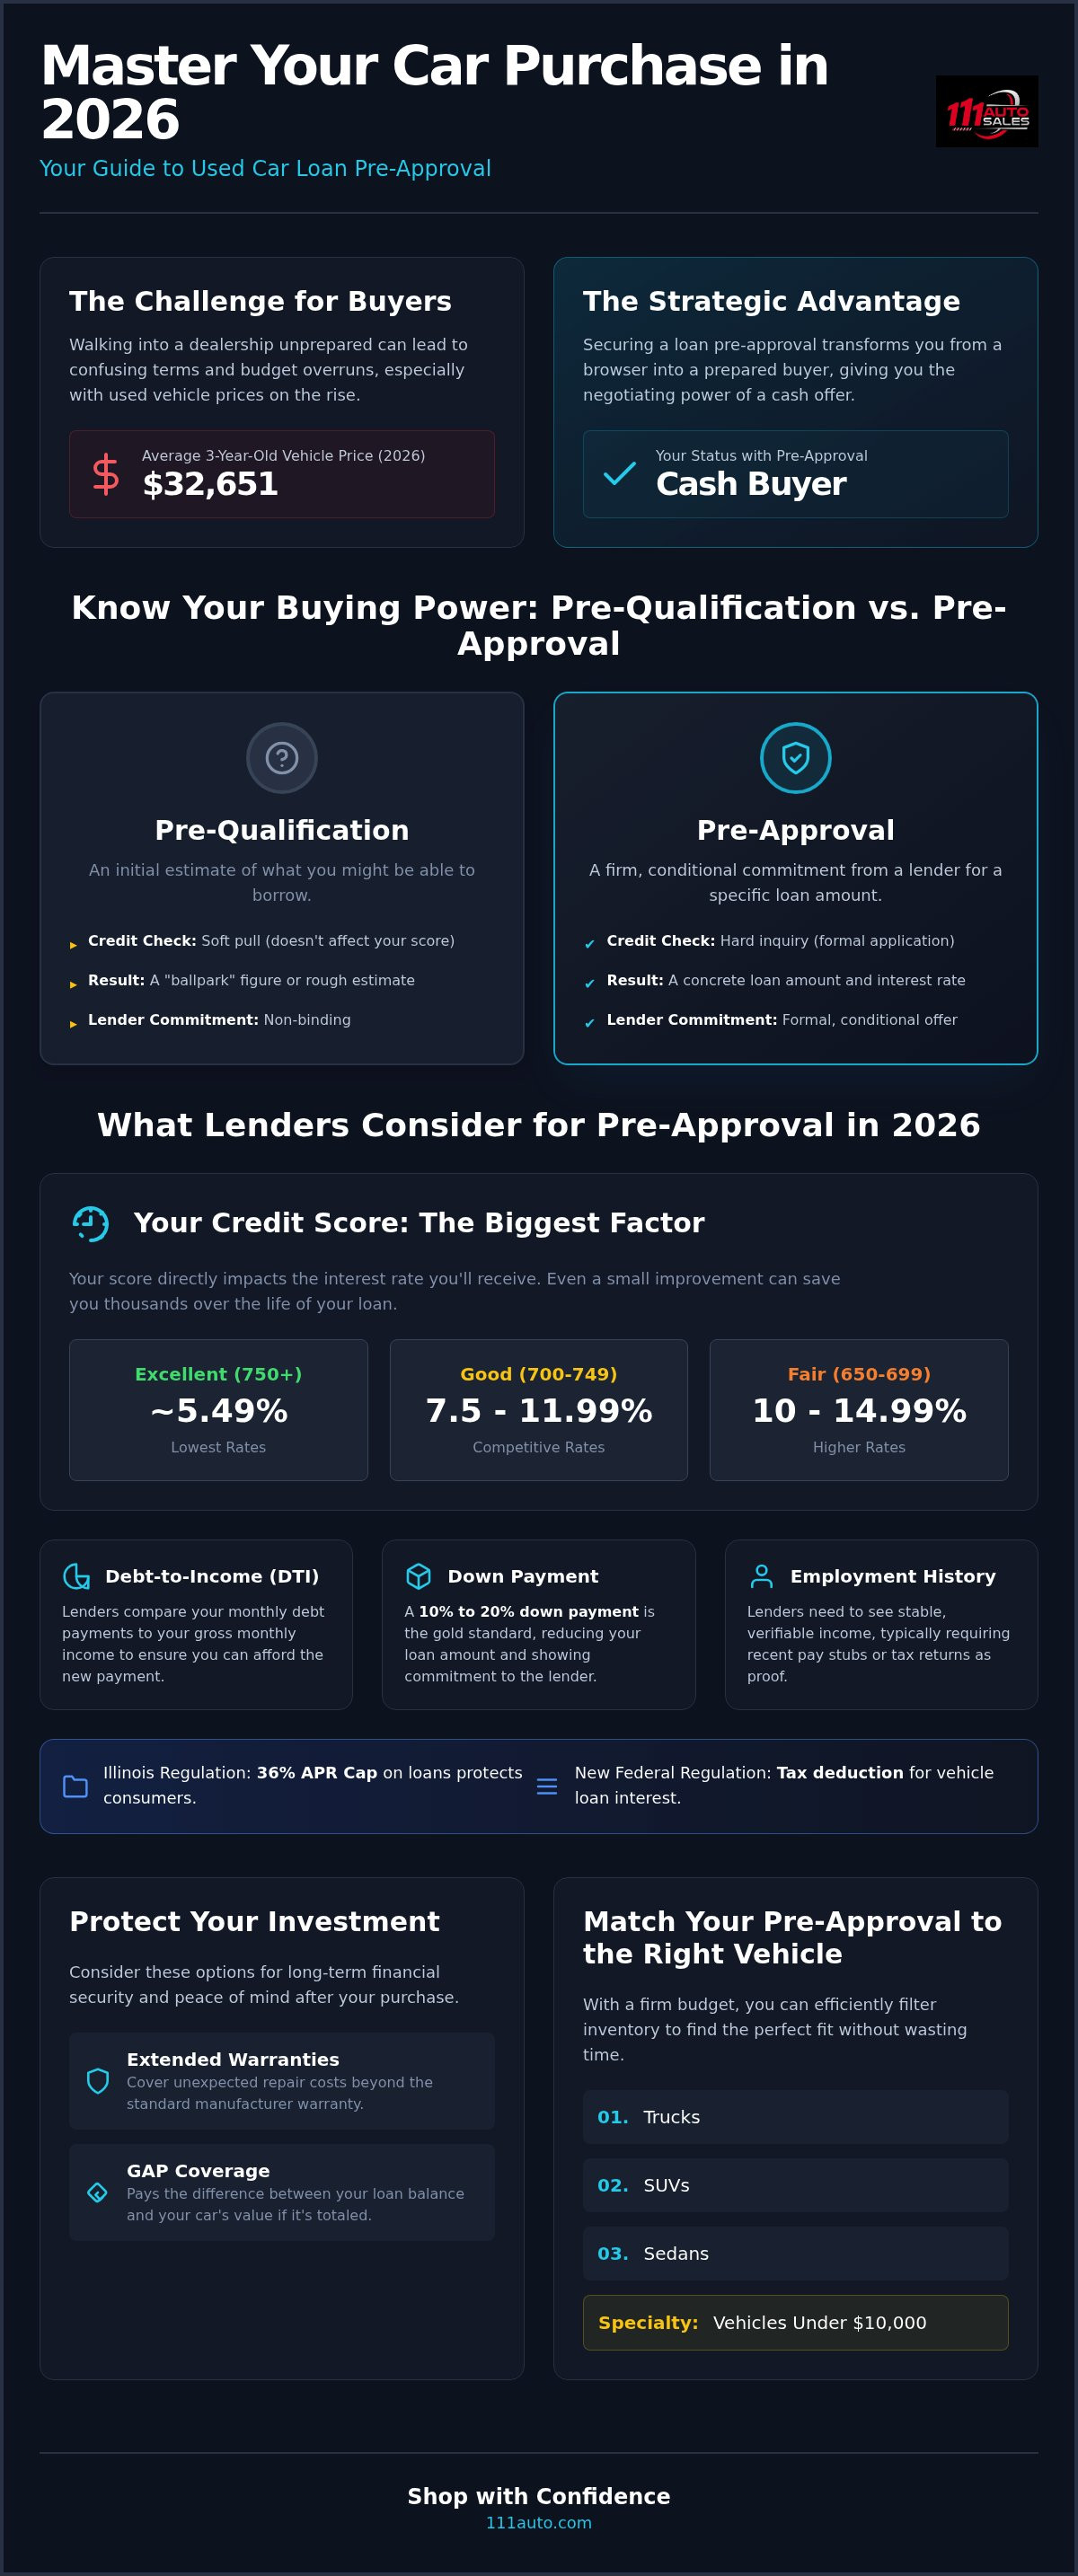
A used car loan pre-approval is a conditional commitment from a lender stating exactly how much they're willing to lend you and at what interest rate. It's distinct from a pre-qualification. While a pre-qualification often relies on a soft credit pull and provides a ballpark figure, a used car loan pre-approval in Pontoon Beach involves a hard credit check. This gives you a concrete number you can take to the bank. Understanding how car financing works before you start browsing inventory prevents the disappointment of falling in love with a vehicle that doesn't fit your financial reality.
For residents in the Metro East, this step is vital. Many buyers in Pontoon Beach find themselves visiting lots in Granite City or Collinsville without a clear plan. This often leads to "payment-based" selling. In this scenario, a buyer focuses solely on the monthly cost rather than the total price of the vehicle, the interest rate, or the loan term. Pre-approval flips the script. It forces the conversation to stay on the actual value of the truck, SUV, or sedan you're eyeing. You'll know your limits before the first test drive.
The Power of the 'Cash Buyer' Status
Walking into a dealership with a pre-approval letter essentially grants you "cash buyer" status. Dealerships take these buyers more seriously because the financing hurdle is already cleared. It simplifies negotiations. You can discuss the price of the car directly without the confusion of trade-in values and financing terms clouding the deal. This clarity speeds up the process significantly. When you have a used car loan pre-approval in Pontoon Beach, the paperwork on the day of purchase moves much faster because the core financial structure is already established.
Budgeting for the Metro East Commute
Your budget should reflect the reality of driving in the Metro East. Between commuting to St. Louis and local trips, fuel and insurance costs add up. In the current September 2026 environment, interest rates for used vehicles vary widely based on credit scores. Buyers with excellent credit might see rates around 5.49%, while fair credit scores may face rates closer to 14.99%. Factoring these percentages into your total cost of ownership is essential for long-term stability. Ultimately, pre-approval serves as the foundation of a stress-free car buying experience.
Key Factors Lenders Consider for Pre-Approval in 2026
Securing a used car loan pre-approval in Pontoon Beach requires a clear understanding of what lenders prioritize when they review your application. In 2026, the criteria have become more precise to reflect current economic stabilization. Lenders primarily look at your credit score, debt-to-income (DTI) ratio, and your employment history. Familiarizing yourself with your consumer rights for auto loans ensures you're treated fairly throughout this rigorous evaluation process.
Your DTI ratio is a critical measure of your financial health. It compares your monthly debt obligations to your gross monthly income. Lenders want to see enough "room" in your budget to comfortably handle a new car payment without risking default. For Metro East workers, proving employment stability is just as vital. Most lenders require at least two recent pay stubs or tax returns to verify that your income is consistent and reliable. Additionally, keep in mind that many financial institutions place restrictions on vehicle age and mileage for used car loans, often preferring vehicles less than ten years old.
Credit Scores and Interest Rates
As of September 2026, your credit score remains the single most influential factor in determining your interest rate. For those with excellent credit (750 or higher), rates can be as low as 5.49% for shorter terms. If your score falls in the "good" range (700-749), you'll likely see rates between 7.50% and 11.99%. Buyers with fair credit (650-699) should expect rates from 10.00% to 14.99%. even a small 50-point improvement in your score can save you thousands of dollars in interest over the life of the loan. If your credit is less than perfect, focus on showing a strong down payment or consistent recent payment history to improve your eligibility.
Down Payments and Trade-In Values
A down payment of 10% to 20% is still the gold standard for used car financing. This initial investment reduces the total loan amount and demonstrates your commitment to the purchase. Your current vehicle’s trade-in value acts as a direct credit toward this amount, lowering your monthly payments and potentially qualifying you for better terms. If you're specifically looking for a commuter car, check out our guide on used sedan financing Pontoon Beach for tailored budgeting tips. Balancing your down payment with a realistic loan term is the best way to maintain a healthy budget. You can start by viewing our available pre-owned inventory to see which models fit your projected pre-approval amount.
Guide to Pre-Approval at 111 Auto Sales
Applying for a used car loan pre-approval in Pontoon Beach at 111 Auto Sales is a transparent and efficient experience. Unlike the multi-step membership requirements found at some regional credit unions, our process focuses on getting you into a reliable truck or SUV without unnecessary hurdles. You can complete the secure online financing application at 111auto.com from your home or office. This digital approach allows our team to review your financial profile and provide a conditional commitment before you visit our location on IL-111.
Once your application is submitted, we provide a detailed loan offer. This document outlines your maximum loan amount, the interest rate, and the specific term length. In 2026, it's also important to consider the "One Big Beautiful Bill Act," which introduced a federal tax deduction for qualified passenger vehicle loan interest. Your lender will provide Form 1098-VLI to help you track this. Most pre-approvals remain valid for 30 to 60 days, giving you a generous window to browse our diverse inventory of pre-owned vehicles.
Documentation You Will Need
To ensure a smooth approval, you should have several key documents ready for verification. Lenders require these to confirm your ability to repay the loan and your residency in the Metro East area.
- Proof of Income: You'll need your two most recent pay stubs. If you're a self-employed resident in the Pontoon Beach area, provide your two most recent tax returns to verify consistent earnings.
- Proof of Residence: A utility bill, lease agreement, or property tax statement from within the last 30 days is standard. This confirms your local address in Madison County.
- Identification and Insurance: A valid driver's license and current auto insurance information are mandatory for the final loan contract.
Understanding Your Loan Terms
Your offer will specify an Annual Percentage Rate (APR), which represents the total yearly cost of the loan including interest and fees. This is different from simple interest, as it provides a more accurate picture of your total financial obligation. You'll also choose a loan term, typically 36, 48, or 60 months. While a 36-month term reduces the total interest paid over time, a 60-month term offers lower monthly payments that may better fit a tighter budget. During this phase, we also discuss the benefits of Warranties and GAP Coverage to protect your investment. 111 Auto Sales simplifies this process by handling financing and inventory under one roof. Securing your used car loan pre-approval in Pontoon Beach is the most effective way to maintain control over your vehicle purchase.
Protecting Your Investment: Warranties and GAP Coverage
Securing a used car loan pre-approval in Pontoon Beach is a strategic move, but protecting that investment is equally important. When you purchase a pre-owned vehicle, especially one with higher mileage, unexpected mechanical issues can disrupt your budget. Extended warranties and GAP coverage act as a financial safety net. These protections ensure that your daily commute or work schedule remains uninterrupted by repair costs or total loss scenarios. It's better to plan for these contingencies during the financing phase than to face them unprepared later.
One of the primary advantages of working with a local dealership is the ability to roll these costs directly into your financing. Instead of paying for a warranty upfront, you can include it in your used car loan pre-approval in Pontoon Beach. This results in a single, predictable monthly payment that covers both the vehicle and its protection. This approach simplifies your monthly budgeting and ensures you aren't caught off guard by large, out-of-pocket expenses. You can apply for financing online today to see how these protection options fit into your lifestyle.
Extended Warranties for Used Cars
Most used car buyers worry about the long-term reliability of their vehicle. An extended warranty addresses this by covering major components like the engine, transmission, and electrical systems. For those purchasing a vehicle for heavy-duty use, a used truck warranty Pontoon Beach provides essential coverage for the demands of Metro East job sites. Beyond repair protection, these warranties preserve the resale value of your vehicle. A documented service history and active warranty make a car much more attractive to future buyers when it's time to trade up.
GAP Insurance Explained
GAP insurance, or Guaranteed Asset Protection, covers the difference between what you owe on your loan and the actual cash value of the vehicle if it's totaled or stolen. This is vital for buyers who opt for low down payments. In the first few years of ownership, depreciation can happen faster than the loan balance decreases, leading to "negative equity." Without GAP, you could be left paying off a loan for a car you no longer own. You should ask about these protection plans during your initial financing consultation to ensure you're fully covered from day one.
Matching Your Pre-Approval to the Right Inventory
Most banks and credit unions leave you on your own once the loan is approved. You're handed a piece of paper and told to find a car that fits the lender's specific age and mileage rules. At 111 Auto Sales, we eliminate this disconnect. By securing your used car loan pre-approval in Pontoon Beach directly through our secure portal, you can immediately match your budget to our physical inventory of sedans, SUVs, and trucks. This "one-stop-shop" approach ensures that every vehicle you test drive is one you can actually afford.
Our team helps you find the best value per dollar by analyzing your pre-approved amount against current 2026 market prices. With the average three-year-old used car now priced at $32,651, being strategic is mandatory. We look at the total cost, including any integrated warranties, to ensure your monthly payment remains sustainable for your specific lifestyle in the Metro East. This process removes the guesswork and allows you to shop with the same confidence as a cash buyer.
Affordable Options Under $10,000
Vehicles in this price bracket are ideal for first-time buyers or local commuters looking to avoid high monthly overhead. We apply specialized financing strategies to our budget inventory to keep interest rates competitive, even for older models. If you need a reliable vehicle for a job site, explore our used trucks under 10000 Pontoon Beach. These selections are vetted for reliability, maximizing your loan's buying power in a segment where quality often varies. Our goal is to provide dependable transportation that fits within the strictest pre-approval limits.
Family-Ready SUVs and Work-Ready Trucks
For those with larger lifestyle demands, we maintain a diverse selection of family-sized SUVs and heavy-duty trucks. When evaluating these, we use specific criteria found in our guide on durable used family SUVs in Pontoon Beach. This ensures your used car loan pre-approval in Pontoon Beach covers a vehicle that meets your safety, space, and towing requirements. We help you balance the higher demand for these segments with a loan structure that won't strain your finances.
The final step is the most rewarding part of the process. Once you've selected a vehicle that matches your pre-approval, you'll take a test drive to confirm the condition and handling. Since the financing is already structured, the final paperwork is a formality. You won't spend hours in a waiting room. You'll simply verify the details, sign the contract, and drive home with total confidence in your purchase.
Take Control of Your Car Buying Journey
Securing a used car loan pre-approval in Pontoon Beach is the most effective way to eliminate the uncertainty of vehicle shopping. By locking in your interest rate and total loan amount before you visit the lot, you protect yourself from high-pressure sales and unsustainable monthly payments. This strategic step transforms the entire process into a transparent, efficient experience where you hold the power of a cash buyer.
At 111 Auto Sales, we've served the Metro East for years by prioritizing clarity and customer security. Whether you're browsing our wide selection of inventory under $10,000 or looking for a work-ready truck, our team is here to help you match your budget to the right vehicle. Our extended warranty options provide the peace of mind you need to drive home with total confidence. Don't leave your next purchase to chance; start with a solid financial foundation.
Apply for Financing and Get Pre-Approved Today and start your journey with a partner you can trust. Your next reliable vehicle is closer than you think.
Frequently Asked Questions
How long does the pre-approval process take at 111 Auto Sales?
Our secure online financing application is designed for maximum efficiency, and most applicants receive a response within the same business day. Once you submit your documentation through our website, our team immediately begins reviewing your profile to establish your buying power. This streamlined approach allows Pontoon Beach residents to move from the initial application to test-driving a truck or SUV in just a few hours, ensuring your time is used effectively.
Does getting pre-approved for a car loan hurt my credit score?
A formal pre-approval involves a hard credit inquiry, which typically results in a minor and temporary dip in your credit score. This is a standard requirement for securing a used car loan pre-approval in Pontoon Beach, as lenders need a detailed view of your history to offer firm interest rates. Most modern credit scoring models treat multiple inquiries for an auto loan within a short window as a single event to minimize the impact.
Can I get pre-approved if I have a low credit score?
Yes, we work with a wide range of credit profiles to help local buyers secure reliable transportation. While your credit score influences the specific interest rate you'll receive, it's only one part of the overall evaluation. We specialize in finding solutions for our diverse inventory, including our selection of vehicles under $10,000. Providing a stable proof of income or a larger down payment can often help those with less-than-perfect credit obtain an approval.
How long is my used car loan pre-approval valid?
Most pre-approval offers remain valid for a period of 30 to 60 days. This generous window gives you enough time to browse our inventory of pre-owned sedans and SUVs without feeling pressured to make an immediate decision. If your pre-approval expires before you find the right vehicle, you'll simply need to provide updated pay stubs to refresh the offer. This ensures your financing terms stay aligned with the current 2026 interest rate environment.
What is the difference between pre-approval and pre-qualification?
Pre-qualification is a basic estimate based on a soft credit pull, whereas pre-approval is a firm commitment based on a comprehensive hard credit check. Pre-approval provides a specific loan amount and interest rate, giving you the same negotiating leverage as a cash buyer. For serious shoppers in Granite City or Collinsville, having a used car loan pre-approval in Pontoon Beach is the more strategic choice for accurate budgeting and a faster closing process.
Can I use my pre-approval for any vehicle on the lot?
Your pre-approval can generally be applied to any vehicle in our inventory that meets the lender's specific age and mileage requirements. We help you match your approved amount to our selection of pre-owned trucks, SUVs, and vans to ensure the vehicle fits within your financial boundaries. If you choose a model from our budget-friendly "Under $10,000" category, your pre-approval often covers the entire cost, which simplifies the final transaction and reduces your out-of-pocket expenses.
Do I need a down payment if I am already pre-approved?
While some pre-approval structures offer low-down-payment options, providing 10% to 20% upfront is still the best way to secure favorable terms. A down payment reduces the total amount you need to borrow, which can lower your monthly payment and total interest costs over the life of the loan. Even with a strong pre-approval, using a trade-in or cash down payment helps you stay well within the Illinois 36% APR cap for consumer loans.
What happens if the car I want costs more than my pre-approved amount?
If the vehicle you select exceeds your pre-approved loan limit, you can simply cover the difference with a cash down payment or a trade-in. This allows you to move into a higher-priced SUV or truck while keeping your financed amount within your pre-set limits. Our team will work with you to calculate these adjustments transparently, ensuring the final deal aligns with your budget and any extended warranty protections you choose to include.


