
Why do national banks treat a reliable $9,000 work truck as a "risky asset" when it's the exact tool you need to get the job done? In 2026, securing financing used trucks under 10000 often feels like a struggle against rigid corporate checklists that ignore the needs of local drivers. You've likely noticed that many lenders hike interest rates on older vehicles or refuse to fund assets below a certain price point. It's a common hurdle in the Metro East area, leaving many buyers worried they'll end up with a "lemon" or a predatory loan.
We believe that a limited budget shouldn't force you into a corner or compromise your peace of mind. You're looking for a dependable work vehicle with low monthly payments and honest, transparent terms. This guide shows you exactly how to navigate the local lending landscape in Pontoon Beach to find a deal that fits your life. We'll break down current 2026 market rates, explain how to bypass bank refusals, and detail the protection plans that keep your truck on the road for years to come.
Key Takeaways
- Understand how Loan-to-Value (LTV) ratios and vehicle age specifically impact your borrowing power for older pickups in 2026.
- Compare the flexibility of specialized dealership lending against the rigid approval criteria of traditional national banks.
- Identify the exact documentation required for Illinois residency to streamline the process of financing used trucks under 10000.
- Learn how to protect your investment with extended warranty options designed for reliable, high-mileage work vehicles.
- Discover the advantages of "one-stop" shopping in Pontoon Beach to secure same-day approval and transparent loan terms.
What Does Financing Used Trucks Under 10000 Entail?
In Pontoon Beach, finding a work-ready vehicle requires a specific financial strategy. When we talk about financing used trucks under 10000, we're describing a specialized retail installment contract. This is a legal agreement where you agree to pay the purchase price plus interest over a set period. Unlike standard new car loans, budget truck financing focuses on assets that have already seen significant road time but still offer immense utility for the Metro East workforce. These contracts are designed to make ownership accessible without the massive debt associated with newer models.
Trucks in this price bracket are high-demand assets. In 2026, many drivers in Granite City and Collinsville find that reliable pickups under $10,000 sell within days of hitting the lot. Economic shifts have made these vehicles essential for small business owners and commuters who need durability without a massive monthly commitment. To secure one of these loans, the down payment plays a vital role. Lenders often require a slightly higher percentage upfront for older models to offset the risk associated with higher mileage. This initial investment secures your stake in the vehicle and often leads to more favorable loan terms.
The Mechanics of a Budget Auto Loan
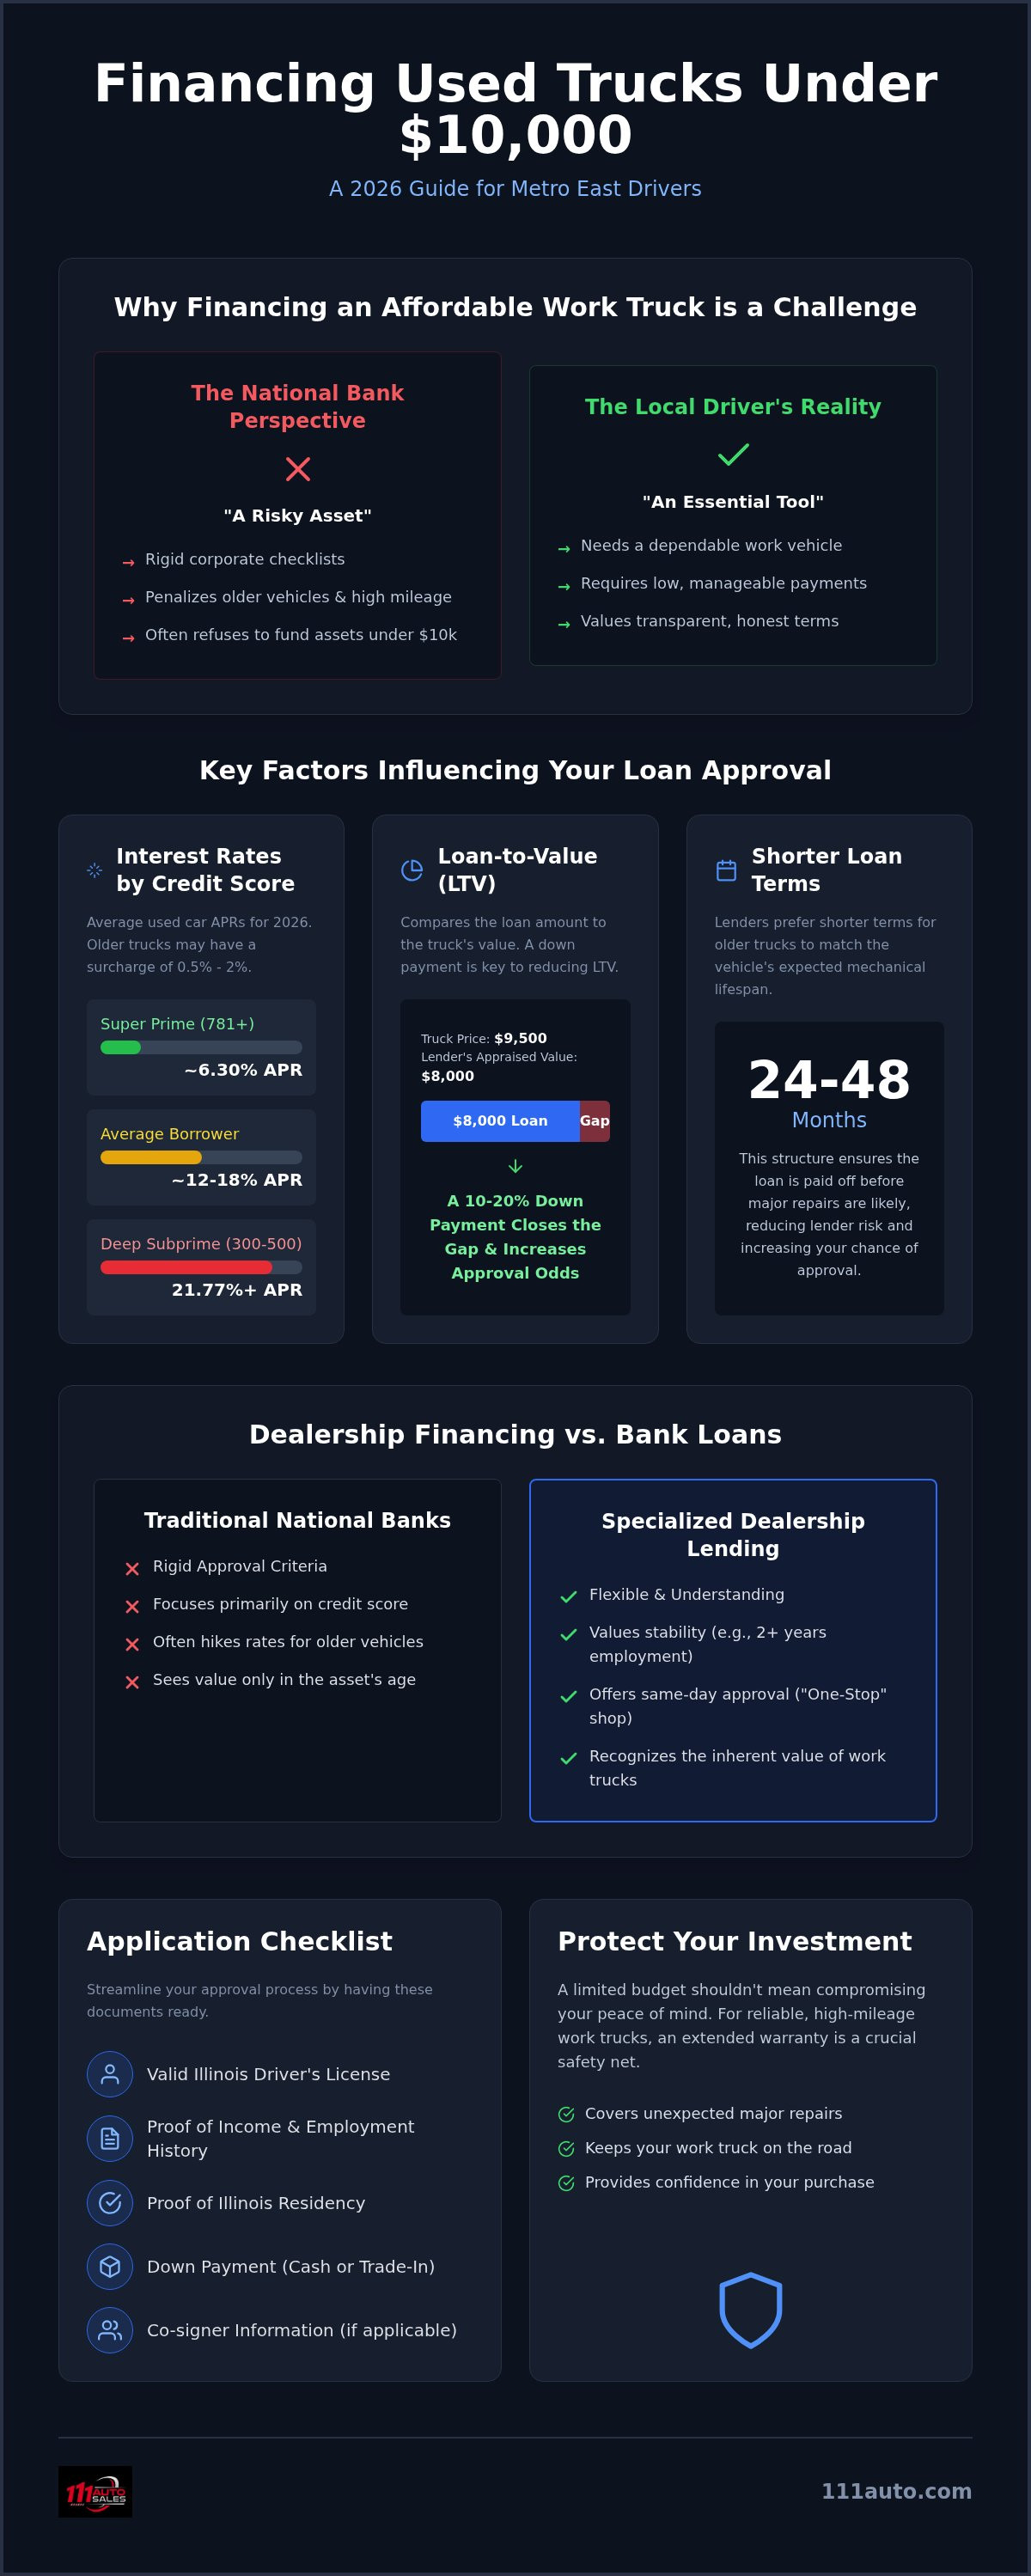
Understanding car financing basics helps you grasp how these specific deals are structured. The principal refers to the actual sale price of your pre-owned truck. Because these vehicles are typically over ten years old, term lengths are usually shorter than what you'd see for a new model. Most local lenders prefer 24 to 48-month terms. This structure ensures you aren't paying for the truck longer than its expected mechanical lifespan. Working with a local lender who understands the Pontoon Beach market is crucial. They recognize the inherent value in a well-maintained truck, even with 150,000 miles on the odometer, whereas national banks might only see the age of the asset.
Benefits of Financing vs. Paying Cash
Many buyers assume cash is always the best path for a budget purchase. However, financing offers several strategic advantages for residents in the Metro East. It allows you to preserve your liquid savings for emergency repairs or business operational costs. It's often safer to have a manageable monthly payment and $5,000 in the bank than to spend every cent on a truck and have no safety net for future maintenance.
Additionally, consistent monthly payments help you build or rebuild your credit score. This is particularly valuable if you're looking to qualify for better rates on future purchases. Finally, financing increases your buying power. Instead of settling for a high-mileage "beater" with your available cash, you can leverage a loan to afford a higher-quality truck. This often means getting a vehicle with a cleaner service history that will last longer and require fewer immediate repairs.
Interest Rates and Credit Factors for Budget Trucks
Securing financing used trucks under 10000 in 2026 involves navigating a specific set of interest rate tiers. While a "super prime" borrower with a score above 781 might see an average used car APR of 6.30%, the reality for older vehicles is often different. Lenders typically view trucks over ten years old as higher risks. They often apply a surcharge of 0.5% to 2% on top of standard rates for these high-mileage assets. For those with "deep subprime" scores between 300 and 500, rates can exceed 21.77%. Understanding these tiers helps you set a realistic budget for your monthly commitment.
The "Loan-to-Value" (LTV) ratio is another critical factor for budget trucks. This ratio compares the loan amount to the vehicle's appraised value. If a truck is priced at $9,500 but a lender values it at $8,000, you face an LTV gap. Most lenders prefer an LTV under 100% for older pickups. Providing a down payment of 10% to 20% effectively lowers this ratio, which significantly increases your approval odds. Shorter loan terms, such as 24 to 36 months, also improve your standing with lenders. They're more likely to approve a loan that pays off before the vehicle reaches the end of its expected mechanical life. You can find more consumer auto loan resources to help calculate these ratios before visiting the lot.
Credit Profiles in the Metro East
Local lenders in the Pontoon Beach area often look beyond just a three-digit credit score. They value stability, particularly your employment history within Granite City, Collinsville, or the greater St. Louis region. A consistent two-year track record with the same employer can sometimes outweigh a lower credit score. If your profile still falls short of lender requirements, adding a co-signer with established credit can secure a lower APR and better terms. This collaborative approach often makes the difference between a rejection and driving home in a reliable work vehicle.
Securing Your Investment with a Warranty
Financing an older truck means you're taking on an asset that has already proven its durability, but high mileage always carries some risk. Integrating a protection plan into your monthly payment provides total peace of mind. These plans typically add only a small amount to your monthly bill but prevent a single mechanical failure from becoming a financial crisis. For a deeper look at how these plans work, read our guide on Used Truck Warranty Pontoon Beach: Protecting Your Metro East Investment. If you're ready to see which trucks in our inventory qualify for these terms, you can browse our current selection to find a match for your budget.
Dealership Financing vs. Bank Loans for Used Pickups
Choosing the right lender is just as important as choosing the truck itself. For those seeking financing used trucks under 10000, the path often splits between traditional banks and specialized dealerships. Large national banks typically prioritize high-value assets and newer models. This often leaves budget-conscious buyers in the Metro East facing automatic rejections based solely on the age or price of the vehicle. Local dealerships, however, operate with a different set of priorities that favor the buyer.
The Traditional Bank Obstacle
Big banks often impose strict mileage and age limits. Many won't finance a vehicle with over 100,000 miles or one that's more than seven years old. Since most trucks under $10,000 fall into these categories, traditional routes are frequently closed. Additionally, many lenders have a minimum loan floor. If you only need to borrow $7,000, you might find a bank refuses to process the application because the asset value is too low for their portfolio. This lengthy approval process can take several business days. In a fast-moving market like Pontoon Beach, that delay often means the truck you wanted is sold before your paperwork clears. Understanding how to get a loan for a used car through the right channels is the first step toward a successful purchase.
The Dealership Advantage for Budget Buyers
Local dealerships offer a significant edge for budget buyers by providing access to multiple subprime and local lenders with a single application. This "one-stop" shopping model is designed for speed and flexibility. We can often secure an approval in the same afternoon you test drive the vehicle. This efficiency is vital when looking for Used Trucks Under 10000 in Pontoon Beach: Reliable Picks for 2026, as these high-demand assets move quickly.
Our deep roots in the community allow us to build relationships with lenders who understand the Metro East economy. We know that a well-maintained pickup is a workhorse that retains value far beyond what a computer algorithm at a national bank might suggest. This specialized knowledge allows us to advocate for you, helping first-time buyers or those with limited credit history find a path to ownership. By coordinating financing used trucks under 10000 in-house, we remove the friction between finding the right truck and getting the keys. This local approach ensures you get transparent terms that fit your specific financial situation in Collinsville or Alton.
Application Checklist for Pontoon Beach Truck Buyers
Preparation is the key to a smooth experience when financing used trucks under 10000. Walking onto the lot with a complete folder of documents can be the difference between a same-day approval and multiple trips back and forth. Lenders in the Metro East look for specific markers of stability. Having these ready allows our team to match you with the best available terms immediately.
Essential Documentation for Illinois Residents
To satisfy Illinois state laws and lender requirements, you'll need several key items. This includes a valid Illinois driver's license and current proof of insurance. You must also provide recent pay stubs from your employer. If you work in Granite City or St. Louis, having the last 30 days of income documented is the standard expectation. Lenders also require residency verification to confirm your address in cities like Belleville, Troy, or Pontoon Beach. Utility bills or a signed lease agreement are the most common forms of proof. These steps ensure the transparency we prioritize in every transaction.
Lenders use these documents to verify your identity and your ability to manage a monthly commitment. If you're self-employed, be prepared to provide bank statements or tax returns from the last two years. While this might seem like a lot of paperwork, it protects both you and the lender by ensuring the loan terms are based on accurate financial data. Being organized shows lenders that you're a serious, low-risk applicant, which can sometimes lead to faster processing times.
Setting a Realistic Truck Budget
Before you start browsing, calculate your debt-to-income (DTI) ratio. This is the percentage of your gross monthly income that goes toward paying debts. Lenders generally prefer a DTI below 45% for a successful application. A helpful benchmark is the 10% rule: your monthly truck payment shouldn't exceed 10% of your gross monthly income. This keeps your ownership experience stress-free and manageable while leaving room for other essential living expenses.
Don't forget to account for the total "out-the-door" price. In Madison County, this includes title and registration fees. In 2026, the Illinois documentary fee is $377.63. Under current state regulations, dealers must include this fee in the advertised price. However, you still need to budget for sales tax and state filing fees. Using a car loan calculator before you visit helps you understand how these costs affect financing used trucks under 10000. If you're also considering other body styles, you might find our guide on How to Find Reliable Used SUVs Under $10, 000 in Pontoon Beach: A 2026 Buyer’s Guide useful. Ready to get started? You can apply for pre-approval online to save even more time at the dealership.
Why 111 Auto Sales is the Premier Choice for Truck Financing
When you're looking for financing used trucks under 10000, you need more than just a lender. You need a partner who understands that a truck is an essential tool for your livelihood. At 111 Auto Sales LLC, we've built our reputation on serving the Pontoon Beach and Granite City communities with a focus on reliability and transparency. We don't just stock any vehicle that fits a price point. Our team specializes in selecting work-ready trucks that meet our standards for quality, ensuring you drive away in a vehicle you can trust.
Our finance process is designed to be straightforward. We remove the uncertainty often found at larger, less personal institutions. By coordinating everything in-house, we provide a clear view of your loan terms from the start. This includes helping you navigate the complexities of extended warranties. We believe that a budget-friendly price shouldn't mean sacrificing long-term protection. Our expertise in matching protection plans to high-mileage vehicles ensures your investment is secured against the unexpected.
Serving the Entire Metro East Area
Our dealership is a convenient hub for buyers throughout the Metro East area. Whether you're coming from Collinsville or crossing over from St. Louis, you'll find a professional environment focused on your needs. While trucks are a core part of our expertise, we maintain a diverse inventory of pre-owned sedans, SUVs, and vans to serve every type of driver. We're committed to a no-pressure sales philosophy. Our goal is to provide the information you need to make a confident decision, not to push you into a contract that doesn't fit your budget.
Start Your Pre-Approval Today
Getting started is simple and efficient. You can begin your application through our secure online portal or visit us in person to discuss your options. Our team works diligently with our network of local lenders to find the best possible terms for your specific credit profile. We handle the heavy lifting of financing used trucks under 10000 so you can focus on getting back to work. Visit us on Henger Street in Pontoon Beach to see our current inventory and experience a more professional way to buy your next truck.
Secure Your Next Work Truck in Pontoon Beach
Securing financing used trucks under 10000 doesn't have to be a complicated or stressful process. By choosing local dealership expertise over rigid national banks, you can find flexible terms that respect your specific budget and needs. A solid down payment combined with a complete application folder remains your best strategy for a same-day approval. Most importantly, don't overlook the value of a protection plan. These plans keep your high-mileage workhorse on the road without the fear of unexpected repair costs disrupting your finances.
111 Auto Sales brings deep Metro East expertise to every transaction. We maintain a specialized inventory of reliable vehicles under $10,000, and our team is ready to coordinate extended warranties that fit seamlessly into your monthly payment. We're here to take the weight off your shoulders and provide a transparent, professional experience from the first test drive to the final signature.
Are you ready to get behind the wheel of a dependable pickup? Apply for used truck financing at 111 Auto Sales today! We look forward to helping you find the right vehicle for your needs and your budget with confidence and peace of mind.
Frequently Asked Questions
Can I finance a used truck under $10,000 with bad credit in Pontoon Beach?
Yes, you can secure financing for a used truck even with a lower credit score by working with specialized local lenders. At 111 Auto Sales, we coordinate with partners who look at factors like your employment history in the Metro East rather than just a three-digit score. Providing a larger down payment also helps offset credit risks. Our team focuses on finding financing used trucks under 10000 for drivers who need reliable work vehicles but face credit challenges.
What is the minimum down payment for a budget truck loan?
Lenders typically require a down payment between 10% and 20% for vehicles in this price range. For a $9,000 truck, this means having $900 to $1,800 ready upfront. While some programs may offer lower requirements, a larger initial investment often leads to better loan terms and lower monthly payments. It also reduces the Loan-to-Value (LTV) ratio, which is a key factor that local lenders use to determine your approval odds for older pickups.
How long does the financing approval process take at 111 Auto Sales?
The financing approval process at 111 Auto Sales is designed for efficiency and can often be completed on the same day. Once you provide the necessary documentation, our team works quickly with our network of lenders to secure your terms. This speed is essential in the Pontoon Beach market, where high-demand trucks priced under $10,000 often sell quickly. We recommend starting our online pre-approval process to save even more time during your visit.
Are interest rates higher for trucks under $10,000 than for newer models?
Yes, interest rates for older, high-mileage vehicles are generally higher than those for brand-new models. Lenders view these trucks as higher risks due to potential mechanical issues and faster depreciation. In the first quarter of 2026, average used car APRs were significantly higher than new car rates. However, by choosing a shorter loan term and providing a solid down payment, you can often mitigate some of these costs when financing used trucks under 10000.
Do I need full coverage insurance to finance a used truck in Illinois?
Yes, Illinois lenders require you to carry full coverage insurance for the entire duration of your auto loan. This includes comprehensive and collision coverage to protect the vehicle's value as collateral. While Illinois state law only mandates liability insurance for all drivers, a financed vehicle has additional requirements set by the lienholder. You'll need to provide current proof of this insurance before you can finalize your purchase and drive off our lot.
Can I include an extended warranty in my truck financing package?
You can definitely include an extended warranty in your financing package at 111 Auto Sales. We specialize in coordinating protection plans that cover major mechanical components, which is vital for high-mileage trucks. By rolling the cost into your monthly payment, you gain long-term peace of mind for only a small increase in your bill. This ensures that a single repair doesn't become a financial burden, allowing you to focus on your work instead.
Will a truck with over 150,000 miles qualify for financing?
Trucks with over 150,000 miles can still qualify for financing through our specialized network of local lenders. While many national banks automatically disqualify high-mileage assets, our partners understand the inherent value of a well-maintained work truck in the Metro East area. We prioritize inventory that has been checked for reliability, making these vehicles more attractive to lenders who focus on the practical utility and durability of the truck rather than just the odometer reading.
What documents do I need to bring to the dealership for a loan?
To ensure a smooth approval, you should bring several key documents to the dealership. These include a valid Illinois driver’s license, your most recent pay stubs from a local employer, and a current utility bill for residency verification. You also need to provide proof of full coverage insurance. If you have a co-signer, they will need to provide the same documentation. Having these items ready allows our finance team to process your application without unnecessary delays.


