
The best-fit vehicle isn’t always the one with the lowest sticker price. It’s the one whose full monthly cost leaves room in your budget. If you’re researching pre-owned auto loans Pontoon Beach, look beyond the payment estimate. Interest, loan length, your credit history, and the vehicle’s age and mileage can all affect your financing options.
It’s understandable to wonder how your credit may affect financing or how to compare offers fairly. A clear plan helps: set a realistic budget, understand the main parts of an auto loan, and compare the amount you’ll repay over the full term, not just the monthly payment. This guide explains what can shape financing options and what information to prepare before applying.
You’ll also see how vehicle needs fit into the decision, from choosing among pre-owned sedans, SUVs, trucks, and vans to exploring financing at 111 Auto Sales LLC in Pontoon Beach. The goal is to make an informed purchase with the numbers in view before you choose.
Key Takeaways
- Understand how a pre-owned auto loan connects you, the vehicle seller, and the financing provider.
- See how credit history, income, existing obligations, down payment, and vehicle details may shape loan options.
- Compare APR, loan length, amount financed, and total repayment instead of judging an offer by its monthly payment alone.
- Prepare a practical budget and common application information before reviewing final loan documents.
- Explore pre-owned auto loans Pontoon Beach shoppers can consider alongside sedans, SUVs, trucks, and vans at 111 Auto Sales.
Pre-Owned Auto Loans for Pontoon Beach Buyers
A pre-owned auto loan is financing used to purchase a vehicle, repaid over time under terms set by the financing provider. You choose a vehicle and agree to its purchase details, while the seller transfers the vehicle as part of the sale. The financing provider supplies or arranges the funds and sets applicable terms, such as the interest rate and repayment schedule. The process can vary by lender and transaction.
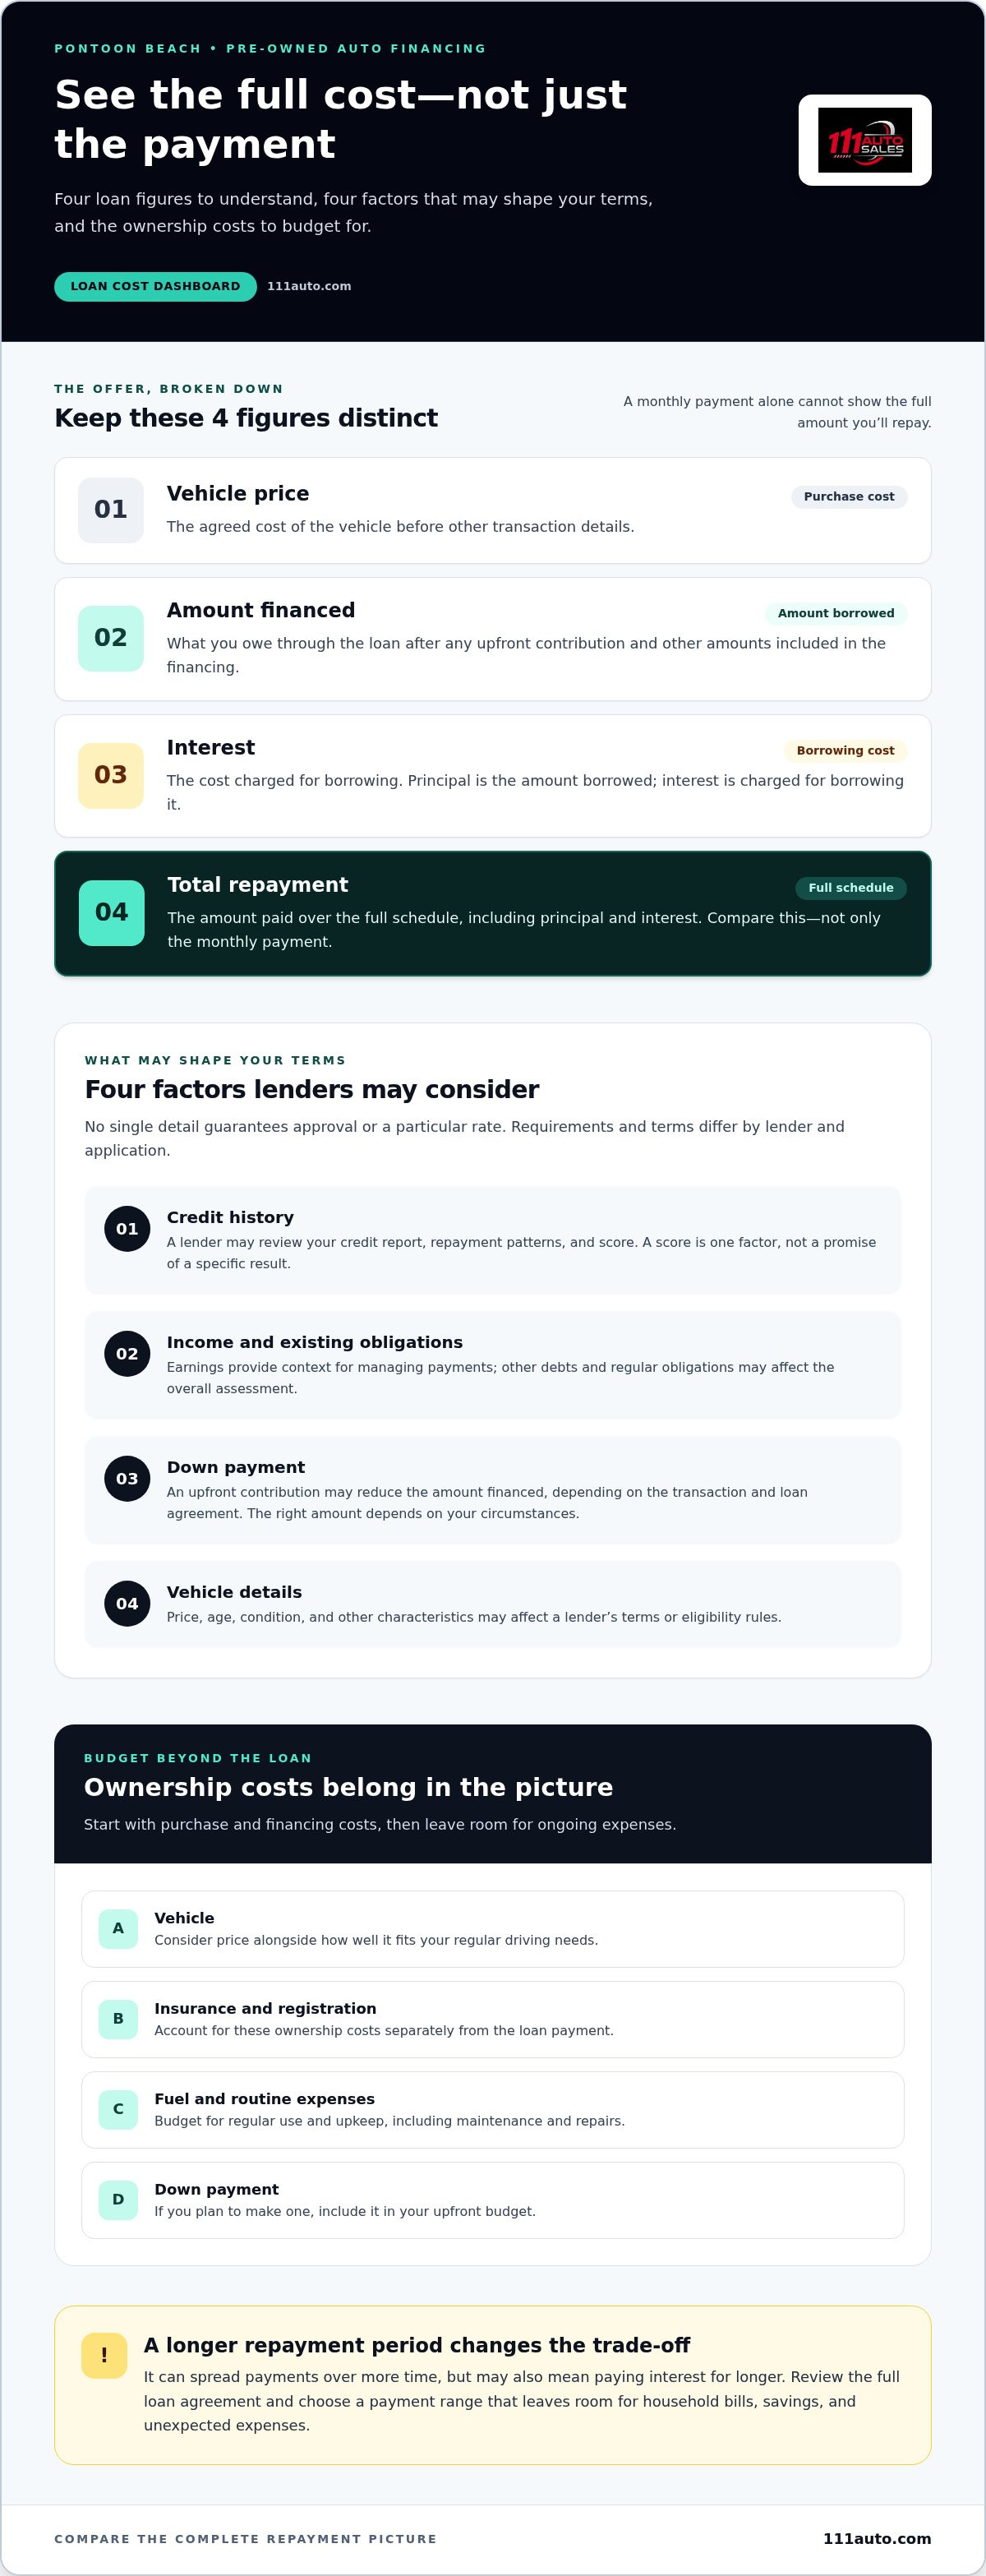
Keep four figures distinct when assessing an offer. The vehicle price is the agreed cost of the car before other transaction details. The amount borrowed, also called the amount financed, is what you owe through the loan after accounting for any upfront contribution and other amounts included in the financing. Interest is the cost of borrowing. Total repayment is the amount paid over the full schedule, including principal and interest. Understanding these terms makes it easier to compare Car finance options and see how a loan fits into your overall purchase plan.
How does a pre-owned auto loan work?
After choosing a vehicle and agreeing on its purchase details, you apply for financing. If the financing provider approves the application, the loan agreement sets out the amount financed, interest, payment schedule, and other applicable terms. You then make scheduled repayments according to that agreement. The payment amount depends on how much you finance, the interest charged, and the repayment period.
Principal is the amount borrowed; interest is the cost charged for borrowing it. Your repayments go toward the loan according to its terms. A longer repayment period can spread payments over more time, but it may also mean paying interest for longer. Review the full agreement rather than relying on a single monthly-payment figure.
What should Pontoon Beach shoppers include in a car budget?
Set your budget before comparing vehicles or loan offers. Start with the purchase and financing costs, then leave room for ongoing ownership expenses. Include insurance, registration, fuel, and routine costs such as maintenance and repairs. These expenses vary by vehicle and personal circumstances, so use realistic estimates for the options you’re considering.
- Vehicle: Consider the price alongside how well the vehicle suits your regular driving needs.
- Insurance and registration: Account for these ownership costs separately from the loan payment.
- Fuel and routine expenses: Budget for regular use and upkeep, not just the purchase.
- Down payment: If you plan to make one, include it in your upfront budget. It can affect the amount financed, but the right amount depends on your circumstances.
Choose a payment range that leaves room for household bills, savings, and unexpected expenses. A payment that looks manageable on its own may feel different once insurance and daily driving costs are included. For shoppers exploring pre-owned auto loans Pontoon Beach, starting with total ownership costs can help narrow vehicle choices without stretching the rest of the household budget.
Which Factors Shape Pre-Owned Auto Loan Terms and Approval?
Financing decisions depend on several applicant and vehicle factors. No single detail guarantees approval or a particular rate. Lenders may consider whether the proposed payment fits your financial picture, how you’ve handled credit, and what vehicle secures the loan. Eligibility requirements and terms differ, so an offer that works for one buyer may not be available to another.
Factors that may come into play include:
- Credit history: Credit reports and repayment patterns can help a lender assess past borrowing behavior.
- Income and existing obligations: Income provides context for your ability to manage payments, while other debts and regular obligations may affect the overall assessment.
- Down payment: Depending on the agreement, paying part of the purchase upfront may reduce the amount financed.
- Vehicle details: Price, age, condition, and other vehicle characteristics may affect a lender’s terms or eligibility rules.
How can credit history affect a used car loan?
A lender may review your credit report, repayment history, and score as part of an application. A score is one factor, not a complete picture or a promise of a specific result. Before applying, review your credit information for errors, such as an account or payment record you don’t recognize. Correct information helps ensure the application reflects your actual history, though it can’t guarantee a particular decision.
Income and current obligations add context. A lender may consider information about your earnings alongside recurring debt payments when evaluating an application. Prepare accurate details, and don’t assume that a single credit score tells the whole story. The Consumer Financial Protection Bureau auto loan guide offers additional consumer-focused information about understanding and comparing auto financing.
Why do the vehicle and down payment matter?
The vehicle’s price influences how much you may need to borrow. A down payment can reduce the amount financed, depending on the transaction and loan agreement, but there’s no universal amount that suits every buyer. Vehicle age and condition may also matter because lenders set their own policies for the vehicles they finance. Review the terms that apply to the specific vehicle and application.
Consider the full picture, not just one factor. For example, choosing a lower-priced vehicle may reduce the amount you need to finance, while a lender’s rules about vehicle age could shape the available terms. These factors work alongside your credit, income, and obligations. Keep your vehicle choice within the budget you’ve set, then compare the written loan details before deciding.
For shoppers considering pre-owned auto loans Pontoon Beach, 111 Auto Sales offers vehicle financing alongside pre-owned sedans, SUVs, trucks, and vans. Explore the dealership’s pre-owned vehicles and financing options as you consider which vehicle and financing arrangement fit your needs.
Comparing Pre-Owned Auto Loan Offers Beyond Payment
A monthly payment is useful, but it doesn’t tell you the full cost of a loan. Compare the details behind each offer using the same vehicle price and, where possible, the same amount financed. Check that each proposal includes the same items, and note anything that’s unclear before deciding.
Which loan details should buyers compare side by side?
Make a simple comparison sheet. Record the figures from each offer, distinguishing amounts due upfront from amounts included in the loan. APR can help compare borrowing costs when disclosed, but review the lender’s explanation and the agreement’s terms rather than treating one number as the whole story.
- APR: Record the annual percentage rate shown for the loan. Check how it’s described in the lender’s disclosure.
- Payment and frequency: Note the scheduled amount and how often it’s due.
- Repayment term: Record how long payments continue.
- Amount financed: Compare the amount being borrowed, including any items added to the loan.
- Fees and total repayment: Note disclosed fees and the total amount scheduled to be repaid over the loan term.
Disclosure terms and lender practices can differ, so compare like with like. If a figure’s meaning isn’t clear, use the written loan disclosure and agreement to understand what it includes. This helps show whether an apparent difference comes from the rate, term, amount financed, or another part of the offer.
What does the loan term change?
The repayment term affects both the size of scheduled payments and how long you remain responsible for the loan. A longer term can spread repayment over more time, which may lower the payment amount. But interest may accrue for longer, so the total borrowing cost can differ from a shorter-term offer. The exact outcome depends on the loan’s terms.
Consider a hypothetical comparison: two offers finance the same amount at the same APR, but one has a longer repayment period. Its scheduled payment may be lower, while the borrower makes payments for longer and could pay more interest overall. Use each offer’s disclosed total repayment to see the actual difference. Don’t infer total cost from the monthly figure alone.
Also separate the core vehicle loan from optional products. An optional product may have its own cost, and if that cost is added to the amount financed, it can increase the balance and affect payments and total repayment. Review whether each item is optional, what it costs, and how it’s treated in the written agreement. For pre-owned auto loans Pontoon Beach buyers are comparing, this side-by-side approach keeps the decision grounded in complete, comparable loan details.
Preparing for a Pontoon Beach Pre-Owned Auto Loan
Preparation can make financing easier to evaluate. Work through the steps in order, keeping your budget, application information, vehicle research, and final paperwork together. This helps you assess the car and loan as one decision instead of focusing on a payment in isolation.
- Set your budget. Choose a payment range that leaves room for insurance, fuel, registration, routine upkeep, and other household needs. Decide how much you can comfortably contribute upfront, if any.
- Identify your vehicle needs. Consider how you’ll use the vehicle, which body style fits your routine, and what ownership costs you can manage.
- Review the vehicle. Examine its history and condition, and consider how its age, mileage, and expected upkeep fit your plans.
- Gather application details. Prepare commonly requested information about your identity, residence, income, and employment. Requirements vary by financing provider.
- Read the proposed agreement. Before accepting, review the amount financed, APR, payment schedule, repayment term, and any disclosed fees. Make sure the figures fit the budget you set.
What information should you gather before applying?
Financing providers commonly request information about identity, current residence, income, and employment. Keep the details accurate and consistent, and organize relevant records so you can respond efficiently if asked. Exact documents and application requirements depend on the financing provider, so use this as a preparation guide rather than a universal checklist or a guarantee of what an application will require.
If you’re considering a sedan, review the used sedan financing guide for additional context as you compare vehicle needs and financing considerations. The same preparation applies across pre-owned vehicle types: understand the car you’re considering and the obligations attached to financing it.
What should you review before accepting loan terms?
Read the written terms carefully before agreeing. Confirm the amount financed, APR, scheduled payment and frequency, repayment term, and disclosed fees. Check whether additional products or costs are included in the amount financed, and compare the agreement’s total repayment with your budget. If a figure or clause is unclear, pause and seek clarification through the relevant financing process before accepting.
Review the vehicle alongside the loan. A financing offer doesn’t tell you the vehicle’s history or condition, and a vehicle that suits your needs still has to fit your full ownership budget. For Pontoon Beach shoppers comparing pre-owned auto loans, reviewing both sides can help prevent a manageable-looking payment from obscuring other costs or terms.
Ready to put your preparation into practice? Explore pre-owned vehicles and financing at 111 Auto Sales in Pontoon Beach.
Explore Pre-Owned Auto Loans and Vehicles at 111 Auto Sales in Pontoon Beach
Once you’ve set a budget and learned what to review in a loan offer, connect those plans to the vehicle you need. 111 Auto Sales is a used vehicle dealership in Pontoon Beach offering pre-owned sedans, SUVs, trucks, and vans, along with vehicle financing options. Its selection includes vehicles priced under $10,000, giving budget-conscious shoppers another price range to consider. A vehicle or financing arrangement should still fit your individual needs and budget.
How can financing support your vehicle search?
Start with how you’ll use the vehicle. A sedan may suit everyday commuting, while an SUV, truck, or van may better match other transportation needs. Keep your budget in view as you browse, and consider the vehicle’s overall ownership costs as well as its purchase price. This helps you focus on options that fit your priorities instead of choosing based only on a payment estimate.
Financing is part of the pre-owned vehicle shopping process at 111 Auto Sales. As you consider a vehicle, financing options can be explored in relation to your application and the vehicle you’re purchasing. Specific rates, terms, down-payment expectations, and approval outcomes depend on the applicable financing decision, so don’t assume a particular payment or offer is guaranteed. Review the terms presented to you and weigh them against the budget you prepared.
Shoppers researching pre-owned auto loans Pontoon Beach can use the dealership’s vehicle selection as a starting point for a practical comparison. Note which body styles meet your needs, then consider vehicle condition, history, and ownership expenses alongside financing details. That way, your decision accounts for both the vehicle and the commitment involved in purchasing it.
Which related financing guides may help next?
If an SUV is on your shortlist, the used SUV financing guide offers vehicle-specific context for your research. Use it to explore considerations related to financing an SUV, then return to your budget and the terms available for the vehicle you’re considering. The right choice depends on how the vehicle fits your transportation needs and financial plans.
Take time to review the options and financing information together. A considered choice should make sense for your day-to-day needs as well as your budget.
Explore 111 Auto Sales vehicles and financing options in Pontoon Beach at your own pace.
Take the Next Step With a Clear Plan
Your next move doesn’t have to be a commitment. Use your budget and loan comparison notes to narrow your vehicle search, then consider how each option fits your daily needs and financial priorities. Careful review can help you move forward with greater confidence.
If you’re considering pre-owned auto loans Pontoon Beach, 111 Auto Sales offers financing options for shoppers in Pontoon Beach and nearby Metro East communities. Its selection includes vehicles priced under $10,000, providing another range to explore as you compare potential purchases. Financing terms and approval depend on the specific application and offer.
Browse the available options and keep your priorities in view. Explore pre-owned vehicles and financing options at 111 Auto Sales to take a practical next step toward your vehicle search. With a clear budget and thoughtful comparison, you can approach the decision with confidence.
Frequently Asked Questions
For shoppers in Pontoon Beach and nearby Granite City, Collinsville, St. Louis, Belleville, Maryville, Troy, Alton, Highland, O’Fallon, Glen Carbon, Swansea, and Cahokia, these answers clarify common financing questions before you apply.
Can I get a pre-owned auto loan with bad credit?
Possibly, but a lender decides based on its own requirements, and bad credit doesn’t guarantee either approval or denial. The lender may consider your credit history alongside income, existing debt, the vehicle, and other application details. Before applying, review your credit report and correct errors if possible. For pre-owned auto loans Pontoon Beach shoppers are considering, compare the complete written terms, not just whether an application receives an offer.
Does applying for an auto loan affect my credit score?
It can, depending on the application and how the lender checks your credit. A formal application may result in a hard inquiry, which can affect a score; checking your own credit or receiving some prequalification estimates may use a soft inquiry instead. Ask what type of credit check will occur before submitting an application. If you’re shopping around, keep applications within a focused period, since scoring models may treat auto-loan inquiries differently.
Can I apply for a pre-owned auto loan if I am self-employed?
Yes, self-employment doesn’t automatically prevent you from applying. A financing provider may ask for information to document income, such as tax records, bank statements, or other financial documentation. Requirements vary, so don’t assume every lender needs the same paperwork. Prepare a clear, accurate picture of your income and existing obligations, and be ready to explain income that changes from month to month or by season.
Is a down payment required for a pre-owned auto loan?
Not in every case. Whether a down payment is required depends on the financing provider, the application, the vehicle, and the loan terms offered. If you plan to contribute money upfront, account for it separately from funds needed for registration, insurance, or other immediate expenses. Before agreeing, check how the down payment changes the amount financed and make sure you’ll still have enough cash for planned household needs.
Can I pay off a pre-owned auto loan early?
It may be possible, but the loan agreement controls how early payoff works. Review it for any prepayment charge, payoff instructions, and the method used to calculate the remaining balance. Don’t rely only on the balance shown on a regular statement, since it may not reflect the amount required to close the loan on a later date. Request a payoff figure through the financing provider’s stated process before sending payment.
Can I finance a used vehicle priced under $10,000?
Yes, a vehicle in that price range may be financed, subject to the financing provider’s requirements and the specific vehicle and application. 111 Auto Sales has a selection of pre-owned vehicles priced under $10,000 and offers vehicle financing options. Approval depends on the application and applicable terms. Review the complete purchase and loan details for the vehicle you’re considering before making plans around it.
Is pre-approval the same as final auto loan approval?
No. Pre-approval is generally an initial indication based on information available at that stage, while final approval may depend on further review. The financing provider may need to verify application details and assess the specific vehicle and final transaction. Treat a pre-approval as a useful planning step, not a promise of final terms. Before signing, review the completed agreement and make sure the amount, payment schedule, and other terms match what you accept.


